Categories
Bookkeeping

How CPA Firms Can Hire a Dedicated Bookkeeping Team in India Without Losing Control: A Complete 2026 Guide

If you run a CPA firm, you know how quickly bookkeeping can become a capacity problem. Every new client adds transaction coding, bank reconciliations, accounts payable and receivable, month-end schedules, and questions that someone must resolve before the books are ready for review. Your existing team still has tax returns, client deadlines, and higher-value advisory work to manage.

Hiring locally can help, but recruiting, training, compensation, and retention take time. The U.S. Bureau of Labor Statistics reports a median annual wage of $50,670 for bookkeeping, accounting, and auditing clerks in May 2025. It projects approximately 144,100 openings per year from 2025 through 2035, primarily to replace workers who transfer to other occupations or leave the labor force. These figures provide context for the U.S. bookkeeping labor market; they do not, by themselves, establish the cost savings or business case for outsourcing.

For some firms, hiring a dedicated bookkeeping team in India offers another way to build capacity. This model can provide access to accounting professionals, support recurring workloads, and let firms plan coverage around their operating schedules. India’s time zone can also support planned handoffs, although meaningful overlap depends on the working hours agreed with the provider.

The important question is how to build that arrangement without losing visibility over client work, quality, or decisions. Here is how to evaluate the model, compare providers, understand costs, and establish controls before work begins.

TL;DR

  • Why consider it: Hiring a dedicated bookkeeping team in India can add capacity for recurring work like reconciliations, AP/AR, and month-end support without immediately growing local headcount.
  • Choose the right model:Dedicated bookkeeper, supervised team, shared resources, project-based, or seasonal. Match it to your volume, complexity, and review capacity.
  • Hire in steps: Measure your workload, define scope and ownership, vet providers on U.S. experience, supervision and continuity, agree on review checkpoints, then run a controlled pilot.
  • Costs: Indicative market ranges are about $10 to $25 per hour or $1,400 to $2,000 per month for a full-time bookkeeper. Compare total cost, including onboarding, review time, rework, and backup coverage, not just the quote.
  • Keep control: Set measurable service expectations, use named accounts, least-privilege access and MFA, and check Section 7216 and FTC Safeguards Rule requirements before sharing client data.
  • Bottom line: It works best with recurring workloads, documented procedures, and firm-level review. Choose it for quality and continuity, not price alone.

Why Are CPA Firms Considering Bookkeeping Teams in India?

The case for India is not simply about location. It is about whether a provider can supply the right skills, follow your procedures, and deliver consistent work within an arrangement your firm can supervise.

Access to a broader accounting talent pool

India offers CPA firms another market in which to recruit accounting and finance professionals. However, not every candidate has experience with U.S. accounting practices or outsourced bookkeeping workflows. Ask providers how they assess relevant bookkeeping experience, software proficiency, documentation practices, and communication skills, and whether assigned professionals have worked with U.S. clients.


Flexible coverage for recurring workloads

A dedicated arrangement can be useful when a firm has a predictable volume of monthly bookkeeping, reconciliations, or cleanup work. Rather than repeatedly assigning tasks to whichever employee has spare time, the firm can establish responsibility for a defined client portfolio or workflow.

Time-zone differences that can support planned handoffs

India Standard Time is UTC+5:30. It is 9.5 hours ahead of U.S. Eastern Daylight Time and 10.5 hours ahead of Eastern Standard Time. That difference can allow work to progress outside a firm’s usual local hours, provided the provider’s schedule, task dependencies, and communication windows are planned in advance.


The difference can also make urgent collaboration harder. Firms should agree on overlapping hours for questions, exceptions, and review discussions instead of assuming that time-zone separation automatically speeds up delivery.


Capacity without immediately expanding local headcount

A provider may offer full-time dedicated, part-time, or project-based support, depending on your firm’s workload and coverage requirements. A part-time arrangement may suit a smaller, predictable volume of recurring bookkeeping, while a dedicated bookkeeper or team may be more appropriate when work arrives consistently across multiple client accounts. Project-based support can help address a defined cleanup backlog or reconciliation project.


Choose the model based on transaction volume, workload consistency, task complexity, and available review capacity. Estimate the hours required, identify peak periods and deadlines, and assess backup needs before committing to a level of support.

Not sure how much bookkeeping capacity your firm actually needs?

Share your client load, software, and review process with Unison Globus to map out a dedicated bookkeeping setup that fits your firm.

What Does a Dedicated Bookkeeping Team Actually Do?

CPA firms often start with a dedicated resource and later choose to hire offshore bookkeepers as workload volumes increase.

  • Transaction recording and categorization: Record transactions using the firm’s chart of accounts and documented coding rules.
  • Bank and credit card reconciliations: Reconcile account activity, investigate discrepancies, and document unresolved items.
  • Accounts payable and receivable: Maintain records, track outstanding balances, and prepare agreed reports.
  • Month-end close support: Prepare reconciliations, schedules, journal-entry support, and other close documentation.
  • Supporting documentation: Organize invoices, receipts, statements, and other records needed for review.
  • Bookkeeping reports: Prepare agreed reports and schedules for the firm’s review.

The firm should define which tasks the team owns, which require approval, and which remain with the firm. Complex accounting judgments, unusual transactions, client-specific exceptions, and final reporting decisions should follow the firm’s established escalation and review procedures.


Before assigning work, assess how consistently the tasks recur, how complete the source records are, and how much review they require. Standardized, repeatable work is generally easier to delegate than work that depends on undocumented client knowledge or frequent judgment calls.

Which Hiring Model Fits Your CPA Firm?

Not every firm needs a full-time team. Many firms compare dedicated resources with broader accounting outsourcing services before selecting the most suitable delivery model. When evaluating bookkeeping outsourcing services in India, compare the available models against the volume, complexity, and predictability of your bookkeeping work.

Hiring model Best suited for Main consideration
Directly hire an individual in India Firms prepared to manage international employment or contracting arrangements Recruitment, employment terms, supervision, and continuity remain the firm’s responsibility
Dedicated bookkeeper through a provider Firms with recurring work that needs consistent ownership Confirm whether the resource is genuinely dedicated and how absences are covered
Dedicated team with a supervisor Larger portfolios, multiple clients, or workflows needing coordination Requires clear ownership, escalation paths, and defined review responsibilities
Shared bookkeeping resources Smaller or fluctuating workloads Confirm availability, priorities, and turnaround commitments
Project-based support Cleanup, backlog reduction, or a defined reconciliation project Agree on deliverables, deadlines, and acceptance criteria
Seasonal support Temporary increases in workload Plan onboarding and access well before the busy period

A dedicated bookkeeper may suit a firm with a consistent, manageable workload. Consider a supervised team when multiple client portfolios, more complex workflows, or backup coverage require additional coordination.

Is Your CPA Firm Ready for a Dedicated Bookkeeping Team?

A dedicated bookkeeping team may suit a firm with recurring work, documented procedures, and enough internal capacity to oversee the engagement. Before proceeding, confirm that the firm can provide usable records, assign an accountable manager, and review completed work within the required timeframe.

  • Workload consistency: Do you have enough recurring bookkeeping work to support a dedicated resource or team?
  • Process readiness: Are your bookkeeping procedures, client-specific accounting rules, and documentation standards clearly defined?
  • Source-document quality: Can your firm provide complete records and resolve missing information without repeatedly delaying the workflow?
  • Review capacity: Can a designated reviewer check reconciliations, supporting schedules, and unresolved exceptions within the required timeframe?
  • Management ownership: Is someone responsible for assigning work, answering technical questions, and resolving escalations?

If these foundations are missing, standardize the relevant procedures or begin with a limited pilot before expanding the engagement.

How to Hire a Dedicated Bookkeeping Team in India

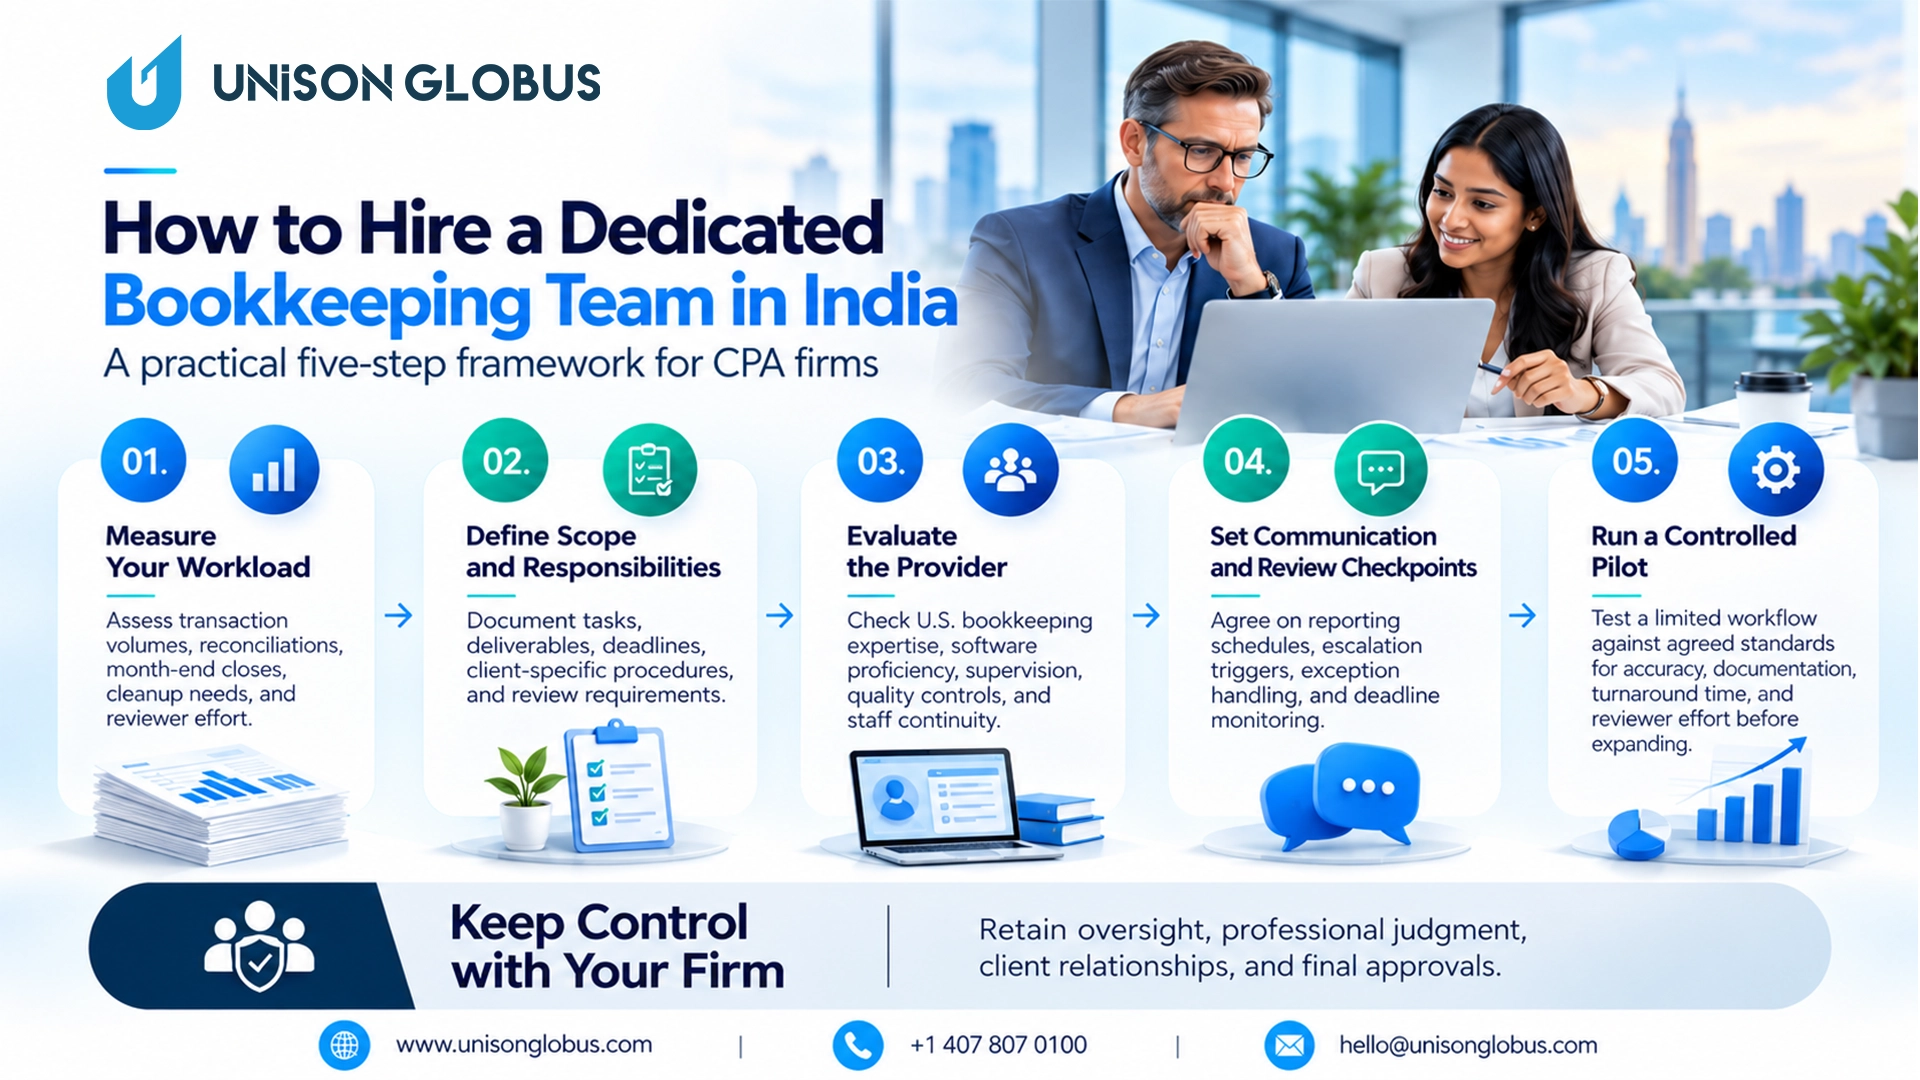
Hiring a dedicated bookkeeping team requires more than selecting a provider. CPA firms should define the work to be delegated, assess the provider’s capabilities, establish review and communication procedures, and test the working arrangement before expanding the scope.

1. Measure your actual workload

Start with the work rather than a headcount target. Review the last three to six months of bookkeeping activity and identify:

  • Number of client entities and monthly transactions.
  • Bank and credit card accounts require reconciliation.
  • Frequency of month-end closes.
  • Volume of AP and AR activity.
  • Cleanup requirements and recurring exceptions.
  • Average time spent reviewing and correcting work.
  • Seasonal changes in workload.

Separate routine tasks from work require judgment or extensive client communication. This gives you a more realistic view of the capacity you need. Firms managing bookkeeping alongside compliance and reporting requirements often combine bookkeeping support with hiring accounting outsourcing services to create a more scalable back-office structure.


2. Define the scope and responsibilities

Prepare a written scope that identifies the tasks the provider will perform, the records it will receive, and the deliverables your firm expects.


When assigning bookkeeping work to a dedicated bookkeeper in India, document the expected deliverables, deadlines, exception-handling procedures, and review requirements before the engagement begins.


For example, a monthly bookkeeping workflow might require reconciliations, an exception list, supporting schedules, and a completed checklist by an agreed date. Specify who answers questions, who resolves discrepancies, and who approves adjustments.


Prepare an onboarding pack that translates the agreed scope into client-specific working instructions. Include the chart of accounts, accounting policies, reconciliation procedures, close calendar, supporting-document requirements, recurring journal entries, known exceptions, and escalation contacts. Walk the assigned team through representative files, then ask it to complete a sample workflow before assigning live work.

ActivityBookkeeping teamCPA firm
Record transactions using approved rulesPrepareSet rules and clarify exceptions
Reconcile accountsPrepare and documentReview exceptions and resolve judgment matters
Prepare month-end schedulesCompileReview and approve as appropriate
Identify missing recordsFlag and trackCoordinate with the client when authorized
Propose adjusting entriesPrepare supporting documentation where agreedReview and approve under the firm’s established process
Final financial reporting or client adviceProvide agreed supporting schedules and documentationReview, make decisions, communicate with clients, and approve or sign off as required by the engagement and applicable professional obligations

Align the final division of responsibilities with the engagement terms, client authorizations, and applicable professional obligations.


3. Evaluate providers, not just individual resumes

When comparing offshore bookkeeping services, assess the delivery model as carefully as the technical skills of the assigned staff.


Ask prospective providers:

  • What experience do team members have with U.S. bookkeeping workflows?
  • Which accounting platforms do they use regularly?
  • How are tasks assigned, tracked, and reviewed?
  • Who supervises the team and handles escalations?
  • How does the provider maintain continuity when an assigned bookkeeper is absent or leaves?
  • How are client data, access permissions, and confidentiality handled?
  • Can the provider demonstrate sample workpapers and review documentation?
  • How are performance issues reported and corrected?

Confirm that client-specific procedures are documented, qualified backup staff can cover absences, and the provider has a defined process for transferring open tasks and knowledge when staffing changes. Agree on how your firm will be notified and how access permissions will be updated.


Ask providers to demonstrate their workflow using sample task records, review notes, and exception reports. This helps you assess how their stated procedures operate in practice rather than relying solely on interview responses.


The Journal of Accountancy’s guidance on working with third-party experts also emphasizes due diligence, clear responsibilities, confidentiality, and appropriate client communication.


4. Agree on communication and review checkpoints

Agree on communication windows and a reporting schedule for task status, unresolved questions, and approaching deadlines. A practical arrangement could include a daily exception log, a weekly workload review, and a monthly discussion of recurring issues.


Define escalation triggers in advance, such as unreconciled differences above an agreed threshold, missing source documents, duplicate transactions, unexpected account balances, or a close at risk of missing its deadline.


5. Start with a controlled pilot

Start with a limited group of clients or a defined workflow. Before work begins, confirm software access, source-document availability, procedures, reporting deadlines, and escalation contacts. Agree on acceptance criteria covering reconciliation accuracy, supporting-document completeness, exception handling, turnaround times, reviewer effort, and communication. Compare the results with your firm’s standards, address any training or workflow gaps, and expand only when the work meets the agreed criteria.
What Determines the Cost of Hiring a Bookkeeping Team in India?

Pricing depends on the engagement model, workload, required experience, supervision, and task complexity. If your firm plans to outsource bookkeeping to India, compare the following cost structures and clarify what each quote includes.


CPA firms should evaluate total value rather than hourly rates alone. Dedicated bookkeeping support that includes quality reviews, backup coverage, documented procedures, and continuity planning often delivers greater long-term value than lower-cost options with limited oversight.

Cost modelHow it worksWhat to clarify
HourlyPay for recorded hoursRates, minimums, approval rules, and time reporting
Monthly dedicated resourcePay a recurring fee for agreed full-time or part-time capacityIncluded capacity, scope, minimum commitment, backup coverage, and additional-hour charges
Fixed-fee workflowPay for a defined service or deliverableTransaction limits, complexity assumptions, and out-of-scope work
Project-basedPay for a defined cleanup or backlog projectData condition, deliverables, acceptance criteria, and change requests
HybridCombine recurring support with project or seasonal capacityHow additional work is approved and priced

As a general market guide, hourly rates for trained bookkeepers in India typically fall between $10 and $25, with senior or more specialized staff priced higher. Dedicated full-time arrangements are often quoted at roughly $1,400 to $2,000 per month for one bookkeeper. These are indicative ranges, not quotes.


When calculating the cost of hiring a bookkeeping team in India, compare the full operating cost rather than the quoted rate alone. Include onboarding, software and access arrangements, management time, review effort, rework, and backup coverage. Ask each provider to price the same scope wherever possible, so you can see whether a lower quote leaves important responsibilities outside the agreement.

How Can Your Firm Maintain Control Over Outsourced Bookkeeping?

Outsourcing changes who perform the work. It does not eliminate the need for oversight.

Set measurable service expectations

Agree on practical measures such as:

  • Reconciliations are completed by the agreed date.
  • Percentage of assigned work completed on time.
  • Number and age of unresolved exceptions.
  • Corrections required during review.
  • Completeness of supporting documentation.
  • Time taken to respond to questions.
  • Reviewer time required per completed workflow.

Make task ownership and review corrections visible in the workflow. Assign responsibility for preparing each task, reviewing it, resolving questions, and correcting identified issues. Track task status, due dates, outstanding dependencies, and review outcomes. When a reviewer returns work for correction, record the finding, assign responsibility for resolving it, and confirms that the revised work meets the agreed criteria before closing the task.


Control of access to client data

Use-named user accounts, least-privilege permissions, and multifactor authentication (MFA) where available. Avoid sharing passwords or granting unrestricted access simply to make onboarding easier.


During provider due diligence, confirm where client data is stored, who can access it, and how the provider protects information in transit and at rest. Ask how the provider approves access, removes permissions when responsibilities change, and manages subcontractors who may access client information.


Agree on how suspected security incidents will be recorded, investigated, and reported to your firm, including who must be notified and the applicable notification timelines. Also establish how client records will be returned or securely deleted at the end of the engagement, including how any retained copies will be handled.


Record the agreed controls, incident-notification obligations, and data-handling requirements in your firm’s vendor-management procedures and service agreement. Ask the provider to demonstrate relevant safeguards during due diligence and review access periodically.


The IRS advises tax professionals to maintain a written information security plan (WISP) and address risks involving service providers. The FTC Safeguards Rule applies to covered financial institutions, including certain tax preparation firms; applicability should be assessed based on the firm’s circumstances.


Review confidentiality and tax information requirements

If the engagement involves tax return information, determine how Internal Revenue Code Section 7216 and its regulations apply to the proposed arrangement. The rules restrict the use and disclosure of tax return information by tax return preparers, subject to applicable requirements, exceptions, and limitations. Disclosures to service providers outside the United States may trigger specific consent requirements, including rules governing the content and execution of taxpayer consent. Before sharing covered information, have a qualified tax or legal adviser review the arrangement and confirm that the applicable requirements are met.

How Unison Globus Approaches Bookkeeping Support

At Unison Globus, we provide dedicated bookkeeping professionals who work within your firm’s existing accounting software, workflows, and review processes. Each engagement is structured around your workload, task ownership, reporting requirements, and review checkpoints, helping your team maintain visibility into work in progress and outstanding items. Many CPA firms also use our tax preparation services during busy season to free up internal resources for advisory and client management activities.


As tax and accounting workflows evolve, our professionals are also ready to work within AI-enabled tools and changing technology ecosystems. They combine digital fluency with accounting expertise to support organized workflows, quality checks, and review-ready deliverables while your firm retains control over technical decisions, client relationships, and final approvals. Firms looking to consolidate recurring back-office functions often combine bookkeeping support with outsourced payroll services for greater operational efficiency.

Could your firm use additional bookkeeping capacity without adding to reviewer workload?

Discuss your firm’s bookkeeping volume, workflow requirements, and review capacity with Unison Globus.

Common Mistakes to Avoid When Hiring Bookkeepers in India

Several avoidable mistakes can create rework, delays, or unclear accountability when a CPA firm brings on a bookkeeping team. Use this checklist to review the main risks before and during onboarding.

Common mistakeWhy it mattersHow to avoid it
Choosing on price aloneThe quoted rate may exclude supervision, backup coverage, or rework.Compare quotes using the same scope and include internal review and management costs.
Delegating without documented proceduresBookkeepers may classify transactions or handle exceptions inconsistently across client accounts.Check that client-specific instructions and escalation rules are complete before assigning live work.
Assuming all accounting experience transfers to U.S. workGeneral accounting knowledge and software familiarity do not guarantee experience with U.S. bookkeeping practices.Assess relevant experience and review sample work before assigning live client work.
Giving broad system accessUnnecessary permissions can expose sensitive client information and increase security risks.Grant only the access required for assigned tasks and remove permissions when they are no longer needed.
Starting with too many clientsWorkflow problems may affect multiple accounts before the team has demonstrated consistent performance.Limit initial assignments until the provider has demonstrated that it can meet the agreed standards.
Treating provider review as a substitute for firm oversightUnclear approval boundaries can create gaps in accountability and quality control.Retain clear preparation, review, approval, and sign-off responsibilities within the firm.

Accounting firms outside the U.S. are exploring the same model

Capacity pressure in bookkeeping is not unique to the U.S. In the UK, accounting firms look offshore for recurring work such as reconciliations, payables, receivables, and month-end support, with local requirements like VAT, Making Tax Digital, and UK GDPR shaping how work is scoped and secured. In Australia, firms do the same for recurring bookkeeping, with GST, BAS lodgement, and Australian privacy requirements shaping the arrangement. In both markets, the core questions match: clear scope, documented procedures, secure access, and firm-level review.


Time zones also differ by market. India is 4.5 to 5.5 hours ahead of the UK, depending on daylight saving, and 4.5 to 5.5 hours behind Australia’s eastern states, so overlap is often easier to plan than with U.S. firms.

Is Hiring a Dedicated Bookkeeping Team in India Right for Your Firm?

A dedicated bookkeeping team is worth considering when recurring work exceeds the capacity your firm can manage efficiently and the engagement can be supported by clear procedures and appropriate review. Bookkeeping outsourcing for CPA firms makes sense only when it meets quality, continuity, and workload requirements, not simply when the quoted cost looks attractive.


If your firm is considering this model, explore how Unison Globus can support your bookkeeping needs through dedicated teams, offshore bookkeepers, and broader accounting outsourcing services tailored to CPA firms.

Frequently Asked Questions

To hire a dedicated bookkeeping team in India, first document your recurring workload, software, deadlines, and review requirements. Compare providers on relevant U.S. bookkeeping experience, supervision, security, communication, and continuity. Begin with a limited pilot before assigning a larger client portfolio.

CPA firms commonly outsource transaction recording, bank and credit card reconciliations, AP and AR tracking, general ledger maintenance, supporting schedules, and agreed cleanup work. The scope should specify which tasks the provider performs and which decisions, approvals, or client communications remain with the CPA firm.

If you plan to hire a bookkeeper from India, an individual may suit a stable, limited workload when your firm can manage supervision and continuity. A dedicated team may be more appropriate when you need broader coverage, coordination, or backup capacity. The right choice depends on workload, complexity, and the provider’s delivery model.

Offshore bookkeeping in India is commonly priced from about $10 to $25 per hour, or roughly $1,400 to $2,000 per month for a dedicated full-time bookkeeper. Actual cost depends on scope, experience, supervision, and backup coverage. Request comparable quotes and include onboarding, review time, rework, and access arrangements when evaluating total cost.

Use appropriate confidentiality terms, role-based access, multifactor authentication where available, documented security procedures, and a written incident-response process. Assess the provider’s safeguards and determine whether requirements such as Section 7216 or the FTC Safeguards Rule apply to your circumstances.

CPA firms can maintain control by defining task ownership, setting review and escalation rules, restricting system access, and tracking unresolved exceptions. Regular performance reviews help identify workflow problems while the firm retains responsibility for client decisions and final review.
Categories
Bookkeeping Tax

Why Post Tax Season Bookkeeping Cleanup Is Critical for US CPA Firms

Tax season is over. The filing rush has passed, the late nights are behind you, and your team is finally coming up for air. It feels like the right moment to exhale and let things settle.

But for US CPA firms, the weeks after April 15th can be just as consequential as the weeks before it. The post-tax season bookkeeping backlog that quietly piled up during the rush does not disappear on its own. It sits there, growing, until someone decides to deal with it through proper post tax season accounting processes. 

The problem is that most firms delay that decision for far too long. And that delay carries a cost that rarely shows up clearly on any report, but is very real and very measurable.

What Is Actually Happening at US CPA Firms Right Now

Before diving into what post-tax season bookkeeping cleanup costs your firm, it helps to understand the broader environment these backlogs are forming in.


The 2026 tax season was one of the most demanding in recent memory for CPA firms across the United States. According to CPA Trendlines Busy Season Barometer data tracking more than 300 accounting professionals, sentiment among tax practitioners fell more than 30 points by April 2026. Fewer than 6% of respondents reported a “much better” year, while nearly three times that number said things were “much worse.” Firms reported doing more work and generating more revenue, but keeping less of it as margins tightened.


At the same time, the IRS itself has been under significant strain. According to the Treasury Inspector General for Tax Administration, IRS workforce reductions between January and May 2025 reduced staffing from roughly 103,000 to under 77,000 employees. That kind of institutional pressure means slower IRS responses, correspondence bottlenecks, and more burden shifting to CPA firms and their clients to manage the fallout.

Add to this the compliance complexity introduced by the One Big Beautiful Bill Act and new IRS deduction categories for overtime pay, vehicle loan interest, and senior bonuses, and you have a filing season that stretched CPA firm bandwidth to the limit.


The result? Bookkeeping backlogs that are deeper than usual, at a time when teams have even less capacity to address them, making CPA bookkeeping backlog management more critical than ever.

The Real Cost of Delaying Post-Tax Season Bookkeeping Cleanup

Most firms assume the backlog is just a workflow inconvenience, something that will sort itself out once the pace slows down. It rarely does. Below are the five ways delayed post-tax season bookkeeping cleanup quietly damages your firm, your team, and your client relationships.

1. Billable Hours Are Lost to Low-Value Work

Every hour a senior CPA spends on bookkeeping catch-up after tax season is an hour not spent on advisory services, client development, or higher-margin work. When your qualified professionals are manually reconciling months of transactions, sorting through uncategorized expenses, and chasing missing documentation, your firm is effectively paying premium rates for entry-level output.

According to Ignition’s 2025 US Accounting and Tax Pricing Benchmark, which surveyed 219 US-based accounting firms, 80% of firms plan to raise prices in 2026, but those increases are concentrated in tax preparation and advisory work. Routine bookkeeping, by contrast, faces downward pricing pressure as automation and outsourcing continue to commoditize it. The gap between what firms can charge for advisory versus transactional bookkeeping work is widening every year. When your senior staff handle that lower-margin work, the cost to the firm compounds on both ends.

Firms that use bookkeeping cleanup services in the USA specifically designed for CPA practices, like those offered by Unison Globus, free their internal teams to stay focused on the work that actually commands a premium.

2. Client Trust Erodes Quietly

Clients may not understand your post-tax season workflow, but they notice the symptoms. When financial reports are delayed, when Q1 questions cannot be answered because the books are two months behind, when they cannot get a clear picture of their position before an important business decision, trust starts to slip.

It is not dramatic or sudden. It is the slow kind: fewer referrals, less enthusiasm in renewal conversations, and a willingness to take a competitor’s call that would not have existed a year ago.

Accounting cleanup after tax season is not a housekeeping exercise. For US CPA firms competing on service quality, it is a client retention strategy tied closely to effective accounting cleanup after tax season practices.

3. Financial Red Flags Go Undetected

Clean, current books are how CPA firms catch problems before they escalate. Cash flow shortfalls, uncollected receivables, vendor discrepancies, and payroll errors can all hide inside a bookkeeping backlog for months before surfacing.

What could have been a straightforward correction in May becomes a complex, time-consuming reconciliation problem by September. The longer the post-tax season bookkeeping cleanup is delayed, the more expensive those discoveries become for your firm and your clients, reinforcing the need for structured bookkeeping cleanup strategies for CPA firms.

4. Staff Burnout Extends Well Beyond April

The accounting profession is facing a structural talent crisis, not a temporary hiring blip. The accounting and auditing workforce has shrunk by over 17% since 2020, with more than 300,000 professionals leaving the field. The BLS projects more than 120,000 accounting and auditing job openings every year through 2034, with the pipeline of new graduates unable to keep pace.

A FloQast survey found that nearly 99% of accountants reported experiencing burnout, with 24% describing it as moderate to severe. And a separate AICPA report identified work-life balance as the number one reason accounting professionals leave their firms.

When your team finishes a grueling tax season only to face months of bookkeeping catch-up stacked on their regular workload, that burnout does not end in April. It runs straight through summer. CPA firm turnover averages 15 to 22% annually across the profession, according to AICPA and Rosenberg Survey data, and the fully loaded cost of losing a senior accountant runs between $50,000 and $100,000 once recruiting, onboarding, and client attrition risk are factored in. The CPA bookkeeping backlog is a driver of that turnover that most firm owners consistently underestimate.

5. Growth Capacity Simply Disappears

A firm buried in post-tax season bookkeeping work does not have the bandwidth to take on new clients, expand service lines, or build out advisory offerings. The backlog becomes a ceiling on growth.

According to the AICPA and CPA.com CAS Benchmark Survey, client advisory services practices reported 17% median growth in 2023, with firms projecting 99% median growth over the next three years. That is where the profession is heading. But that growth is only accessible to firms that have cleared the operational weight of backlog work and built the capacity to pursue it through effective outsourced bookkeeping for CPA firms models.

Wondering whether outsourced bookkeeping
for CPA firms could work for your practice?

Why Firms Keep Letting This Problem Repeat

Most CPA firm owners know the backlog exists. The challenge is structural, not a matter of awareness.


After a grinding tax season, the instinct is to let the team decompress. That is fair and appropriate. But without a concrete plan for bookkeeping catch-up services USA, where cyclical workload spikes are a known annual reality, decompression stretches into summer, summer into fall, and the firm enters the next tax season carrying the same unresolved weight as the one before.


The staffing math also does not support an in-house fix. Hiring full-time bookkeepers to handle a cyclical post-season surge does not make financial sense. So the work gets assigned to whoever has a spare moment, which means it gets done inconsistently, if at all.


This is precisely the gap that white-label bookkeeping services for CPAs are built to fill.

How Outsourced Bookkeeping Cleanup Changes the Equation for US CPA Firms

The most effective bookkeeping cleanup strategies for CPA firms increasingly involve outsourced partnerships that absorb the post-tax season surge without adding permanent overhead to the firm’s cost structure.


White-label bookkeeping services for CPAs allow a firm to deliver clean, current client books under its own brand, with all the underlying work handled by an experienced external team operating as a seamless extension of the firm. Clients see professional, consistent service. Internal staff get breathing room. And the backlog is cleared through a structured, documented process, improving how CPAs manage bookkeeping backlog after tax season.


Unison Globus has been providing this kind of support to CPA and accounting firms across the United States for over 19 years. Their outsourced bookkeeping and accounting cleanup services are built exclusively for CPAs, EAs, CMAs, and accounting firms. This is not generic small-business bookkeeping. It is firm-grade support that understands the workflows, documentation standards, and turnaround expectations of a professional accounting practice. They currently partner with more than 1,000 accounting and bookkeeping firms globally.


Here is what US CPA firms that have worked with them have said:


“We began working with Unison to help manage backlogs of bookkeeping and accounting work and were delighted with the quality of work and impressive turnaround times, which really helped us at a time of exceptional growth. We appreciate the flexibility Unison provides to increase resources as we need them and have used the offshore team to help build capacity as our Practice grows.”


“We have been outsourcing work to Unison Globus for a number of years now. As a growing Practice with severe peaks in workload, we find Unison Globus is the perfect partner to meet our outsourcing needs. Our relationship is a true partnership, with excellent communication between our teams and exceptional turnaround times.”

What Sets Unison Globus Apart

  • Built exclusively for CPA firms. Unison Globus serves CPAs, EAs, CMAs, CIAs, and accounting firms in the US only. Their team understands the compliance standards and quality expectations that distinguish CPA-grade work from general bookkeeping.
  • Scalable capacity for cyclical surges. Their model is designed for the exact kind of workload spike that follows April 15th. They scale up to absorb a large backlog and scale back down once the work is done, with no permanent overhead implications for your firm.
  • Works inside your existing platforms. Unison Globus works across QuickBooks Online, Xero, and the other platforms US CPA firms already use, delivering reconciled, categorized, review-ready financials directly into existing workflows.
  • Rigorous security and data protection. Unison Globus employs vetted professionals and enterprise-grade security protocols. CPAs who have worked with them consistently name data security as a key reason they continue the relationship.
  • White-label delivery. Your clients always see your firm’s name. Unison Globus operates behind the scenes, as a true extension of your team.
  • Proven firm-level results. One firm of 25 professionals that adopted the Unison Globus model transitioned over 60% of routine work to their offshore team. Within one year, advisory billings increased by 20%, employee engagement scores rose by 17 points, and the firm recorded zero voluntary departures during busy season.

How CPAs Manage Bookkeeping Backlog After Tax Season: A Practical Framework

Whether a CPA firm uses outsourced bookkeeping cleanup services in the USA or addresses the backlog in-house, a structured approach makes the difference between a cleanup that actually gets done and one that drags into the following quarter. The following bookkeeping cleanup strategies for CPA firms are used by high-performing US practices to clear backlogs systematically.

  • Triage by urgency first. Not all client backlogs carry the same risk. Prioritize clients with the most time-sensitive needs: upcoming loan applications, board meetings, quarterly reviews, or major financial decisions that depend on accurate current books.
  • Define done before starting. Set a specific target date and specific completion criteria. Without a defined end state, post-tax season bookkeeping cleanup has a way of expanding indefinitely.
  • Separate cleanup from ongoing work. Running catch-up and current-period bookkeeping in the same workflow creates confusion, errors, and delays in both. Treat them as separate workstreams with separate assignments and timelines.
  • Standardize the cleanup checklist. Reconciliations, expense categorizations, adjusting journal entries, and financial statement preparation should follow a documented, repeatable process. This protects quality across clients and makes it straightforward to hand work off to an outsourced partner like Unison Globus.
  • Review the root cause once cleanup is complete. Ask why the backlog formed. Was it insufficient bookkeeping support during tax season? Slow client document delivery? Unclear internal ownership? The answer shapes how CPAs manage bookkeeping backlog after tax season more effectively the following year.

Unison Globus offers daily, monthly, and quarterly financial recordkeeping and reconciliation as part of their ongoing outsourced bookkeeping services for CPA firms. Many firms that engage them for post-season cleanup continue the relationship year-round, removing the backlog problem at its source rather than treating it annually.

The Firms That Treat This Seriously Pull Ahead

The CPA firms that treat post-tax season bookkeeping cleanup as a genuine operational priority consistently pull ahead of those that treat it as an afterthought. The difference shows up in client retention, team stability, advisory capacity, and ultimately in profitability.


The current environment in US public accounting makes this more pressing, not less. The IRS is under operational stress. Regulatory complexity is growing. The talent pipeline is thin. And client expectations for advisory services are rising faster than most firms can build the capacity to meet them.


The cost of ignoring your CPA bookkeeping backlog after tax season rarely appears on a single line of any report. But it accumulates across lost billing opportunities, client churn, staff departures, and advisory revenue that never gets pursued because the firm simply never had the bandwidth.


Firms that partner with specialists in outsourced bookkeeping for CPA firms to handle their accounting cleanup after tax season are not just solving a short-term workflow problem. They are building the operational foundation that makes growth possible.


Thinking about what outsourced post tax season accounting support could look like for your firm?


There is no obligation and no pressure. Unison Globus works exclusively with US CPA firms, and their team is straightforward about what they can and cannot do for your specific situation. Start with a conversation.


Firms that partner with specialists in outsourced bookkeeping for CPA firms to handle their accounting cleanup after tax season are not just solving a short-term workflow problem…

If your backlog is slowing down Q2 work, you’re not alone -
but you also don’t have to carry it into the next season.

Unison Globus can clear months of bookkeeping in weeks through CPA-grade white-label support.

Categories
Accounting Bookkeeping IRS updates Tax

How 2026 IRS Updates and Tax Season Changes Are Driving CPA Firms to Outsource Accounting & Bookkeeping

Every tax season brings change, but 2026 is different in scale and scope. A combination of new IRS deductions, updated standard deduction thresholds, fresh compliance regulations, and tightening data security requirements has made this one of the most complex filing seasons in recent memory. For CPA firms, these changes don’t arrive one at a time; they land simultaneously, across every client file, with the same April deadline.

The 2026 tax season changes introduce new deductions for seniors, tips, overtime pay, and vehicle loan interest, each of which requires additional documentation, verification, and client communication. Standard deductions have increased across all filing statuses. And the IRS has released new regulations, schedules, and guidance that expand the compliance workload for firms of every size.
For many CPA firms, absorbing this complexity with existing staff simply isn’t possible. Capacity constraints, a shrinking talent pipeline, and rising client expectations are converging. The firms navigating this season most effectively share a common thread: they’ve turned to strategic outsourcing of accounting and bookkeeping to create the capacity and expertise they need without the overhead of permanent hiring.
This report examines the specific 2026 IRS changes driving that pressure, the data behind the talent shortage, and the concrete case for why outsourcing has moved from a cost-cutting option to a core operational strategy.

Key 2026 IRS Updates Increasing Workload for CPAs

The IRS has introduced several significant changes for the 2026 tax year that directly impact how CPA firms prepare returns, advise clients, and manage documentation. Taken together, these updates represent a meaningful increase in per-return complexity, and they affect virtually every client file a firm handles. Below are the three areas driving the most additional work.

a. New 2026 Deductions Adding Filing Complexity

Four new or expanded deductions took effect for the 2026 tax year, each requiring specialized tracking, client verification, and additional documentation that wasn’t part of prior-year workflows:


  • Additional $6,000 standard deduction for taxpayers age 65 and older, requiring age verification and coordination with existing senior-specific provisions.
  • Up to $25,000 deduction for qualified tips — a new provision that requires employers and self-employed individuals to document and categorize tip income separately from regular wages.
  • Up to $12,500–$25,000 overtime deduction for qualifying workers, requiring payroll record review and verification of overtime categorization across W-2 and contractor arrangements.
  • Up to $10,000 deduction on passenger vehicle loan interest for US-assembled vehicles, adding a new documentation requirement and eligibility check to personal and business returns alike.


Each of these deductions increases the documentation burden per return. Firms must now collect additional records, verify eligibility, and reconcile new line items — multiplied across every applicable client. For practices managing hundreds of returns, this translates to a significant increase in total preparation hours.

b. Standard Deduction Increases for 2026

The IRS has raised standard deductions across all filing statuses for 2026. While individually each adjustment may seem straightforward, the aggregate impact on a CPA firm’s workflow is substantial. Every client projection, tax planning model, and itemization analysis must be recalibrated:


  • $32,200 for married filing jointly
  • $16,100 for single filers and married filing separately
  • $24,150 for head of household


Beyond the return itself, these changes affect mid-year tax planning conversations, estimated payment calculations, and the itemization threshold analysis firms conduct for clients with significant deductible expenses. Every client portfolio requires a fresh look — not just at filing time, but throughout the year as planning guidance is updated.

c. New IRS Regulations and Schedules for 2026

In addition to deduction changes, the IRS has introduced new regulatory frameworks and administrative updates that expand the compliance workload for CPA firms:


  • Trump Accounts: The IRS has released new guidance governing these newly established savings accounts, requiring CPAs to understand eligibility, contribution rules, and reporting requirements for clients who participate.
  • New IRS schedules for no-tax-on-tips, overtime, and senior deductions: These provisions each require updated schedule filings and documentation standards that did not exist in prior years.
  • Expanded in-person IRS assistance hours: While beneficial for taxpayers, this increases client expectations around real-time guidance and responsiveness from their CPA firms.


Collectively, these regulatory additions mean that staff must stay current with evolving IRS guidance, update client-facing materials, and adapt workflows mid-season — all while managing the existing filing volume. For firms without dedicated compliance resources, this is where the strain becomes most acute.

Rising Fraud Risks and Data Security Pressure in 2026

Regulatory complexity is only one side of the 2026 challenge. The IRS’s release of its annual “Dirty Dozen” tax scams list for 2026 has drawn renewed attention to the fraud and identity theft risks that CPA firms must actively defend against on behalf of their clients. The list highlights increasingly sophisticated schemes, including phishing attacks targeting tax professionals, fraudulent refund requests, and AI-generated identity fraud, that place the burden of vigilance directly on accounting firms.


This raises the stakes significantly for any CPA firm considering an outsourcing partnership. Security is no longer a secondary consideration; it has become a deal-breaker. Firms evaluating offshore accounting support should require demonstrated compliance with the following standards as a baseline:


  • SOC 2 Type II certification: Independently audited controls for security, availability, and confidentiality of client data.
  • Secure Virtual Desktop Infrastructure (VDI): Ensures client data never leaves a controlled environment, even when accessed remotely.
  • Multi-factor authentication (MFA): Required for all system access, eliminating single-point credential vulnerabilities.
  • Strong internal controls: Segregation of duties, access logging, and regular security audits to ensure accountability at every level.

Reputable outsourcing providers invest heavily in these protections precisely because their CPA firm clients require it. When evaluating a partner, security infrastructure should be among the first questions asked, and the answers should be verifiable, not just promised.

Why CPA Firms Are Outsourcing Accounting & Bookkeeping in 2026

The decision to outsource is rarely driven by a single factor. For most CPA firms in 2026, it’s the convergence of several pressures, all hitting at once, all worsening, that makes outsourcing not just attractive but necessary. Here are the four forces most directly driving the shift.

a. The US Accounting Talent Shortage

The accounting workforce in the United States has contracted sharply. Since 2020, the profession has lost more than 300,000 workers, a reduction of approximately 17% of the total accounting workforce. The pipeline hasn’t recovered: CPA exam candidates are down more than 32% since 2016, and 41% of currently practicing accounting professionals report plans to leave the field within five years, largely due to burnout.


The consequences are visible in the market. Over 75% of US accounting firms report difficulty hiring qualified staff, and 74% say they are unable to take on additional clients due to staffing limitations. This isn’t a temporary hiring crunch; it’s a structural imbalance that makes domestic talent acquisition an increasingly unreliable strategy for managing peak-season volume.

b. Seasonal Workload Pressure

Tax season fundamentally changes the workload profile of a CPA firm. Between January and April, filing volumes can increase 200–300% above baseline, a surge that must be absorbed within fixed deadlines and, for most firms, with a largely fixed headcount. The result is predictable: backlogs build, turnaround times lengthen, staff burn out, and client satisfaction suffers.


Outsourcing addresses this directly. Rather than carrying the overhead of year-round staff capable of handling peak volume, firms can engage offshore teams specifically for the high-demand months, scaling capacity to actual workload without permanent cost implications.

c. Automation-Enhanced Outsourcing Teams

Today’s offshore accounting providers are not simply lower-cost replicas of domestic teams. The best providers have integrated automation tools throughout their workflows, creating a model that’s faster and more accurate than traditional manual processing. Key areas where automation is now standard include:


  • Document intake: Automated classification and routing of client-submitted documents, reducing manual sorting time and intake errors.
  • Validation checks: Automated cross-referencing of figures against prior-year data, IRS thresholds, and internal rules before human review begins.
  • Draft return creation: System-generated draft preparation that staff then review and refine, rather than building from scratch.


The combination of automation and experienced offshore staff accelerates turnaround times, reduces bottlenecks, and allows CPA firms to focus their senior professionals on review, advisory, and client communication rather than data processing.

d. Strategic Value Beyond Cost Savings

Outsourcing is no longer primarily a cost-cutting exercise for CPA firms; it has evolved into a strategic capability. Firms that have integrated offshore partnerships report benefits that go well beyond the balance sheet: the ability to take on larger and more complex engagements, real-time workflow support that keeps projects moving across time zones, and access to specialized skills that support advisory and consulting services alongside compliance work.

The global accounting outsourcing market reached $54.79 billion in 2025 and is projected to grow at 8.21% annually through 2030. That growth is being driven by firms that have moved beyond the cost-savings framing and are using offshore partnerships as a genuine competitive lever.

How Outsourcing Helps CPA Firms Handle the 2026 Tax Season

Understanding why firms outsource is one thing; understanding what it actually delivers during a demanding tax season is another. The operational benefits of a well-structured outsourcing partnership show up in four specific ways that directly address the pressures CPA firms face in 2026.

a. Faster Processing and Backlog Management

When offshore teams handle routine bookkeeping, data entry, and initial return preparation, in-house CPAs spend their time on review and advisory rather than ground-level processing. The result is measurably faster throughput. Firms that outsource accounting and bookkeeping services during tax season consistently report 25–30% faster turnaround times, a difference that is visible to clients and directly impacts satisfaction and retention.


Automation built into offshore workflows further accelerates this. Document intake, validation, and draft creation happen faster and with fewer errors than manual processing, compressing the time between receiving client documents and delivering a completed return.

b. Real-Time Reconciliation

One of the most meaningful operational shifts outsourcing enables is the move from monthly close cycles to real-time reconciliation workflows. Rather than batch-processing transactions at month-end, offshore teams can maintain books on a rolling basis, flagging discrepancies immediately, keeping ledgers current, and giving CPA firms and their clients a continuously accurate financial picture.


This shift matters most during tax season, when outdated books create rework and delays. Firms with real-time reconciliation processes enter the filing period with cleaner data and fewer surprises, which directly reduces the time and stress of tax preparation.

c. Compliance-Ready Bookkeeping

Quality offshore accounting support is trained in US GAAP, current IRS regulations, and the specific documentation requirements introduced in 2026. This means firms can delegate a broad range of compliance-adjacent bookkeeping tasks with confidence, including:


  • Year-end cleanup and closing procedures
  • Account reconciliations and trial balance preparation
  • Payroll processing and reconciliation
  • Sales tax calculation and filing support
  • Entity-specific filings for S-corps, partnerships, and trusts

Having these tasks handled by trained specialists rather than stretched in-house staff ensures that the books entering the CPA’s review process are clean, organized, and compliant with current requirements.

d. Scalability During Peak Months

Perhaps the most structurally important benefit of outsourcing is the ability to scale capacity without scaling headcount permanently. CPA firms can add the equivalent of four to six specialists during January through April for less than the annual cost of two permanent US hires and reduce that offshore team size during slower months without layoffs, severance, or the friction of rehiring.


This flexibility converts a fixed-cost staffing problem into a variable-cost solution that tracks actual demand. It also removes a ceiling that limits many firms’ growth: 42% of CPA firms currently cannot take on additional clients due to capacity constraints. Outsourcing removes that ceiling.

Is Your Firm Ready for the 2026 Tax Season Workload?

What CPA Firms Should Look for in an Outsourcing Partner

Not all outsourcing providers are equal, and the wrong partnership creates more problems than it solves. Given the security, compliance, and quality stakes involved in 2026, here are the five criteria that should anchor any evaluation:


  1. ISO / SOC 2 Type II-compliant data security infrastructure, with documentation available on request, not just assurances.
  2. Cloud-based, automation-integrated workflows that enable real-time access, collaboration, and visibility into work in progress.
  3. Tested and documented review processes with defined quality metrics — accuracy rates, turnaround benchmarks, and escalation procedures.
  4. Real-time reporting tools that allow your firm to monitor progress, flag exceptions, and maintain oversight without micromanaging.
  5. Specialized expertise in both bookkeeping and US tax compliance, with demonstrable experience supporting CPA firms, specifically not just general finance outsourcing.

A strong partner will welcome scrutiny on all of these points. References from similarly sized accounting firms, verifiable certifications, and transparent onboarding processes are reliable signals of a provider that takes the partnership seriously.

Why CPA Firms Prefer Outsourcing Accounting & Bookkeeping Services to India

India has established itself as the dominant destination for offshore accounting & bookkeeping services for US CPA firms, and the reasons go beyond cost. The combination of talent depth, technical expertise, language capability, and time zone dynamics creates a set of operational advantages that other destinations have not been able to replicate at scale.

Why IndiaDetail
Talent pool3+ million qualified accounting and finance professionals
LanguageEnglish-speaking workforce with global certifications
US expertiseTrained in US GAAP, IRS regulations, and current tax law
Cost advantage40–70% savings vs. US-based operations
Staff cost comparison$18,000–$28,000/yr (India) vs. $45,000–$60,000/yr (US)
Time zone offset10.5 hours behind the US East Coast — enabling overnight productivity
Turnaround benefitWork completed overnight; ready for US morning review

The time zone advantage is particularly valuable during tax season. Work assigned at the close of a US business day can be completed overnight and ready for senior review the following morning, compressing turnaround cycles by one to two days on typical return preparation timelines. For firms managing large filing volumes against hard deadlines, that compression is a meaningful operational advantage.

India’s accounting workforce also benefits from deep familiarity with US-specific requirements. Many professionals hold CPA-equivalent qualifications, have trained specifically on US GAAP and IRS regulations, and work within firms that have built their entire business model around supporting American CPA practices. This is specialized expertise at scale, not a generic back-office function.

The Numbers: Cost Savings at Scale

The financial case for outsourcing accounting to India for US CPAs is straightforward, but seeing the figures at scale makes the magnitude clearer. The table below compares the annual cost of a five-person accounting team in the US versus an equivalent offshore team, and projects the savings over five years.

 
Cost MetricEstimate
Annual cost: 5-person US team$400,000 – $600,000
Annual cost: 5-person offshore team$120,000 – $240,000
Annual savings$280,000 – $360,000
5-year savings$1.4M – $1.8M
Hourly rate: India$8 – $12 / hour
Hourly rate: US equivalent$20 – $30 / hour
Per-hour savings60 – 66%


These figures represent direct labor cost comparisons for equivalent work. Quality is not compromised: reputable offshore partners employ professionals with CPA-equivalent credentials, maintain SOC 2 Type II security certifications, and operate under the same quality standards firms expect from domestic staff. The savings are structural, a function of labor market differences, not a reflection of lower-quality output.

Conclusion: Why CPA Outsourcing Is Now Essential for 2026 and Beyond

The 2026 IRS updates have made one thing clear: the traditional model of CPA firm operations, fixed headcount, in-house bookkeeping, and domestic-only hiring is not built for the current environment. The forces reshaping the industry are not temporary, and they are not moving in a more favorable direction.


New IRS deductions for seniors, tips, overtime, and vehicle loan interest have increased per-return complexity. Updated standard deduction thresholds require recalibration across every client portfolio. Fresh regulatory frameworks, including Trump Account guidance and new IRS schedules, add compliance layers that demand current expertise. The “Dirty Dozen” fraud alert has raised the security bar for every firm handling client data.


Meanwhile, the domestic talent pipeline is structurally insufficient. Over 300,000 accounting professionals have left the US workforce since 2020. Firms cannot take on new clients due to staffing limitations. There is no hiring solution that resolves this within a single tax season.


Accounting outsourcing for CPA firms to a trusted offshore partner addresses all of these pressures at once. It provides access to qualified professionals at scale. It converts peak-season fixed costs into flexible variable capacity. It delivers faster turnarounds, real-time reconciliation, and compliance-ready bookkeeping without the overhead of permanent hiring.


The global accounting outsourcing market is growing at 8.21% annually because tens of thousands of firms have run this calculation and reached the same conclusion. The firms positioned to thrive in 2026 and beyond are the ones that treat outsourcing not as a fallback, but as a core part of how they operate.


If you’re rethinking how your firm should scale in this environment, partnering with Unison Globus can help you expand capacity, manage complexity, and move forward without adding unnecessary overhead.

Ready to Optimize Your Firm's Operations for 2026?

Categories
Bookkeeping IRS updates

Avoid IRS Penalties: Why Mid-Year Cleanup & Offshore Bookkeeper Matter for CPA Firms

Every year, millions of U.S. taxpayers face IRS estimated tax penalties even when they file on time. For CPA firms navigating Q3 tax planning, advisory work, and extended return filings, one silent risk often drives these penalties: unresolved bookkeeping backlogs from earlier quarters.
When books remain unreconciled or misclassified, the consequences are clear: inaccurate financial reporting, 2025 missed estimated tax payment deadlines, and higher IRS scrutiny. Mid-year bookkeeping cleanup for CPAs is no longer optional. Requirement for services to avoid IRS penalties 2025 is at a record high, and client expectations for proactive guidance increasing, firms need to treat cleanup as a risk management priority that directly impacts compliance, client trust, and October 15 tax extension deadline readiness.
For many firms, this means seeking additional support through catch-up accounting support for tax season, automation technology, or specialized offshore bookkeeping services for CPA firms to clear backlogs quickly and free up in-house professionals for advisory and tax planning work.

IRS Penalties: A Real Risk for Your Clients

For CPA firms, IRS tax penalties are more than numbers on a notice. They represent avoidable client frustrations and unplanned, low-value work that erodes bandwidth for high-impact services like advisory, compliance reviews, and Q3 tax planning for CPA firms.
Penalties are rarely the result of intentional neglect. More often, they come from estimated tax payments made on incomplete or outdated financial records. When Q1 and Q2 reconciliations aren’t finished by midyear, Q3 estimated tax filings become educated guesses instead of data-driven calculations.
And the problem is accelerating. In 2023, the IRS collected nearly $7 billion in underpayment penalties, almost four times the total assessed just a year earlier. Average penalties for taxpayers have jumped from around $150 to nearly $500 per case, reflecting not only higher amounts owed but also the IRS’s increased penalty and interest rates (which climbed to 8% by late 2023, up from 3% in 2021).
This is why mid-year bookkeeping cleanup is a strategic safeguard. By reconciling transactions, correcting misclassifications, and updating records before Q3, firms can accurately calculate estimated tax payments, protect clients from unnecessary penalties, and enter Q4 with audit-ready documentation for IRS compliance.

Quick Reference: Key IRS Details

Estimated Tax Deadlines

  • Q1: April 15
  • Q2: June 15
  • Q3: September 15
  • Q4: January 15 (next year)

Penalty and Interest

  • Underpayment penalty: 0.5% to 5% per month on unpaid amounts
  • Interest: Compounded daily at IRS quarterly rates

Safe Harbor Thresholds

  • Pay 90% of current year tax or 100% of prior year tax
  • For AGI above $150,000: 110% of prior year tax

Why August Is the Right Time to Act

For CPA firms, August is one of the most strategic months in the accounting calendar. It offers a rare chance to get financial records current, address unresolved bookkeeping issues, and prepare client data for accurate tax planning, all before October 15 tax extension deadlines and year-end workloads collide.

What happens if firms wait? Postponing cleanup until the fall compresses workflows. Extended return filings, yearend reviews, and advisory planning all collide, leaving teams stretched thin, increasing the risk of errors, and forcing lastminute fixes that undermine client confidence. Firms that miss this window often spend more time firefighting than planning.

Acting in August helps firms:
  • Complete Form 4868 instructions for individuals and Form 7004 business tax extensions with ample review time before October deadlines
  • Prepare accurate Q3 estimated tax submissions, reducing IRS penalty exposure
  • Reconcile first half transactions, ensuring reliable financial data for planning
  • Fix categorization errors that distort reporting and delay decision-making
  • Produce clear, actionable reports that enable meaningful advisory discussions
Acting in August is about creating space for strategy instead of crisis management. Firms that tackle backlogs now gain control over their timelines, protect clients from preventable penalties, and position their teams to focus on advisory and planning when it matters most.

For many firms, this is also the ideal moment to expand capacity. Whether through process automation or specialized offshore accounting teams, leveraging August to resolve months of unresolved work can transform Q4 from a scramble into a well-planned, profitable, close to the year.

Don’t wait for Q4 to fix Q1 and Q2.

Partner with Unison Globus now for mid-year bookkeeping cleanup, Form 4868 and 7004 preparation, and secure offshore accounting support that keeps your client’s penalty-free. Get in touch now

August Advantage: Act Now vs Wait

Act in August Wait Until Fall
Extended returns filed ahead of October deadlines Deadlines stack up creating chaos
Accurate Q3 estimated tax filings Higher risk of penalties and compliance errors
Backlogs resolved for clean books Teams overextended and burned out
Advisory-ready reports for better client conversations Lost opportunities for planning and growth
August is your capacity window. Act now to protect clients, reduce risks, and enter Q4 prepared.

Why Backlogs Happen and Why They Are Hard to Clear

Even when CPA firms know what needs to be done in August, from midyear bookkeeping cleanup to preparing estimated tax filings and finalizing extended returns, actually clearing these backlogs is rarely straightforward.

The Hidden Roadblocks

  • Unreconciled accounts from earlier quarters delay accurate financial reporting.
  • Incomplete or missing documentation creates gaps that take hours to fill.
  • Delayed client responses lead to unpredictable timelines and stalled workflows.
  • Inconsistent categorization skews financial reports and complicates cleanup.
  • Data scattered across multiple platforms increases the time spent on manual work.

Why This Puts Firms at Risk

Midyear bookkeeping backlogs do more than slow down day today operations. Incomplete reconciliations and delayed financial updates create gaps that increase audit exposure, leaving firms vulnerable if the IRS or state agencies request supporting documentation.

They also push out delivery timelines, making it harder to meet client expectations for timely financial statements, tax estimates, and planning insights. In a profession where trust is tied directly to reliability, these delays can erode client confidence and strain relationships.

Perhaps most critically, these backlogs drain a firm’s most valuable resource: its people. Partners, managers, and senior accountants often end up handling catchup bookkeeping and transaction cleanup. This forces senior staff into firefighting mode, leaving little time for innovation, business development, or deep client engagement. Over time, this reactive approach weakens the firm’s competitive edge and diminishes its ability to deliver differentiated, high value services.

In short, when bookkeeping cleanup lags, firm capacity shrinks, risks rise, and growth stalls, precisely when clients need their advisors to lead with clarity and foresight.

The Measurable Impact

  • 65% of small businesses fall behind on bookkeeping in the first half of the year.
  • The IRS assessed over $1 billion in underpayment penalties in 2024, much of it linked to inaccurate or delayed filings.
  • Audit risk increases by up to 40 percent when documentation is incomplete or inconsistent.
  • CPA firms lose 10 to 15 hours per client manually reconciling backlogged data.
In short: Without the right process and additional support, even proactive firms end up stuck in reactive mode at the exact time clients need them to lead with planning and insight.

Turn Backlogs into Opportunity - Act Now with Unison Globus

Midyear cleanup is not just about reconciling accounts. It is a strategic opportunity to protect clients, reduce risk, and create the capacity your firm needs to deliver higher value work.

For firms already stretched thin, tackling multi-month backlogs internally often means sacrificing advisory projects or pushing teams toward burnout. Partnering with experienced offshore bookkeeping services for CPA firms can change that.

With more than 19 years of experience and a 500-plus member team, Unison Globus helps CPA firms resolve 3–12 months of backlog in as little as 2–4 weeks while ensuring IRS-compliant, paperless workflow for tax season and seamless collaboration across platforms like QuickBooks, Xero, Sage, and NetSuite.

The results speak for themselves:
  • Lower overhead by avoiding the cost and time of hiring and training in-house
  • Scalable capacity to flex resources based on seasonal demand
  • Improved compliance with reduced penalties and audit exposure
  • Enhanced client service through timely, accurate reporting and insights
August is your window. Use this time to clear backlogs, stabilize operations, and enter Q4 with the confidence and capacity to focus on growth.