

 [gtranslate]
For Australian accounting firms managing sizeable SMSF books, peak workloads can put significant pressure on preparation teams. Reconciliations, financial statements, supporting schedules and documentation must progress alongside other accounting and compliance work.
As preparation queues build, experienced accountants can become increasingly involved in routine preparation instead of focusing on review, exceptions and matters requiring professional judgement. Adding permanent headcount is not always practical when demand fluctuates throughout the year.
This is where Outsourced SMSF Preparation Australia can offer a practical capacity option. Defined preparation activities can be supported by an external team while the firm retains responsibility for review, professional judgement and client relationships. The right model should fit the firm’s existing processes, technology, quality controls and responsibility boundaries.
TL;DR
- Peak SMSF workloads can create a capacity bottleneck, particularly when preparation volumes compete with other compliance work for the same resources.
- Adding overtime, hiring or reallocating staff may increase preparation capacity without increasing senior review capacity, creating downstream bottlenecks.
- Outsourcing defined SMSF preparation activities can add controlled capacity while partners and senior accountants retain technical review, professional judgement and client responsibility.
- A successful outsourced model depends on clear workflows, documented procedures, exception management, secure data handling and defined responsibility boundaries.
- Preparation, internal review and independent SMSF audit must remain clearly separated, with the accounting firm retaining appropriate professional responsibilities.
- The best time to evaluate outsourcing is before peak workload builds, allowing firms to assess providers, test workflows and establish controls before pressure intensifies.
The Instinct to “Just Push Through Peak Season” and Why It Underperforms
Most firms initially absorb SMSF workload internally through overtime, staff reallocation or recruitment. These responses can provide short-term relief, but they do not necessarily resolve the underlying workflow constraint.
Adding preparation hours can increase the number of completed files entering review. However, it does not automatically increase the number of partners, managers or senior accountants available to review those files.
Recruitment has a similar limitation during a concentrated workload period. New staff need time to understand the firm’s SMSF procedures, software environment, workpaper standards and review expectations before contributing independently.
Staff reallocation can create another bottleneck. Moving experienced accountants into SMSF preparation may push other compliance, advisory or client responsibilities further down the workflow.
There is also a quality implication. When preparation is completed under sustained pressure, incomplete information, unresolved exceptions or inconsistent workpapers can generate additional review queries. Those queries return to the same senior professionals already facing constrained availability.
| Internal response | Immediate benefit | What remains unresolved |
|---|---|---|
| Overtime | Increases short-term preparation capacity | Senior review and approval capacity does not increase |
| Reactive hiring | Adds potential preparation capacity | New staff require onboarding, supervision and process familiarisation |
| Staff reallocation | Directs existing resources toward urgent SMSF files | Capacity is reduced elsewhere in the practice |
| Batching or deferring files | Allows the team to focus on selected files first | Work accumulates and creates a larger downstream queue |
| Increasing review effort | Provides additional scrutiny to compressed files | Senior staff spend more time correcting preparation issues |
Expert Insight:
The important distinction is between preparation capacity and reviewer capacity. A firm can increase production effort while leaving senior review capacity unchanged.
That distinction is critical during peak workloads. Internal responses may increase preparation activity, but they do not necessarily resolve the constraint created by limited senior review capacity. The objective is therefore to create enough review-ready preparation capacity without adding unnecessary work back into the senior review queue.
Is your SMSF preparation bottleneck a staffing problem or a capacity-design problem?
The Stakes: What a Compressed SMSF Season Means for Practice Capacity
The SMSF sector is substantial, which makes preparation and review capacity a legitimate practice-management consideration for firms with sizeable SMSF books.
The ATO publishes quarterly and annual SMSF statistics.. Its March 2025 quarterly report recorded 646,168 SMSFs, 1,197,293 members and approximately $1.01 trillion in estimated assets.
While national SMSF growth does not translate directly into increased workload for every accounting firm, it highlights the scale of the sector and the volume of annual reporting, preparation and audit activity involved.
The question is therefore not how large the national SMSF market is. It is how much preparation and review work reaches a firm’s finite internal team at the same time.
For an accounting practice, the more relevant issue is concentration. A substantial SMSF client base can bring significant reconciliation, financial statement, annual return and review work into periods when other compliance engagements are also progressing.
This is where SMSF compliance obligations intersect with workflow design. The compliance obligations remain with the relevant professionals, but firms can assess whether every production task needs to remain with the same internal resources.
Effective ATO SMSF Compliance also depends on accurate preparation, complete documentation and appropriate professional review throughout the workflow.
Where the SMSF Preparation Bottleneck Actually Shows Up
SMSF preparation capacity is typically consumed across a series of connected production activities. The pressure becomes more visible when routine processing, reconciliations, documentation and exception handling accumulate before senior review.
The preparation points that commonly create pressure
- Transaction processing: Bank, investment and other transaction data must be captured and classified consistently before reconciliations and financial statements can progress. Incomplete or incorrectly coded transactions can create downstream rework.
- Bank and investment reconciliations: Multiple accounts, investment transactions, securities and property holdings can increase reconciliation effort, particularly where supporting evidence or transaction classifications require follow-up.
- Asset registers and supporting schedules: Investment and asset information often needs to be reflected consistently across the relevant registers, financial statements and supporting schedules. Gaps between source records and working papers can create additional review queries.
- Financial statement preparation: Preparing the first-pass financial statements and associated workpapers can consume substantial production capacity before a senior professional reviews the file. This is often where SMSF Financial Statement Preparation becomes a significant workflow component.
- Contribution and pension checks: Contribution and pension data should be reconciled to member records and supporting evidence, with exceptions identified before the file reaches senior review.
- Document follow-up: Missing bank statements, investment documentation, contribution evidence or other supporting records can prevent a file from progressing. Repeated follow-up can also draw internal accountants away from preparation and review activities.
- Exception identification and escalation: Unusual, incomplete or uncertain items should be identified during preparation, assigned to an appropriate owner and escalated when technical judgement is required. The objective is to resolve and document exceptions before they reach the senior review queue, rather than leave the reviewer to reconstruct the issue.
- Auditor query turnaround: Preparation gaps or unresolved exceptions can generate additional exchanges with the independent SMSF auditor. Each query can return work to the accounting team and consume further preparation or review capacity.
- Senior review queues: Even well-prepared files can remain incomplete when partner or manager review capacity is constrained. At this stage, senior review becomes the rate-limiting point in the workflow.
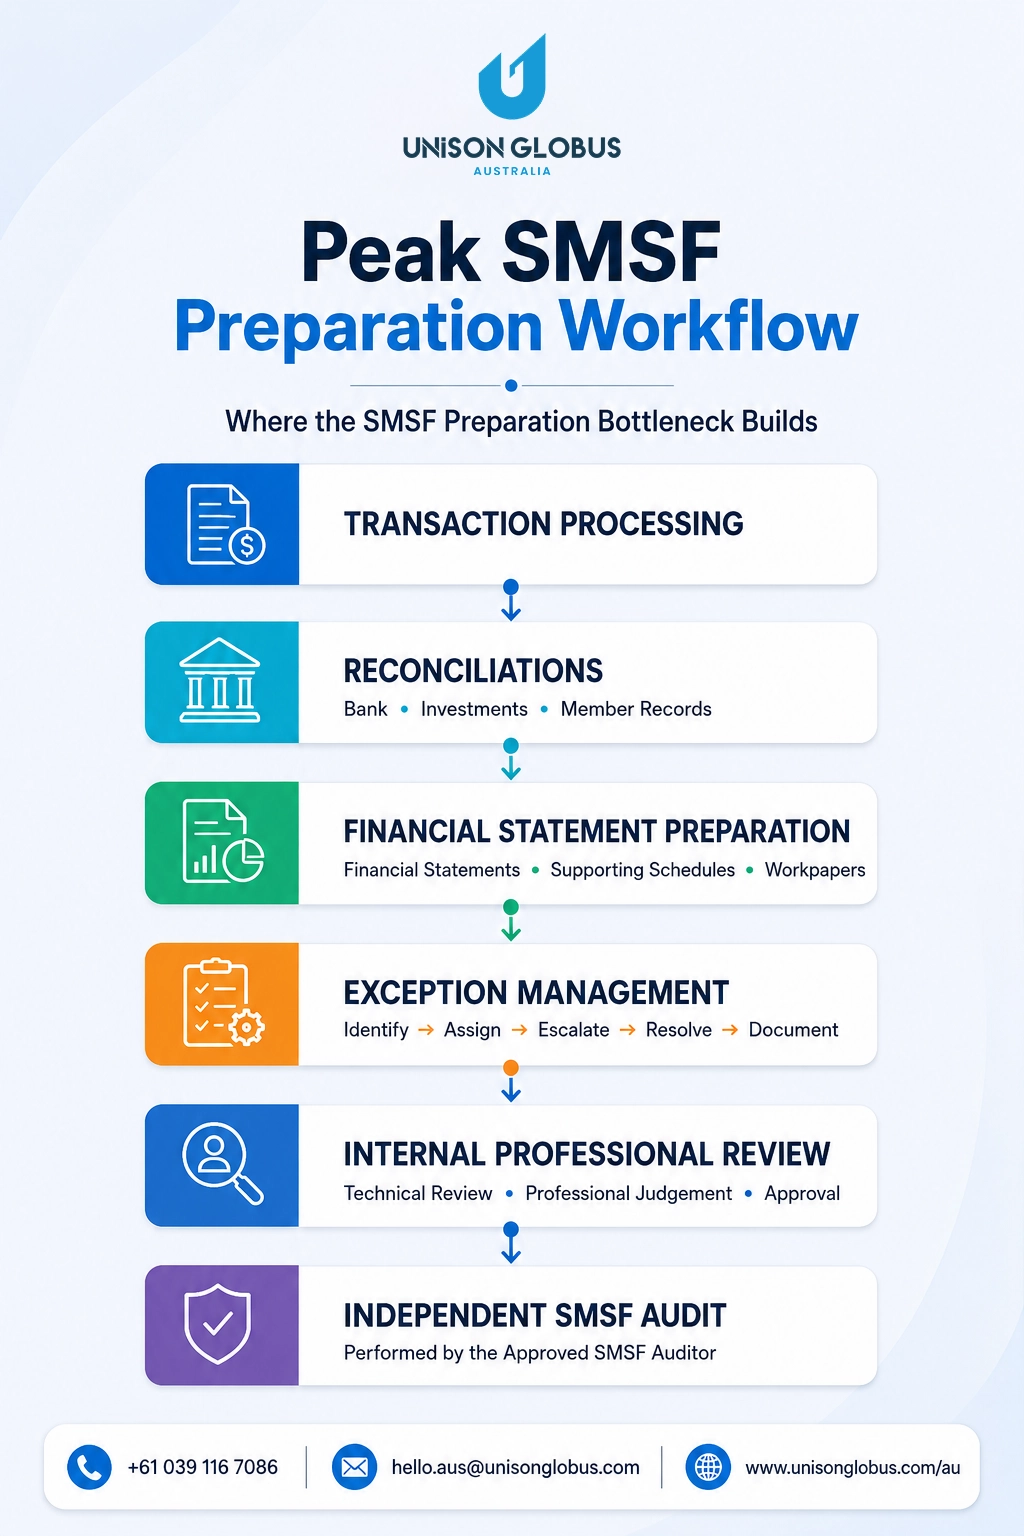
These activities form a connected workflow that moves the file from initial processing through preparation, exception resolution, professional review and independent audit:
Transaction processing → Reconciliation → Financial statement preparation → Supporting schedules and documentation → Exception identification → Exception resolution → Internal professional review → Independent SMSF audit
A dedicated SMSF preparation team Australia model can potentially address the production side of these constraints by absorbing defined preparation activities. It does not remove internal review, professional judgement, client ownership or the accounting firm’s applicable professional responsibilities.
The Talent Supply Problem Behind the Seasonal Squeeze
Recruitment can strengthen permanent capability, but it is not always an efficient response to workload that rises and falls around recurring SMSF preparation periods. Many firms also explore outsourced accounting and bookkeeping support to add flexible capacity without increasing permanent headcount.
Australian accounting firms operate within a broader professional labour market where experienced accounting and tax capability can take time to recruit and develop. That does not establish a universal SMSF-specific talent shortage, but it does make permanent recruitment only one part of capacity planning.
Recruitment and seasonal capacity solve different problems
Permanent recruitment makes sense when workload supports sustained additional headcount. External preparation support can be considered when the requirement is more closely connected to recurring volume fluctuations.
This is where SMSF preparation outsourcing Australia, including SMSF administration, accounting, and year-end finalisation support, becomes an operational consideration.
For firms considering whether to hire offshore SMSF specialists, the important question is not simply whether specialists are available. It is whether the arrangement can operate within Australian requirements, firm-specific procedures, appropriate supervision and secure information-handling controls.
How Outsourced SMSF Preparation Addresses Each Bottleneck
A structured model begins by separating defined preparation activities from responsibilities that require internal professional judgement. The external workflow should align with the firm’s procedures, documentation standards, review checkpoints and escalation requirements.
This approach allows outsourced SMSF preparation services for accounting firms to function as an extension of defined preparation capacity rather than a replacement for internal professional oversight.
Match the external workflow to the internal bottleneck
- Reconciliation capacity: External preparation support can absorb defined reconciliation and processing activities during higher-volume periods, allowing internal staff to focus on exceptions and review.
- First-pass financial statements: Financial statements and supporting workpapers can be prepared against firm-specific templates, procedures and documentation expectations within the agreed scope.
- Structured compliance checks: Standardised checklists and documented review points can help identify missing information or exceptions before senior review. They do not replace professional judgement.
- Audit-ready handoff: A complete supporting file can create a more orderly handoff to the independent SMSF auditor.
- Review rather than re-preparation: Senior professionals can focus on reviewing prepared work, investigating exceptions and applying judgement rather than repeatedly rebuilding incomplete files.
The workflow can therefore move from:
- Internal-only: Intake → Reconciliation → Preparation → Exception management → Rework → Internal review → Audit handoff
- Supported model: Intake → Reconciliation → Defined external preparation → Exception identification and resolution → Internal review → Audit handoff
The supported model changes where defined preparation activities are performed while keeping technical judgement, approval and audit responsibilities within the appropriate roles.
A review-ready file should contain completed reconciliations, supporting evidence, prepared financial statements, documented exceptions and clear escalation notes, allowing the senior reviewer to focus on validation rather than reconstruction.
Separating SMSF Preparation, Review and Audit Responsibilities
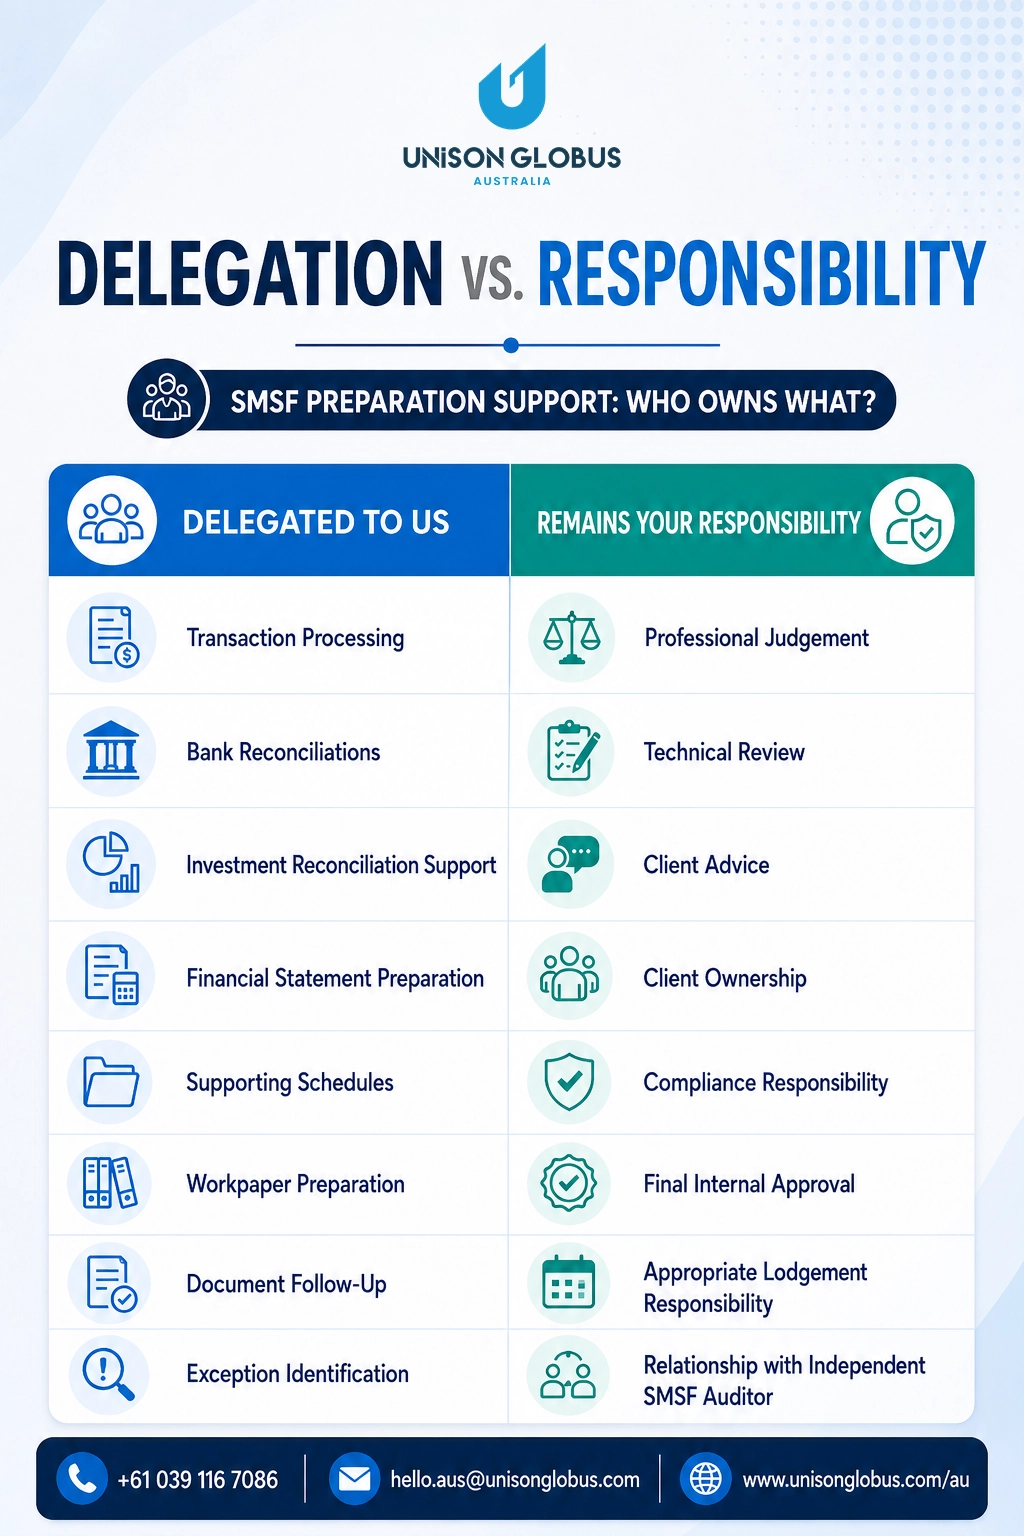
The distinction between preparation, professional review and independent audit should remain clear throughout the workflow. Defined production activities can be supported externally, while the accounting firm retains appropriate review and professional responsibilities and the independent auditor remains separate.
| Stage | External preparation support | Australian accounting firm | Independent SMSF auditor |
|---|---|---|---|
| Transaction processing | Performs defined processing activities | Provides procedures, oversight and review | — |
| Reconciliation | Supports bank, investment and other defined reconciliations | Reviews results and resolves matters requiring professional judgement | — |
| Financial statements | Prepares first-pass financial statements and supporting workpapers | Performs technical review and appropriate approval | Considers financial information as part of the independent audit |
| Exceptions | Identifies, documents and escalates exceptions | Determines treatment and resolves matters requiring professional judgement | Considers relevant matters independently during the audit |
| Compliance judgement | Escalates matters requiring technical assessment | Determines appropriate treatment within its professional responsibilities | Independently assesses matters relevant to the audit |
| Independent audit | Does not perform the independent audit | Provides required information and responds to auditor queries | Performs the independent SMSF audit |
This structure keeps defined preparation activities within the external production workflow while the accounting firm retains professional judgement, review and client responsibility. The independent SMSF auditor remains separate from the preparation process.
That is the practical role of an SMSF outsourcing partner: supporting defined preparation activities within the firm’s established review structure.
For firms assessing SMSF outsourcing solutions for accountants, the critical question is whether preparation responsibilities can be clearly separated from professional decisions and review responsibilities.
Technology integration matters
Technology compatibility should support the firm’s existing workflow, not create another process to manage. Before implementation, firms should confirm system access, document exchange, reconciliation workflows, task tracking and review handoffs. Automated feeds can reduce manual data entry, but reconciliation, exception investigation and professional review remain essential.
What Firms Should Consider Before Outsourcing SMSF Preparation
Outsourcing SMSF preparation raises legitimate questions about independence, professional responsibility, confidentiality, offshore processing, and cost. Assess these before implementation, not after the arrangement is operational.
Independent audit requirements
Under section 35C of the Superannuation Industry (Supervision) Act 1993, each SMSF trustee must ensure that an approved SMSF auditor is appointed for each year of income.
Preparation and audit should therefore remain clearly separated, with defined responsibility boundaries between outsourced preparation, the accounting firm’s internal review and the independent SMSF audit. Preparation support does not make the external provider the independent auditor or transfer the auditor’s separate responsibilities. Approved SMSF auditors must meet ASIC registration requirements and comply with applicable ongoing obligations.
Firms should maintain clear boundaries between preparation, internal review and SMSF audit coordination support activities to preserve independence and ensure compliance responsibilities remain appropriately allocated.
Professional responsibility and supervision
Similar to an STP compliance health check, regular reviews of SMSF workflows and reporting processes can help firms identify operational and compliance risks before peak periods.
The TPB’s current outsourcing and offshoring guidance states that registered tax practitioners must ensure tax agent services provided on their behalf are provided competently. Where an unregistered third party performs such services, appropriate supervision and control may be required depending on the nature of the arrangement.
The precise supervision and control requirements depend on the arrangement and whether the external party is a registered tax practitioner or another third party. The accounting firm’s professional responsibilities therefore do not simply move to the external provider. Responsibility boundaries, review procedures and applicable supervision should be established before work begins.
Firms using offshore SMSF preparation support for CPA firms should establish these controls before client work is transferred, with clear expectations for supervision, review and escalation.
Data security and confidentiality
Firms should assess how client information will be accessed, transferred, stored and protected before engaging an external provider.
The TPB specifically identifies controls such as confidentiality arrangements, secure connections, access controls, audit trails, segregation of duties and approval processes as considerations for outsourcing and offshoring arrangements.
Client disclosure and offshore processing
Where client information is disclosed to an offshore third party, firms need to consider applicable professional and privacy obligations.
Under Code item 6, a tax practitioner must generally obtain client permission before disclosing information relating to the client’s affairs to a third party, unless a legal duty to disclose applies, as outlined in the TPB’s confidentiality guidance.
Where the Privacy Act applies, APP 8 also establishes requirements for cross-border disclosure of personal information and can leave an Australian entity accountable for certain acts or practices of an overseas recipient.
Cost structure
Outsourced preparation and permanent recruitment have different cost structures. External capacity can be aligned more closely with workload volume, while permanent headcount carries ongoing employment and development costs.
That does not make outsourcing automatically cheaper. Firms should assess workload, utilisation, recruitment costs, management requirements and provider fees against their own operating model.
Before moving from consideration to implementation, firms should also assess whether a prospective provider can operate effectively within their existing SMSF workflow and control environment.
When Outsourcing SMSF Preparation Makes Operational Sense
Outsourcing makes the strongest operational case when a firm has a recurring preparation bottleneck that can be separated from professional judgement.
For Australian firms considering whether to outsource SMSF work, the decision should begin with workload patterns, workflow maturity, review capacity and the ability to define responsibilities clearly.
Conditions that support the model
- Recurring peak volume: Workload increases follow a recognisable pattern rather than representing a one-off event.
- Senior production involvement: Partners or senior accountants spend substantial time preparing files instead of reviewing completed work.
- Limited recruitment flexibility: Permanent recruitment does not align with short-term workload fluctuations.
- Documented procedures: SMSF processes, workpaper standards and escalation points are sufficiently clear for another team to follow.
- Defined responsibilities: Preparation, review, client communication and audit responsibilities have clear ownership.
- Controlled technology: Secure file access, document exchange and task tracking can support the required handoffs.
Conditions that suggest fixing the workflow first
- Unclear ownership: Staff do not have consistent responsibility for preparation and review stages.
- Inconsistent files: Similar SMSF engagements are prepared using materially different structures or procedures.
- Undocumented processes: The firm cannot clearly explain how a standard file should move from intake to review.
- Existing quality problems: Preparation errors have not been diagnosed or addressed at their source.
Outsourcing does not compensate for a fundamentally inconsistent workflow. If the process cannot be explained internally, it will be difficult to transfer effectively to an external team.
What Happens When Firms Wait Until the Next Peak
Recurring workload patterns can be planned for before preparation queues have formed. Waiting until a bottleneck is already developing leaves little time to assess providers, map workflows, establish controls or test file handoffs.
The key is to avoid implementing a new operating model in the middle of the bottleneck.
Before the peak
The firm can document preparation responsibilities, establish review checkpoints, assess providers, confirm information-handling arrangements and test sample file handoffs. A defined workload can then be piloted to measure exceptions, rework, turnaround between handoffs and reviewer effort before broader implementation.
During the peak
Once the process is established, the external team can work within the agreed workflow while internal professionals focus on review, exceptions, client communication and matters requiring professional judgement.
The value of preparing early is not simply speed. It gives the firm an opportunity to test and refine the operating model before peak workload pressure makes changes more difficult.
What Australian Accounting Firms Should Evaluate in an SMSF Preparation Provider
Before engaging a provider, firms should assess the following operational, technical and control criteria to determine whether the model fits their existing SMSF workflow:
| Evaluation area | What to verify |
|---|---|
| SMSF capability | Experience with Australian SMSF preparation, reconciliations, financial statements and supporting workpapers. |
| Workflow fit | Ability to work within the firm’s procedures, templates, file structures and review checkpoints. |
| Exception management | Defined processes for identifying, assigning, escalating, resolving and documenting exceptions, with clear ownership at each stage. |
| Quality controls | Documented QA procedures, review controls, correction workflows and escalation protocols before work reaches the firm’s senior reviewer. |
| Software compatibility | Compatibility with the firm’s existing SMSF, accounting, document-management and workflow platforms. |
| Data security | Access controls, secure data transfer, storage arrangements, confidentiality controls and incident procedures. |
| Scalability | Ability to absorb defined workload increases while maintaining agreed procedures and responsibility boundaries. |
| Audit handoff | Consistent workpapers, supporting documentation and clear escalation notes for handoff to the independent SMSF auditor. |
| Communication | Defined communication channels, response expectations, status reporting and escalation contacts. |
Provider evaluation should focus on how the external team fits within the firm’s existing workflow and control environment. Firms should verify who performs each preparation activity, how exceptions are managed and escalated, what documentation standards apply, and how completed work moves into internal review and audit handoff. Representative workpapers, supporting schedules and exception notes can help assess whether the provider’s output meets the firm’s expectations.
Before broader implementation, firms can test the model using a defined group of files and measure preparation quality, exceptions, rework, turnaround between handoffs and reviewer effort. A structured pilot provides practical evidence of whether the provider can operate consistently within the firm’s procedures and whether the arrangement improves preparation capacity without weakening review controls or responsibility boundaries.
What a Supported SMSF Peak Season Looks Like
SMSF files are entering preparation while other compliance engagements are still progressing through the practice.
In a supported model, defined preparation activities can move through an external team before reaching senior reviewers. Reconciliations are completed against documented procedures, first-pass financial statements and supporting workpapers are prepared, and exceptions are identified for escalation.
The file then moves into the firm’s internal review process.
The partner or senior accountant remains involved. Their role becomes more focused on reviewing prepared work, resolving exceptions, applying professional judgement and managing client and audit interactions.
For firms that need additional support around this stage, SMSF review services for accounting firms can complement preparation capacity while keeping appropriate professional oversight within the practice.
The result is not a pressure-free peak season. It is a different allocation of professional capacity. This approach creates additional controlled preparation capacity while keeping technical judgement, internal review and professional responsibility within the firm’s established workflow.
How Unison Globus Australia Supports a Structured SMSF Preparation Model
For accounting firms considering outsourced SMSF preparation, Unison Globus Australia supports defined preparation activities within the firm’s existing workflow. The focus is on adding controlled preparation capacity while working within established procedures, documentation standards and review checkpoints. This approach can also complement broader SMSF Audit & Compliance Solutions for Australian Businesses where preparation, review and audit-related workflows need clearly defined boundaries.
What the preparation model can support:
- SMSF preparation: Defined preparation activities, including reconciliations, financial statements, supporting schedules and workpapers, based on the firm’s procedures and agreed scope.
- Processing support: SMSF Processing Support for Bookkeeping Firms can assist with transaction processing, reconciliations and related preparation activities where inputs, outputs and responsibilities are clearly defined.
- Exception and workflow support: Preparation teams can identify missing information, document exceptions and escalate matters requiring professional assessment before files move into internal review.
The accounting firm remains responsible for appropriate professional review, judgement, client relationships and applicable compliance responsibilities. External preparation support operates within that structure, giving senior professionals a more organised body of work to review rather than transferring those responsibilities to the provider.
For firms evaluating SMSF Preparation Services for CPA Firms, the decision should ultimately be based on preparation volume, workflow fit, documented procedures, review capacity and appropriate controls.
Need more SMSF preparation capacity without expanding your internal team?
Peak SMSF Workloads Require More Than Additional Hands
Peak SMSF preparation pressure is fundamentally a capacity and workflow-design issue, not simply a staffing shortfall.
When senior review capacity is constrained, defined preparation support can help create additional controlled capacity while allowing professionals to focus on judgement, exceptions and review.
The objective is not to transfer responsibility. It is to structure preparation work so the right tasks are handled by the right resources, with appropriate oversight and clear accountability.
Unison Globus Australia can support accounting firms evaluating a structured B2B SMSF preparation model. If your firm is facing recurring SMSF preparation capacity pressures, contact Unison Globus Australia to discuss a suitable support model.
Frequently Asked Questions
Outsourced SMSF Preparation Australia can support defined production tasks such as reconciliations and financial statement preparation while internal professionals retain review responsibility.
Preparation may occur before independent audit, but the approved SMSF auditor must remain independent and perform the audit under applicable statutory and professional requirements.
No. The TPB requires tax practitioners to ensure outsourced tax agent services are provided competently, with appropriate supervision and control where applicable.
Review confidentiality, access controls, security, data storage, client permission and applicable privacy obligations. Offshore disclosures can also trigger APP 8 requirements where the Privacy Act applies.
They can, where the provider’s systems and access arrangements support the firm’s workflow. Software compatibility should be confirmed before implementation rather than assumed.
Ideally, before preparation queues form. This gives the firm time to document procedures, assess providers, establish controls and test workflow handoffs.