

 [gtranslate]
Summarize and analyze this article with:
- TL;DR
- The Nonprofit Audit Calendar Doesn’t Leave Room for Slack
- Where Peak-Period Audit Bottlenecks Actually Form
- Why Adding More Hands Doesn’t Always Solve the Problem
- Need additional support during peak nonprofit audits? See how we support CPA firms with workpapers, documentation, schedules, and defined testing.
- Where Outsourced Audit Support Fits in the Engagement Workflow
- Nonprofit Audit Work Requires Engagement-Specific Support
- What Firms Should Validate Before Using External Audit Support
- How to Compare Capacity Options During Peak Audit Periods
- When Outsourced Audit Support Is Worth Evaluating
- Where This Leaves the Peak-Season File
- Audit Workload Challenges Extend Beyond One Market
- Facing nonprofit audit bottlenecks during peak periods? See how our defined offshore audit support can keep preparation moving while your team stays focused on review.
- Frequently Asked Questions
- Which nonprofit audit tasks can realistically be supported by an outsourced team?
- What stays the CPA firm’s responsibility when using outsourced audit support?
- How does outsourced audit support fit into an existing engagement workflow?
- How do firms maintain quality and review controls over externally prepared work?
- What should a CPA firm evaluate before choosing an audit support provider?
- When does outsourced audit support make more sense than seasonal hiring?
By the third week of October, several nonprofit engagements can be moving through preparation, testing, and review at the same time. One client may be closing its annual financial statements while another is completing a Single Audit tied to federal awards, and a third may still have outstanding schedules or supporting documentation. For firms managing several engagements at once, outsourced audit support can provide additional execution capacity for defined work without changing where professional judgment and engagement responsibility sit.
The pressure often shows up in the review queue. Managers and partners may find themselves preparing lead schedules, organizing evidence, or following up on routine documentation while also reviewing work prepared by others. Overtime, internal redistribution, and seasonal hiring can help in specific situations, but they do not always address the underlying issue: experienced audit professionals are spending review time on preparation work.
For CPA firms, the practical question during these peak nonprofit periods is how to allocate defined execution work without disrupting the review and decision-making structure of the engagement.
TL;DR
- Core message: Peak nonprofit audit periods create pressure when preparation, testing, documentation, client follow-up, and review converge across multiple engagements.
- Where outsourced support fits: CPA firms can assign defined, reviewable work such as workpaper preparation, roll-forwards, schedules, PBC tracking, testing documentation, and exception identification, while retaining professional judgment and final engagement responsibility.
- Why nonprofit expertise matters: Contributions, donor restrictions, net assets, functional expenses, grants, and Single Audit requirements create engagement-specific considerations that external support providers need to understand.
- What firms should evaluate: Scope clarity, review controls, nonprofit and Single Audit experience, security, technology integration, communication, escalation procedures, and workflow compatibility.
- Bottom line: Outsourced audit support can help firms manage variable peak workloads when the work is clearly defined and integrated into the existing review structure, without shifting engagement-level responsibility away from the CPA firm.
What Is a Nonprofit Audit?
A nonprofit audit is an independent examination of an organization’s financial statements and supporting records, covering areas such as contributions, donor restrictions, net assets, functional expenses, grants, and internal controls. Organizations subject to federal award requirements may also undergo a Single Audit, which adds federal program and compliance procedures. For federal awards issued beginning October 1, 2024, the expenditure threshold used in determining Single Audit applicability increased to $1 million, subject to the applicable federal award framework and requirements.
(Source:
Federal Register: Guidance for Federal Financial Assistance
)
The Nonprofit Audit Calendar Doesn’t Leave Room for Slack
Nonprofit audit workloads tend to arrive in overlapping waves rather than in a perfectly distributed sequence. Calendar-year organizations move toward year-end close and subsequent audit work while other clients may be preparing for board meetings, grant reporting, or other deadlines. June 30 fiscal-year organizations create another recurring workload pattern, so firms with a broad nonprofit portfolio can have several engagements moving through different stages at the same time.
That overlap becomes more significant when a firm is also handling Single Audits. These engagements add federal program and compliance procedures alongside the financial statement audit, including additional testing, documentation, and work associated with the Schedule of Expenditures of Federal Awards. The engagement team may therefore be coordinating multiple streams of work within the same reporting window.
Note: Single Audit threshold
For federal awards issued beginning October 1, 2024, the expenditure threshold used in determining Single Audit applicability increased to $1 million. Firms should apply the requirements based on the applicable federal award framework and fiscal period rather than treating the threshold as a blanket rule for every nonprofit engagement.
The practical challenge is therefore one of workflow timing. A firm may have the technical knowledge to perform the engagement while still finding that preparation, evidence collection, documentation, and review are converging too closely together
.
That distinction becomes particularly important during nonprofit audit preparation, when preparatory work starts consuming the same experienced hours needed later for review and resolution.
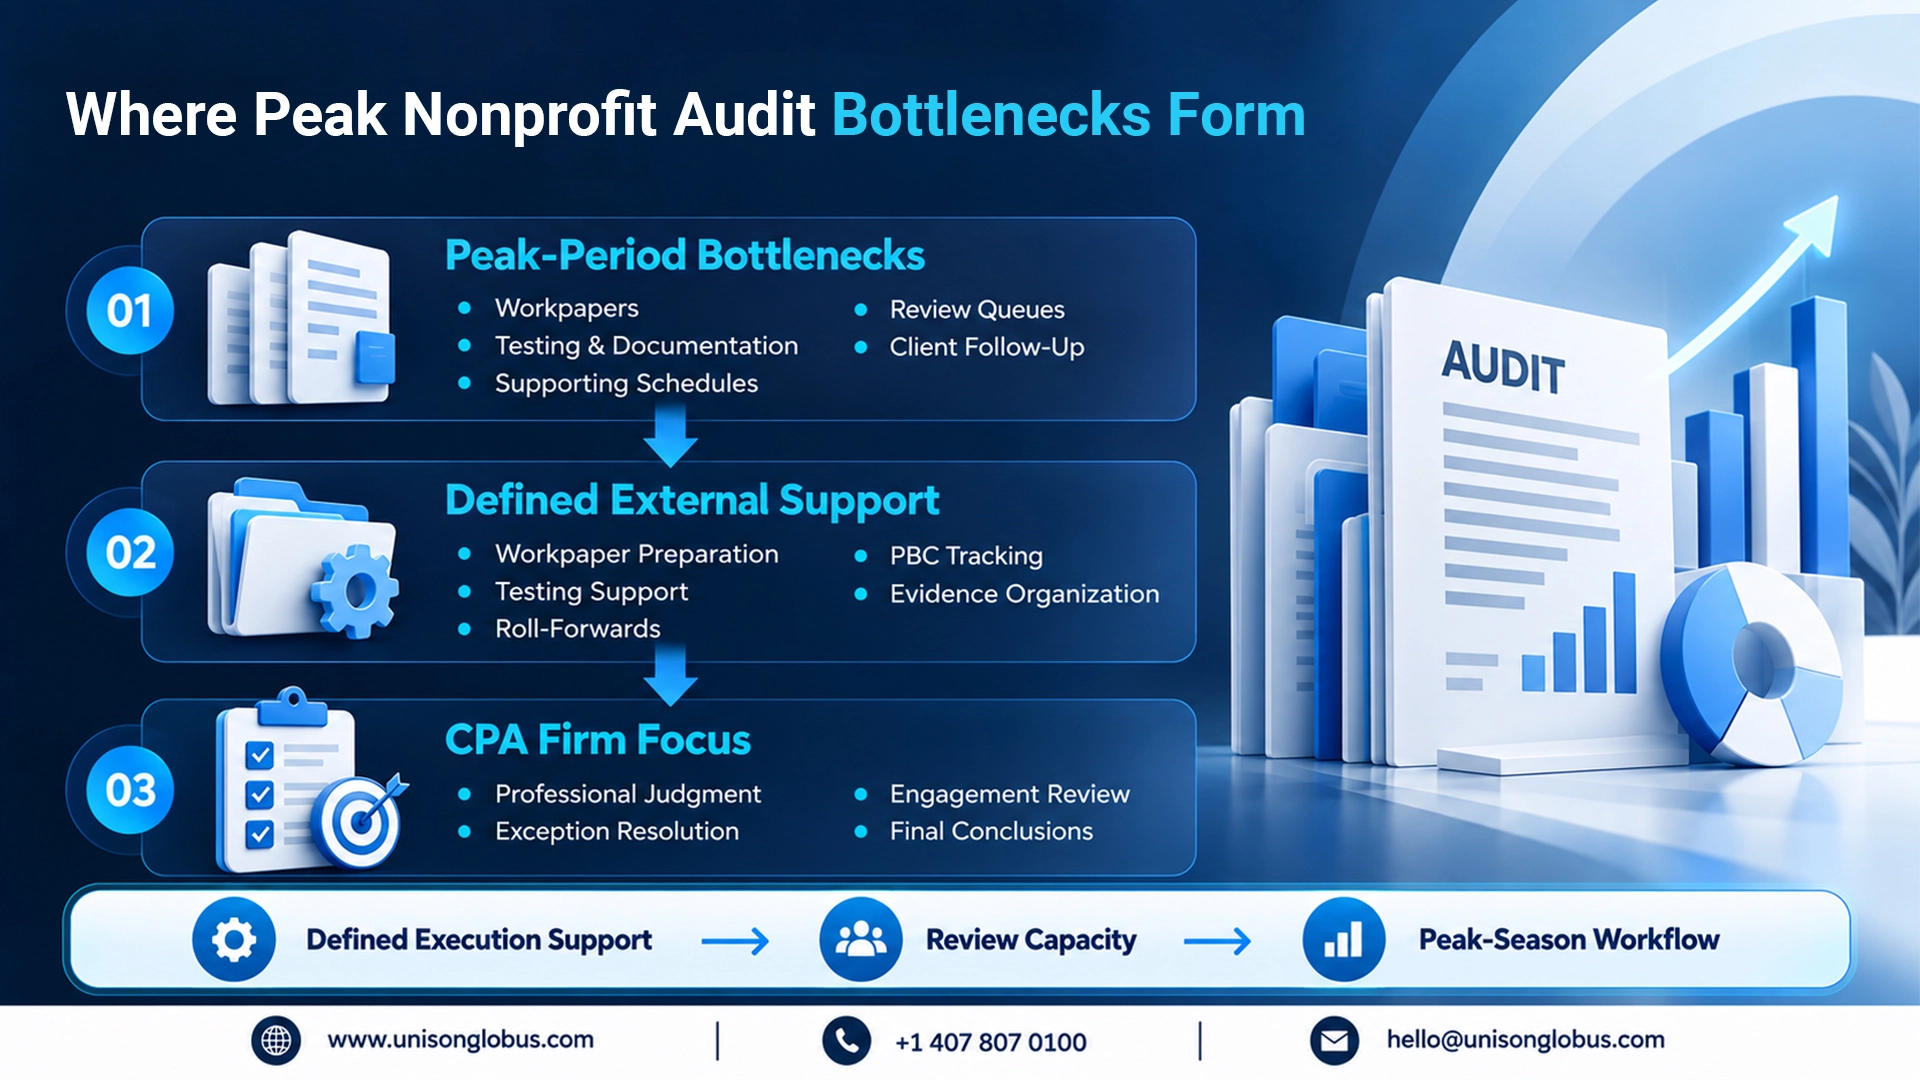
Where Peak-Period Audit Bottlenecks Actually Form
Workpaper Preparation
Workpaper preparation is one of the first places where pressure becomes visible. Lead schedules, reconciliations, supporting documentation, roll-forwards, and recurring workpapers still need to be completed even when senior professionals are already committed to reviewing other engagements.
When a senior or manager absorbs that preparation because no other qualified resource is available, the immediate file may move forward, but the review schedule can become compressed. Across several files, preparation that finishes later than planned leaves reviewers with less time to evaluate the work, investigate exceptions, and resolve open items before other engagements reach the same review stage.
The operational question is therefore whether the firm can complete defined preparation work early enough to protect reviewer capacity during peak periods.
Testing and Evidence Documentation
Testing and evidence documentation can become particularly demanding on nonprofit engagements involving federal awards, restricted grants, or other areas requiring detailed supporting evidence. The work may involve gathering documentation, organizing it against the relevant procedure, recording the testing performed, and identifying items that require attention from the engagement team.
The timing and organization of evidence matter because incomplete or poorly documented testing can create additional follow-up during review. Clear documentation of the procedure performed, evidence examined, and items requiring attention gives the engagement team a more structured basis for evaluating exceptions and determining the next step. Defined testing activities can therefore be supported externally when the firm’s procedures, documentation expectations, and escalation criteria are already established.
Roll-Forwards and Supporting Schedules
Roll-forwards and supporting schedules are recurring components of many audit engagements. They may involve less engagement-level judgment than final review, but they still require familiarity with the firm’s methodology, documentation expectations, and client-specific information.
Roll-forwards and supporting schedules are particularly suitable for a structured preparation model when the firm already has defined templates, prior-year information, and established documentation requirements. External support can organize recurring schedules against those requirements, giving the engagement team a consistent starting point for review and exception evaluation.
Review Queues
Review queues create a different constraint: several engagements can become review-ready at nearly the same time, even when each file progressed through preparation at a different pace.
A file that reaches review two weeks later than planned can occupy the same reviewer during a much more crowded period. For firms managing several nonprofit engagements, the challenge is therefore the concentration of review work across multiple files, rather than simply the number of preparation hours available.
Client Follow-Up
Client follow-up introduces another variable. Nonprofit finance teams may be coordinating board approvals, grant documentation, restricted-fund information, allocation details, and other supporting records while managing their regular accounting responsibilities.
When required information is missing, specific procedures may have to pause. The engagement team then has to determine what can continue, what requires follow-up, and what should remain open until the evidence arrives.
External support can help maintain PBC (Prepared by Client) trackers, organize outstanding requests, and flag missing items against the engagement team’s requirements. The engagement team still determines whether the available evidence is sufficient and what additional client communication or audit procedures are necessary.
Why Adding More Hands Doesn’t Always Solve the Problem
Firms have several ways to respond to peak demand, including overtime, seasonal hiring, and internal redistribution. Each can be appropriate depending on the duration and predictability of the workload.
The constraint appears when additional hours increase execution capacity without addressing the stage where the engagement is actually constrained. Internal redistribution can relieve one engagement while creating pressure on another, particularly when the same senior professionals are needed for review.
The U.S. Bureau of Labor Statistics projects about 115,300 openings for accountants and auditors each year, on average, from 2025 through 2035, with many openings reflecting replacement needs. BLS also notes that longer work periods are typical during periods such as quarterly audits and tax season. These figures cover the broader accountants-and-auditors occupation rather than nonprofit audit specifically.
The more useful management question is specific to the firm’s workflow: Which activities require the firm’s most experienced professionals, and which can be clearly assigned, documented, and reviewed by another qualified resource?
The answer can vary by engagement. A firm with sustained year-round demand may have a different staffing requirement from one that experiences concentrated nonprofit audit peaks several times a year.
Need additional support during peak nonprofit audits? See how we support CPA firms with workpapers, documentation, schedules, and defined testing.
Where Outsourced Audit Support Fits in the Engagement Workflow
Outsourced audit support provides additional execution capacity for clearly defined, reviewable engagement activities. Nonprofit audit support services can fit within the CPA firm’s existing procedures, templates, technology, and review framework.
| Engagement need | Potential external support | Internal CPA firm responsibility |
|---|---|---|
| Workpaper preparation | Defined preparation and organization | Review and approval |
| Supporting schedules | Roll-forwards and documentation | Evaluation and review |
| Defined testing support | Testing and evidence documentation under established procedures | Professional evaluation and conclusions |
| PBC organization | Tracking and documentation support | Client relationship and follow-up decisions |
| Documentation | Workpaper and evidence organization | Review of sufficiency and appropriateness |
| Exceptions | Identification and escalation | Resolution and professional judgment |
| Review notes | Administrative preparation support | Evaluation and final disposition |
A practical workflow can therefore run through:
Assign → Prepare → Document → Identify Exceptions → Review → Resolve → Final Engagement Review
When the external team identifies an unusual transaction, incomplete evidence, or judgment-sensitive matter, it should escalate the item to the firm’s engagement team.
The firm’s professionals then evaluate the matter, perform the required review, determine the appropriate response, reach engagement-level conclusions, and retain final oversight.
Clarification: External execution does not transfer engagement responsibility
A support provider can perform defined engagement activities while the CPA firm retains responsibility for professional evaluation, significant-matter decisions, engagement conclusions, client decisions, and final engagement oversight.
For firms evaluating audit support for CPA firms, the important question is therefore how the external work enters the firm’s existing process. A provider that can complete individual tasks but requires managers to rebuild the work or operate a separate documentation process may add coordination rather than remove it.
Nonprofit Audit Work Requires Engagement-Specific Support
Nonprofit engagements contain accounting and reporting considerations that affect how preparation work should be organized. The support model therefore needs to reflect the nature of the organization, its funding arrangements, and the applicable financial reporting and audit requirements.
The 2026 AICPA Not-for-Profit Entities – Audit and Accounting Guide covers distinctive NFP accounting, financial statement preparation, and auditing considerations, including audit planning, risk assessment, financial statements, contributions, agency transactions, and fund accounting.
Contributions and Donor Restrictions
Contribution-related work can require supporting schedules that distinguish restricted and unrestricted activity and preserve the documentation necessary for the engagement team’s evaluation. The underlying records and supporting evidence should align with the firm’s established audit procedures and documentation requirements.Net Asset Classification
Net asset classification requires supporting information that reflects applicable donor restrictions and financial reporting requirements. External support can organize the underlying information, while the engagement team evaluates the classification and supporting documentation.Functional Expense Information
Where the engagement involves functional expense allocation, preparation should preserve the client’s underlying records, allocation methodology, and supporting documentation for the engagement team’s evaluation. Where those elements are already defined, the work may be suitable for structured external support.Grants and Federal Awards
Grant-funded organizations can introduce additional documentation and coordination requirements. Engagement teams may need information concerning grant terms, expenditures, compliance requirements, and supporting records before particular procedures can be completed. The engagement team evaluates whether the evidence satisfies the applicable audit procedures and determines the response to exceptions, compliance matters, or unusual circumstances.Single Audit Support
Single Audit engagements add federal compliance work alongside the financial statement audit. Depending on the engagement, support may involve documentation, testing performed under established procedures, and organization of evidence associated with federal programs and the SEFA.
GAO analyzed 3,680 Single Audit findings from audit years 2022 through 2024 that were addressed to prime recipients that passed federal funds through to subrecipients. The analysis identified recurring compliance issues involving areas such as subaward reporting, subrecipient monitoring, and eligibility decisions.
(Source: GAO report: GAO, Grants Management: Recent Guidance Could Enhance Subaward Oversight)
This analysis does not measure outsourcing demand or audit workload directly. It provides context on the types of compliance issues identified through Single Audits involving federal subawards.
For firms handling this work, provider familiarity with nonprofit and Single Audit processes becomes a practical selection criterion. General audit experience does not necessarily indicate familiarity with the documentation and compliance requirements involved in a particular NFP engagement.
What Firms Should Validate Before Using External Audit Support
- Professional Judgment and Responsibility: The firm should clearly distinguish execution support from activities requiring professional judgment, significant-matter evaluation, or engagement-level conclusions.
- Quality and Review: Externally prepared work should follow the firm’s existing review structure, documentation expectations, procedures, and review criteria.
- Confidentiality and Data Security: Firms should understand how engagement information is accessed, transferred, stored, and restricted, particularly where nonprofit records, donor information, employee data, or federal award documentation are involved.
- Technology and Workflow Integration: Firms should evaluate compatibility with their audit software, templates, documentation conventions, and file structures to avoid unnecessary handoffs and additional coordination.
- Scope and Task Ownership: The firm should clearly define what is assigned externally, what remains internal, and which matters require escalation. A task that becomes more complex during preparation should return to the appropriate engagement professional.
- Communication and Escalation: The support model should establish how exceptions, unusual transactions, missing evidence, and ambiguous items are escalated to the engagement team and how the next step is communicated.
- Nonprofit Experience: When evaluating an offshore audit team, firms should consider relevant experience with restricted contributions, nonprofit financial statements, grant activity, Uniform Guidance considerations, and Single Audit documentation.
How to Compare Capacity Options During Peak Audit Periods
Outsourced support is one option within a broader set of capacity approaches. Firms can compare the alternatives based on how long the demand lasts, how quickly support is required, what skills the work demands, and how closely the resource needs to operate within the existing engagement structure.
| Capacity model | Best fit to evaluate around | Key considerations |
|---|---|---|
| Permanent hiring | Recurring, year-round demand | Recruitment, development, retention, and ongoing cost |
| Seasonal hiring | Predictable seasonal volume | Hiring timeline, onboarding, availability, and training |
| Overtime | Immediate short-term pressure | Existing team capacity and sustainability |
| Internal redistribution | Uneven workload across teams | Effect on the engagements losing that capacity |
| Selective outsourced support | Defined, variable execution needs | Scope clarity, review structure, security, and provider fit |
The comparison should also consider how the firm repeatedly absorbs peak periods. If senior professionals move into preparation work, review can become concentrated later in the engagement. If managers absorb routine client coordination, their review schedules become less predictable.
These patterns can show where the firm’s current operating model is absorbing seasonal demand and whether a defined execution resource could address a specific constraint.
When Outsourced Audit Support Is Worth Evaluating
Outsourced audit support is worth evaluating when a firm can identify recurring activities that consume meaningful preparation time during peak periods and define those activities clearly enough for another qualified resource to perform and document them.
The model can be particularly relevant when several nonprofit engagements overlap, demand varies significantly by season, and the firm already has established review procedures.
A different approach may deserve attention first when a first-year engagement involves unusual complexity, work remains judgment-heavy throughout, scope is unclear, or internal review procedures are inconsistent.
The strongest starting point is a defined portion of the workflow where task ownership, documentation expectations, review procedures, and escalation paths are already understood. For firms considering offshore audit services, the same principle applies: external support can strengthen a defined workflow, but it cannot compensate for unclear task ownership, incomplete documentation, weak review criteria, or poor engagement planning.
Where This Leaves the Peak-Season File
The October schedule makes the distinction clear. The same nonprofit engagements are still running, client documentation still arrives at different times, and the firm still has to meet its engagement deadlines.
For firms considering outsourced audit support, the practical question is which activities require the firm’s highest-level expertise and which defined execution tasks can be prepared externally and brought back into the established review structure.
Here, Unison Globus supports Audit Support Services for CPAs and Accounting Firms, covering defined audit preparation, documentation, workpaper, schedule, and testing activities within the firm’s engagement workflow. For firms managing peak periods, its offshore audit support can help keep defined preparation work moving while the CPA firm retains professional judgment, review authority, and final engagement responsibility.
Audit Workload Challenges Extend Beyond One Market
While nonprofit audit requirements vary by jurisdiction, accounting firms across markets face similar pressure during peak periods: keeping preparation, documentation, and review work moving while senior professionals manage deadlines and engagement oversight. The specific requirements differ, but the underlying challenge of balancing routine execution with senior-level review is widely shared.
In the UK, firms manage peak pressures around year-end accounts, tax compliance, and audit and assurance services. In Australia, audit and assurance engagements can create similar demands on preparation, documentation, and review teams. In the US, nonprofit audits, Single Audits, and year-end engagements can place additional pressure on preparation and review workflows.
For firms exploring offshore capacity, the provider’s location is only one consideration. An audit outsourcing company in India may support defined preparation and documentation activities, but firms should evaluate the provider’s nonprofit experience, review processes, security controls, technology compatibility, and ability to work within the existing engagement workflow.