

 [gtranslate]
Summarize and analyze this article with:
- Year-End BAS Review Starts Where Small Errors Become Review Problems
- Why BAS Errors Survive the Review Process
- Insight:
- What the ATO Data Says About GST Compliance Risk
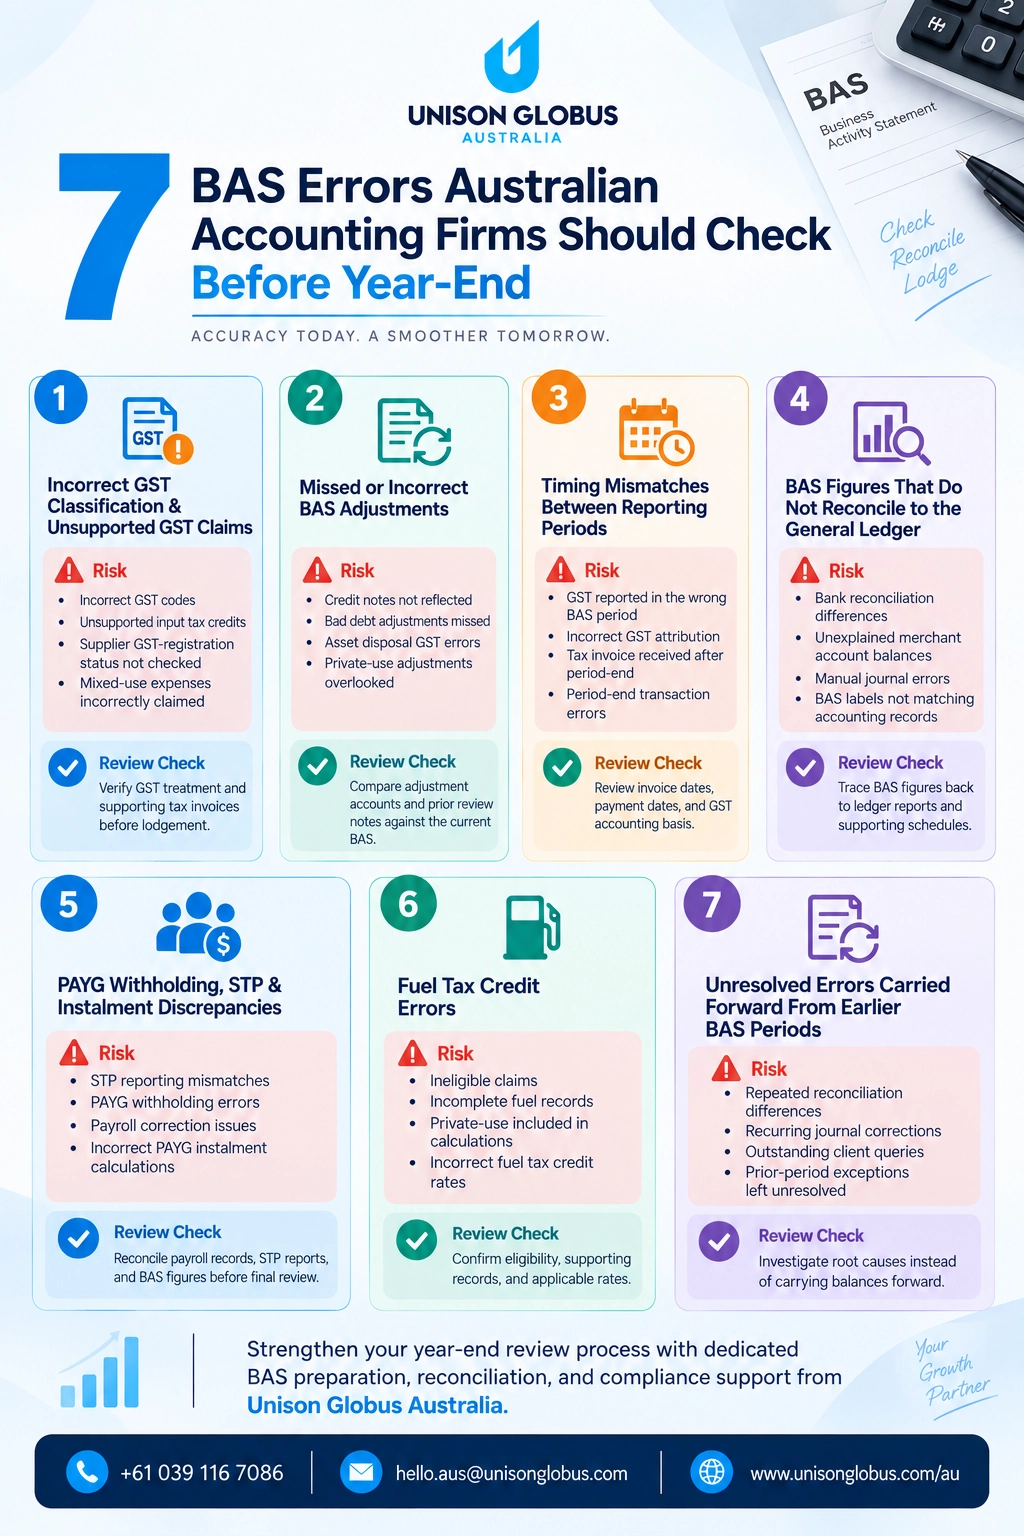
- 7 BAS Errors to Check Before Year-End
- 1. Incorrect GST Classification and Unsupported GST Claims
- 2. Missed or Incorrect BAS Adjustments
- 3. Timing Mismatches Between Reporting Periods
- 4. BAS Figures That Do Not Reconcile to the General Ledger
- 5. PAYG Withholding, STP or Instalment Discrepancies
- 6. Fuel Tax Credit Errors Where Applicable
- 7. Unresolved Errors the Team Carries Forward from Earlier BAS Periods
- What Year-End Workload Does to BAS Review Capacity
- How Outsourced BAS Review Can Close These Checking Gaps
- What Firms Should Check Before Outsourcing BAS Review & Finalisation
- When Outsourced BAS Review Makes Operational Sense
- Return to the Year-End BAS Review Question
- How Unison Globus Australia Supports BAS Review and Reconciliation
- Compliance Review Challenges Extend Beyond Australia
- Frequently Asked Questions
- What BAS errors should accounting firms check before the FY2027 year-end?
- Why should firms review BAS processes before year-end?
- What do outsourced BAS services typically support?
- Can an accounting firm outsource BAS review work offshore?
- What should firms check before using an offshore BAS support provider?
- When does BAS review outsourcing make sense?
- What Is Included in a BAS Compliance Review?
- How Often Should Accounting Firms Perform a BAS Compliance Review?
- Can Outsourced BAS Support Improve Year-End Review Capacity?
A BAS Compliance Review helps Australian accounting firms identify GST, PAYG and reconciliation issues before year-end. For firms handling high BAS volumes, identifying recurring errors early can reduce review bottlenecks and improve compliance outcomes.
Consider a Melbourne practice reviewing BAS compliance for 180 quarterly clients. As the firm prepares for the FY2027 year-end cycle, a GST coding inconsistency across several construction clients has survived three routine review cycles and now surfaces during year-end reconciliation.
The team can correct the issue. However, doing so requires senior review time, additional client queries and a review of earlier BAS periods. For firms considering outsourced BAS services, the more useful question is where defined support can strengthen checking without replacing professional judgement.
BAS preparation creates the reported figures. BAS reviews whether those figures make sense against client records, prior periods and underlying transactions. When deadlines are compressed, firms can protect preparation output while reducing time for deeper exception checking. A robust workflow connects preparation, reconciliation, exception identification, professional review and lodgement.
What Is a BAS Compliance Review?
A BAS compliance review is the process of checking GST, PAYG withholding, PAYG instalments, reconciliations, supporting documentation and reporting accuracy before BAS lodgement.
Year-End BAS Review Starts Where Small Errors Become Review Problems
A BAS review becomes more demanding when small issues sit across different parts of the file. GST coding, reconciliations, payroll records and supporting documents may look manageable in isolation, but together they can consume significant senior review time.
A controlled BAS workflow should move through:
- Preparation: Compile transactions, payroll information, adjustments and supporting records.
- Reconciliation: Compare BAS figures with the general ledger, bank activity and relevant sub-ledgers.
- Exception identification: Isolate unusual movements, missing documentation and unresolved items.
- Professional review: Apply judgement to material or technically complex matters.
- Lodgement: Finalize the BAS after the practice resolves outstanding review points.
The objective is not to check every transaction manually. It is to ensure the workflow consistently identifies the items that require deeper review. Many Australian accounting firms use dedicated offshore BAS review support from Unison Globus Australia to strengthen reconciliation and exception checking processes while retaining full professional oversight.
Struggling with BAS review bottlenecks during peak periods? Explore how dedicated offshore BAS support can help your firm improve review capacity and turnaround time.
Why BAS Errors Survive the Review Process
Compressed review cycles change what reviewers can realistically investigate. A senior accountant checking twelve BAS files in two hours may confirm totals and obvious movements but have little time to trace an unusual transaction back to its source document.
The difference matters because arithmetic checks and exception checks require different levels of attention.
Preparation capacity and review capacity also solve different problems. Adding another preparer can increase throughput, but it does not automatically create more senior time to investigate unusual transactions, challenge assumptions or resolve reconciling items.
When a firm expands preparation without strengthening review capacity, senior staff can end up reconstructing work instead of reviewing it. That creates more rework and leaves less time for genuinely unusual issues.
Recurring errors expose the same weakness more clearly. If a GST coding problem reaches the BAS once and the workflow never introduces a control around that transaction type, the same issue can return in the next reporting period.
Insight:
A recurring BAS error often tells a firm more about its control points than its staff knowledge. The useful question becomes: which review step should I identify the issue earlier?
What the ATO Data Says About GST Compliance Risk
The ATO’s GST administration data provides useful context for firms reviewing their controls. For 2022–23, the ATO estimated a gross GST gap of 12.6% of theoretical GST and a net gap of $7.9 billion, or 9.0%. The GST gap measures the difference between GST collected and the amount the ATO estimates it would collect if taxpayers fully complied with the law.
For an accounting firm, the more useful application of that context is to examine where routine BAS workflows can allow GST issues to pass through preparation and into review.
Which recurring control gaps could allow an incorrect BAS figure to pass through preparation and review?
7 BAS Errors to Check Before Year-End
The following checks focus on errors that can survive routine processing when firms rely heavily on recurring workflows or compressed review cycles.
1. Incorrect GST Classification and Unsupported GST Claims
A GST error can start with an incorrect tax code and continue through BAS preparation when the team does not verify the underlying transaction.
Where the risk appears:
- GST classification: Check whether the tax code correctly reflects taxable, GST-free or input-taxed treatment, and whether the acquisition supports an input tax credit.
- Unsupported claims: The practice cannot substantiate an input tax credit because it does not hold sufficient supporting documentation. For purchases of more than $82.50 including GST, the practice generally needs to hold a valid tax invoice before claiming the GST credit.
- Supplier status: The supplier does not hold GST registration where registration affects the claim.
- Mixed-use expenses: The bookkeeping process claims the full GST amount even though the expense has a private component.
Example: A client purchases equipment partly for business and partly for private use. The bookkeeping file claims the full input tax credit without documenting the business-use proportion. During the year-end BAS review, the firm needs to verify the claim against the underlying evidence and applicable GST treatment.
Include unusual tax codes, high-value purchases, new suppliers and mixed-use expenses in the year-end BAS review and verify the supporting evidence before finalising the BAS.
2. Missed or Incorrect BAS Adjustments
Adjustments can arise from credit notes, private-use changes, asset disposals and GST bad-debt adjustments. Each situation requires the practice to confirm the relevant GST treatment before finalising the BAS.
Where the risk appears:
- Credit notes: Previous GST treatment no longer reflects the revised transaction.
- Bad debts: For clients that account for GST on a non-cash basis, confirm that the client attributed GST on the taxable supply and that the debt remains unpaid because the client has written it off as bad or the debt has remained overdue for 12 months or more. The ATO’s GST adjustment guidance sets out these conditions and excludes the Division 21 bad-debt adjustment for entities that account for GST on a cash basis.
- Asset disposals: The GST treatment of a business asset disposal does not flow correctly into the BAS.
- Private use: Business expenses or assets also have a private component.
Review focus: Compare adjustment accounts, credit notes, asset disposals, private-use entries and prior-period review notes with the current BAS. Escalate items that require technical judgement before finalising the activity statement.
3. Timing Mismatches Between Reporting Periods
Timing errors can move GST into the wrong BAS period even when the transaction itself contains the correct amount.
Where the risk appears:
- GST attribution: Check whether the team applied the client’s cash or non-cash GST accounting basis correctly when determining the relevant BAS period.
- Tax invoice timing: Confirm that the practice holds the required tax invoice when it claims an input tax credit on the BAS, particularly where invoice timing crosses a reporting period.
- Period-end transactions: Review transactions close to the reporting-period boundary where payment, invoice issuance or tax-invoice availability could affect GST attribution.
- Manual journals: Period-end entries affect GST balances without adequate supporting documentation.
Example: A supplier issues an invoice before quarter-end, but the practice receives the supporting tax invoice after the reporting period closes. The reviewer checks the client’s GST accounting basis, the applicable attribution period and whether the practice held the tax invoice when lodging the BAS before deciding which period should include the input tax credit.
Include GST attribution in the BAS preparation and review support process. Check significant period-end transactions against the client's GST accounting basis, payment and invoice dates, tax-invoice availability and BAS period before escalating unexpected timing differences.
4. BAS Figures That Do Not Reconcile to the General Ledger
A BAS can balance internally while still failing a broader reconciliation with the accounting records. BAS reconciliation and compliance services should therefore trace reported figures back to the general ledger, control accounts and supporting schedules. Poor reconciliations often originate from underlying bookkeeping issues that were not addressed earlier in the reporting cycle.
Where the risk appears:
- Bank accounts: GST-related transactions do not agree with reconciled bank activity.
- Merchant facilities: Clearing balances or transaction fees remain unexplained.
- GST-relevant loan entries: Check fees, charges and other loan-related transactions for the correct GST treatment rather than treating the loan balance itself as a GST item.
- Manual journals: Entries bypass normal transaction workflows.
- BAS labels: Reported figures do not trace cleanly to ledger reports.
Example: The BAS reports the expected GST amount, but the GST control account carries a recurring unexplained balance. The team clears the difference with a journal each quarter instead of investigating its source.
Trace significant BAS labels back to the general ledger and supporting schedules. Investigate recurring differences rather than repeatedly correcting them.
5. PAYG Withholding, STP or Instalment Discrepancies
Payroll information can create BAS exceptions when STP reporting, payroll records and activity statement figures do not align. Payroll compliance and STP accuracy play an important role in reducing BAS review exceptions.
Where the risk appears:
- STP reporting: Payroll totals differ from information reported through STP.
- PAYG withholding: Withholding amounts do not reconcile with payroll records.
- Payroll adjustments: Corrections or unusual pay runs create unexplained differences.
- PAYG instalments: The instalment position no longer reflects the client’s expected business or investment income.
Example: A payroll correction changes PAYG withholding after the team prepares the BAS. The correction reaches the payroll records but does not flow into the figures used for BAS preparation.
What to do: Reconcile payroll, STP and PAYG withholding before final review. Check the client’s PAYG instalment calculation against expected liability and confirm whether the 2026–27 5% GDP adjustment applies to the method the client uses.
Reconcile payroll, STP and PAYG withholding before final review. Check the client’s PAYG instalment calculation against expected liability and confirm whether the 2026–27 5% GDP adjustment applies to the method the client uses.
6. Fuel Tax Credit Errors Where Applicable
Fuel tax credits create an additional review point for eligible clients. Errors can arise from eligibility, fuel records, business use or rate application.
Where the risk appears:
- Eligibility: The client’s activities do not meet the relevant requirements.
- Fuel records: Quantities or supporting records do not adequately support the claim.
- Business use: The calculation includes ineligible or private use.
- Rates: The team applies an incorrect rate for the relevant period.
Review focus:
Treat fuel tax credits as an exception-based check. Confirm eligibility, fuel records, business use and the applicable rates before including the claim.
Where the BAS includes a fuel tax credit claim, verify the supporting documentation, assess the calculation and confirm that the team applied the correct rate for the relevant claim period. Escalate any unusual or material claims for further review.
7. Unresolved Errors the Team Carries Forward from Earlier BAS Periods
A recurring unresolved BAS difference can indicate a control issue when the team repeatedly clears or carries it forward without identifying the underlying cause or determining the appropriate correction. A routine bookkeeping adjustment resolves a known transaction-level issue; a recurring unexplained difference requires investigation, ownership and escalation.
Where the risk appears:
- Prior-period differences: Reconciliation items remain open.
- Recurring journals: The same account requires repeated corrective entries.
- Client queries: The practice continues requesting the same missing information.
- Review notes: Previous exceptions remain unresolved.
- Corrections: The team carries an earlier error forward instead of determining the appropriate correction.
Example: A GST control account has carried a small difference for three consecutive BAS periods. Each quarter, the preparation team posts a journal to clear the balance without identifying the original transaction causing the difference.
Maintain an exception trail, assign ownership and determine the appropriate correction before the next BAS cycle. Where an earlier GST error requires correction, assess the applicable ATO correction rules rather than repeatedly clearing the difference.
What Year-End Workload Does to BAS Review Capacity
Year-end pressure can reduce the amount of time senior staff have available for BAS review. When senior staff receive a large group of BAS files together, they may spend more time locating missing information and resolving basic preparation issues. Many firms use outsourced accounting support to manage seasonal workload spikes without increasing permanent headcount.
That leaves less time for:
- Trend analysis: Investigating unusual GST movements.
- Reconciliation: Following differences across multiple accounts.
- Exception review: Assessing unusual or technically complex transactions.
- Client communication: Resolving questions before the lodgement deadline.
- Professional judgement: Considering matters that require senior oversight.
The issue therefore concerns whether the practice has enough review capacity to assess BAS files after preparation, reconciliation and exception handling.
How Outsourced BAS Review Can Close These Checking Gaps
Outsourced BAS services can provide defined BAS preparation and review support within the firm’s existing preparation, reconciliation and checking workflow. Firms looking for broader support may also combine BAS processes with outsourced accounting and bookkeeping functions.
A controlled model can follow this sequence:
Preparation → Checking → Exception escalation → Internal professional review → Lodgement
The external team can support tasks such as:
- Reconciliations: Compare BAS figures with ledger and supporting records.
- Exception identification: Flag unusual GST treatment, missing documents and unexplained differences.
- Adjustment checks: Identify potential BAS adjustments for internal assessment.
- Payroll reconciliation: Compare payroll, STP and PAYG withholding information.
- Prior-period review: Highlight recurring unresolved items.
- Workpaper preparation: Organise supporting schedules and review notes for the firm’s team.
The handoff should give the firm a clear set of exceptions, reconciliations and supporting schedules to assess during professional review.
What Firms Should Check Before Outsourcing BAS Review & Finalisation
Professional Responsibility and Supervision
The practice should establish:
- Defined responsibilities: Document which tasks the provider performs and which decisions remain with the practice.
- Escalation rules: Identify matters that require registered practitioner involvement.
- Review controls: Set expectations for sampling, exception handling and feedback.
- Auditability: Maintain a clear record of preparation, review comments and changes.
The practice should define where BAS preparation and review support ends and where its own professional review and decision-making begin. Before engaging a provider, the firm should also confirm whether the provider’s activities constitute a BAS service that requires TPB registration or fall within an applicable exemption. The TPB’s guidance on supervision, competency and quality management provides expectations for supervision arrangements, workflow oversight, review processes, file management, escalation pathways and quality controls. The TPB’s guidance on outsourcing and offshoring focuses on the additional considerations that arise when engaging external providers, including competency, supervision, client disclosure obligations and compliance with the Code of Professional Conduct.
Data Security and Offshore Processing
If the arrangement involves offshore processing, firms should assess:
- Access controls: Limit system and file access according to role.
- Data transfer: Establish secure methods for sharing client information.
- Contractual controls: Set enforceable requirements for information handling, subcontracting and breach notification.
- Audit trails: Maintain visibility over file access and changes.
- Incident procedures: Confirm how the provider handles security incidents.
The OAIC’s APP 8 guidance on cross-border disclosure requires APP entities to take reasonable steps before disclosing personal information to overseas recipients and can hold the Australian entity accountable for certain overseas handling.
Client Disclosure and Engagement Terms
The firm should also confirm:- Client information: Confirm whether the arrangement requires client permission to disclose information to an external provider and whether any privacy or cross-border disclosure obligations apply.
- Engagement terms: Address third-party and offshore processing where relevant.
- Client communication: Define who requests outstanding information and manages client communication.
- Professional decisions: Keep technical judgement and engagement decisions within the firm’s defined responsibility structure.
Commercial Fit
The commercial model should support the firm’s existing workflow without creating another layer of review or administration. Firms should assess:
- Defined scope: Confirm exactly which preparation, reconciliation and checking activities the provider performs and where the firm’s review begins.
- Workflow integration: Check whether the provider can work within the firm’s existing systems, documentation standards and handoff process.
- Review burden: Assess whether external checking produces clear exceptions and review-ready files rather than creating additional reconstruction work.
- Service structure: Confirm how the arrangement handles recurring work, peak-period requirements, escalation and changes in workload.
- Commercial terms: Examine pricing, minimum commitments and scope boundaries against the firm’s intended use of the service.
When Outsourcing Does Not Solve the Problem
BAS preparation and review support can strengthen a defined workflow, but the practice should address underlying control gaps before adding external support. Review the process first when:- Client records: Address recurring gaps where incomplete records delay preparation and exception review.
- GST coding: Standardise coding rules where bookkeeping and BAS services rely on workflows that repeatedly apply inconsistent GST treatment.
- Exception ownership: Assign responsibility for unresolved items so issues do not remain open across BAS cycles.
- Escalation criteria: Define the points that require senior or registered practitioner review.
- Professional review: Establish the firm’s review responsibilities before assigning preparation or checking activities externally.
When Outsourced BAS Review Makes Operational Sense
The model may fit when the practice has a recurring, clearly defined group of preparation or checking activities that compete with higher-value review work.
Typical indicators include:
- Seasonal workload spikes: BAS volumes increase faster than available review capacity.
- Senior bottlenecks: Experienced accountants spend review time on routine reconciliations.
- Recurring exceptions: Teams repeatedly investigate the same preparation issues.
- Backlog risk: Completed BAS files wait for review close to lodgement deadlines.
The practical test is whether the firm can isolate repeatable activities without weakening its internal review controls.
Looking to strengthen reconciliation, exception identification, and year-end BAS review processes? Talk to our team about a tailored support model.
Return to the Year-End BAS Review Question
A year-end BAS review should answer more than whether the activity statement balances. It should confirm correct GST treatment, trace significant figures to supporting records, resolve unexplained differences and align payroll and PAYG information.
When earlier exceptions remain unresolved, the issue may sit within the workflow rather than a single BAS. The core question is straightforward: can the practice identify and escalate exceptions before professional review and lodgement? Where the answer remains unclear, strengthen the process before the next BAS cycle.
How Unison Globus Australia Supports BAS Review and Reconciliation
Unison Globus Australia provides BAS Review & Lodgement Support for Australian Businesses, covering defined preparation, reconciliation, exception identification and review support activities, with the firm’s professional team applying the relevant judgement and approval controls.
- BAS preparation: Prepare activity statement figures and supporting workpapers.
- GST reconciliation: Compare reported figures with accounting records.
- Exception identification: Flag unusual treatment, missing evidence and unexplained differences.
- Review support: Organise schedules and review points for the firm’s professional team.
- PAYG and prior-period checks: Reconcile payroll information and recurring exceptions.
The firm defines the provider’s role and applies the appropriate professional judgement, review, supervision and engagement controls for the arrangement. While Australian firms focus on BAS, GST and ATO compliance obligations, accounting firms globally face similar review-capacity challenges during peak workloads and reporting periods.
Compliance Review Challenges Extend Beyond Australia
While BAS compliance reviews are unique to Australia’s GST and ATO reporting framework, the underlying challenge is often the same across accounting firms globally: maintaining review quality during periods of increasing workload. Whether firms are managing BAS reviews, year-end accounts, tax compliance, or reconciliation processes, capacity constraints can place additional pressure on senior review teams.
For example, many firms in the United States use outsourced bookkeeping and accounting support for CPA firms to improve workflow efficiency, strengthen reconciliations, and manage peak workload periods without increasing permanent headcount.
Similarly, accounting practices in the United Kingdom often rely on year-end accounts and bookkeeping support for UK accounting firms to maintain reporting accuracy and meet compliance deadlines during busy reporting cycles.
Canadian accounting firms face comparable challenges around reconciliations, financial reporting, and resource planning, leading many practices to adopt accounting support for Canadian firms as part of their broader operational strategy.
Regardless of jurisdiction, the common objective remains the same: ensuring routine preparation and reconciliation activities are completed efficiently so senior professionals can focus on review, advisory, and compliance oversight.