Categories
BAS Home Aus

BAS Compliance Review: Common Errors Australian Accounting Firms Should Address Before Year-End

A BAS Compliance Review helps Australian accounting firms identify GST, PAYG and reconciliation issues before year-end. For firms handling high BAS volumes, identifying recurring errors early can reduce review bottlenecks and improve compliance outcomes.

Consider a Melbourne practice reviewing BAS compliance for 180 quarterly clients. As the firm prepares for the FY2027 year-end cycle, a GST coding inconsistency across several construction clients has survived three routine review cycles and now surfaces during year-end reconciliation.

The team can correct the issue. However, doing so requires senior review time, additional client queries and a review of earlier BAS periods. For firms considering outsourced BAS services, the more useful question is where defined support can strengthen checking without replacing professional judgement.

BAS preparation creates the reported figures. BAS reviews whether those figures make sense against client records, prior periods and underlying transactions. When deadlines are compressed, firms can protect preparation output while reducing time for deeper exception checking. A robust workflow connects preparation, reconciliation, exception identification, professional review and lodgement. 

What Is a BAS Compliance Review?

A BAS compliance review is the process of checking GST, PAYG withholding, PAYG instalments, reconciliations, supporting documentation and reporting accuracy before BAS lodgement.

Year-End BAS Review Starts Where Small Errors Become Review Problems

A BAS review becomes more demanding when small issues sit across different parts of the file. GST coding, reconciliations, payroll records and supporting documents may look manageable in isolation, but together they can consume significant senior review time.


A controlled BAS workflow should move through:

  • Preparation: Compile transactions, payroll information, adjustments and supporting records.
  • Reconciliation: Compare BAS figures with the general ledger, bank activity and relevant sub-ledgers.
  • Exception identification: Isolate unusual movements, missing documentation and unresolved items.
  • Professional review: Apply judgement to material or technically complex matters.
  • Lodgement: Finalize the BAS after the practice resolves outstanding review points.

The objective is not to check every transaction manually. It is to ensure the workflow consistently identifies the items that require deeper review. Many Australian accounting firms use dedicated offshore BAS review support from Unison Globus Australia to strengthen reconciliation and exception checking processes while retaining full professional oversight.

Struggling with BAS review bottlenecks during peak periods? Explore how dedicated offshore BAS support can help your firm improve review capacity and turnaround time.

Why BAS Errors Survive the Review Process

Compressed review cycles change what reviewers can realistically investigate. A senior accountant checking twelve BAS files in two hours may confirm totals and obvious movements but have little time to trace an unusual transaction back to its source document.


The difference matters because arithmetic checks and exception checks require different levels of attention.


Preparation capacity and review capacity also solve different problems. Adding another preparer can increase throughput, but it does not automatically create more senior time to investigate unusual transactions, challenge assumptions or resolve reconciling items.


When a firm expands preparation without strengthening review capacity, senior staff can end up reconstructing work instead of reviewing it. That creates more rework and leaves less time for genuinely unusual issues.


Recurring errors expose the same weakness more clearly. If a GST coding problem reaches the BAS once and the workflow never introduces a control around that transaction type, the same issue can return in the next reporting period.

Insight:

A recurring BAS error often tells a firm more about its control points than its staff knowledge. The useful question becomes: which review step should I identify the issue earlier?

What the ATO Data Says About GST Compliance Risk

The ATO’s GST administration data provides useful context for firms reviewing their controls. For 2022–23, the ATO estimated a gross GST gap of 12.6% of theoretical GST and a net gap of $7.9 billion, or 9.0%. The GST gap measures the difference between GST collected and the amount the ATO estimates it would collect if taxpayers fully complied with the law.


For an accounting firm, the more useful application of that context is to examine where routine BAS workflows can allow GST issues to pass through preparation and into review.


Which recurring control gaps could allow an incorrect BAS figure to pass through preparation and review?

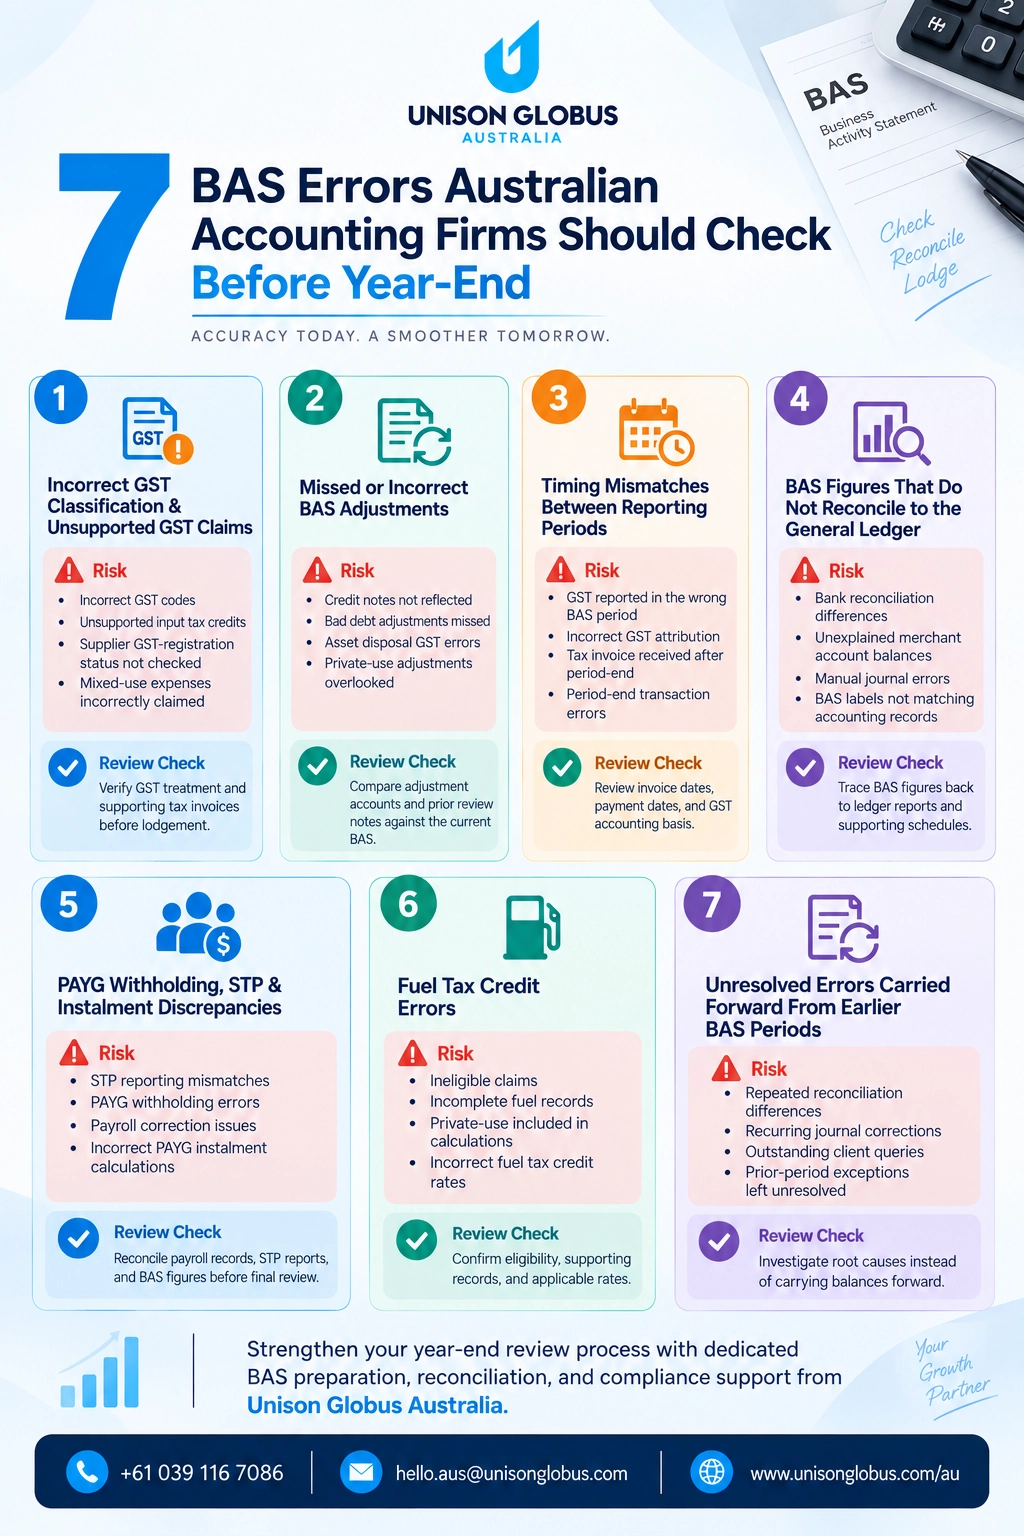
7 BAS Errors to Check Before Year-End

The following checks focus on errors that can survive routine processing when firms rely heavily on recurring workflows or compressed review cycles.

1. Incorrect GST Classification and Unsupported GST Claims

A GST error can start with an incorrect tax code and continue through BAS preparation when the team does not verify the underlying transaction.

Where the risk appears:

  • GST classification: Check whether the tax code correctly reflects taxable, GST-free or input-taxed treatment, and whether the acquisition supports an input tax credit.
  • Unsupported claims: The practice cannot substantiate an input tax credit because it does not hold sufficient supporting documentation. For purchases of more than $82.50 including GST, the practice generally needs to hold a valid tax invoice before claiming the GST credit.
  • Supplier status: The supplier does not hold GST registration where registration affects the claim.
  • Mixed-use expenses: The bookkeeping process claims the full GST amount even though the expense has a private component.

Example: A client purchases equipment partly for business and partly for private use. The bookkeeping file claims the full input tax credit without documenting the business-use proportion. During the year-end BAS review, the firm needs to verify the claim against the underlying evidence and applicable GST treatment.

✓ What to do

Include unusual tax codes, high-value purchases, new suppliers and mixed-use expenses in the year-end BAS review and verify the supporting evidence before finalising the BAS.


2. Missed or Incorrect BAS Adjustments

Adjustments can arise from credit notes, private-use changes, asset disposals and GST bad-debt adjustments. Each situation requires the practice to confirm the relevant GST treatment before finalising the BAS.


Where the risk appears:

  • Credit notes: Previous GST treatment no longer reflects the revised transaction.
  • Bad debts: For clients that account for GST on a non-cash basis, confirm that the client attributed GST on the taxable supply and that the debt remains unpaid because the client has written it off as bad or the debt has remained overdue for 12 months or more. The ATO’s GST adjustment guidance sets out these conditions and excludes the Division 21 bad-debt adjustment for entities that account for GST on a cash basis.
  • Asset disposals: The GST treatment of a business asset disposal does not flow correctly into the BAS.
  • Private use: Business expenses or assets also have a private component.

Review focus: Compare adjustment accounts, credit notes, asset disposals, private-use entries and prior-period review notes with the current BAS. Escalate items that require technical judgement before finalising the activity statement.


3. Timing Mismatches Between Reporting Periods

Timing errors can move GST into the wrong BAS period even when the transaction itself contains the correct amount.


Where the risk appears:

  • GST attribution: Check whether the team applied the client’s cash or non-cash GST accounting basis correctly when determining the relevant BAS period.
  • Tax invoice timing: Confirm that the practice holds the required tax invoice when it claims an input tax credit on the BAS, particularly where invoice timing crosses a reporting period.
  • Period-end transactions: Review transactions close to the reporting-period boundary where payment, invoice issuance or tax-invoice availability could affect GST attribution.
  • Manual journals: Period-end entries affect GST balances without adequate supporting documentation.

Example: A supplier issues an invoice before quarter-end, but the practice receives the supporting tax invoice after the reporting period closes. The reviewer checks the client’s GST accounting basis, the applicable attribution period and whether the practice held the tax invoice when lodging the BAS before deciding which period should include the input tax credit.

✓ What to do

Include GST attribution in the BAS preparation and review support process. Check significant period-end transactions against the client's GST accounting basis, payment and invoice dates, tax-invoice availability and BAS period before escalating unexpected timing differences.


4. BAS Figures That Do Not Reconcile to the General Ledger

A BAS can balance internally while still failing a broader reconciliation with the accounting records. BAS reconciliation and compliance services should therefore trace reported figures back to the general ledger, control accounts and supporting schedules. Poor reconciliations often originate from underlying bookkeeping issues that were not addressed earlier in the reporting cycle.


Where the risk appears:

  • Bank accounts: GST-related transactions do not agree with reconciled bank activity.
  • Merchant facilities: Clearing balances or transaction fees remain unexplained.
  • GST-relevant loan entries: Check fees, charges and other loan-related transactions for the correct GST treatment rather than treating the loan balance itself as a GST item.
  • Manual journals: Entries bypass normal transaction workflows.
  • BAS labels: Reported figures do not trace cleanly to ledger reports.

Example: The BAS reports the expected GST amount, but the GST control account carries a recurring unexplained balance. The team clears the difference with a journal each quarter instead of investigating its source.

✓ What to do

Trace significant BAS labels back to the general ledger and supporting schedules. Investigate recurring differences rather than repeatedly correcting them.


5. PAYG Withholding, STP or Instalment Discrepancies

Payroll information can create BAS exceptions when STP reporting, payroll records and activity statement figures do not align. Payroll compliance and STP accuracy play an important role in reducing BAS review exceptions.


Where the risk appears:

  • STP reporting: Payroll totals differ from information reported through STP.
  • PAYG withholding: Withholding amounts do not reconcile with payroll records.
  • Payroll adjustments: Corrections or unusual pay runs create unexplained differences.
  • PAYG instalments: The instalment position no longer reflects the client’s expected business or investment income.

Example: A payroll correction changes PAYG withholding after the team prepares the BAS. The correction reaches the payroll records but does not flow into the figures used for BAS preparation.

What to do: Reconcile payroll, STP and PAYG withholding before final review. Check the client’s PAYG instalment calculation against expected liability and confirm whether the 2026–27 5% GDP adjustment applies to the method the client uses.

✓ What to do

Reconcile payroll, STP and PAYG withholding before final review. Check the client’s PAYG instalment calculation against expected liability and confirm whether the 2026–27 5% GDP adjustment applies to the method the client uses.


6. Fuel Tax Credit Errors Where Applicable

Fuel tax credits create an additional review point for eligible clients. Errors can arise from eligibility, fuel records, business use or rate application.


Where the risk appears:

  • Eligibility: The client’s activities do not meet the relevant requirements.
  • Fuel records: Quantities or supporting records do not adequately support the claim.
  • Business use: The calculation includes ineligible or private use.
  • Rates: The team applies an incorrect rate for the relevant period.

Review focus:

Treat fuel tax credits as an exception-based check. Confirm eligibility, fuel records, business use and the applicable rates before including the claim.

✓ What to do

Where the BAS includes a fuel tax credit claim, verify the supporting documentation, assess the calculation and confirm that the team applied the correct rate for the relevant claim period. Escalate any unusual or material claims for further review.


7. Unresolved Errors the Team Carries Forward from Earlier BAS Periods

A recurring unresolved BAS difference can indicate a control issue when the team repeatedly clears or carries it forward without identifying the underlying cause or determining the appropriate correction. A routine bookkeeping adjustment resolves a known transaction-level issue; a recurring unexplained difference requires investigation, ownership and escalation.


Where the risk appears:

  • Prior-period differences: Reconciliation items remain open.
  • Recurring journals: The same account requires repeated corrective entries.
  • Client queries: The practice continues requesting the same missing information.
  • Review notes: Previous exceptions remain unresolved.
  • Corrections: The team carries an earlier error forward instead of determining the appropriate correction.

Example: A GST control account has carried a small difference for three consecutive BAS periods. Each quarter, the preparation team posts a journal to clear the balance without identifying the original transaction causing the difference.

✓ What to do

Maintain an exception trail, assign ownership and determine the appropriate correction before the next BAS cycle. Where an earlier GST error requires correction, assess the applicable ATO correction rules rather than repeatedly clearing the difference.
What Year-End Workload Does to BAS Review Capacity

Year-end pressure can reduce the amount of time senior staff have available for BAS review. When senior staff receive a large group of BAS files together, they may spend more time locating missing information and resolving basic preparation issues. Many firms use outsourced accounting support to manage seasonal workload spikes without increasing permanent headcount.


That leaves less time for:

  • Trend analysis: Investigating unusual GST movements.
  • Reconciliation: Following differences across multiple accounts.
  • Exception review: Assessing unusual or technically complex transactions.
  • Client communication: Resolving questions before the lodgement deadline.
  • Professional judgement: Considering matters that require senior oversight.

The issue therefore concerns whether the practice has enough review capacity to assess BAS files after preparation, reconciliation and exception handling.

How Outsourced BAS Review Can Close These Checking Gaps

Outsourced BAS services can provide defined BAS preparation and review support within the firm’s existing preparation, reconciliation and checking workflow. Firms looking for broader support may also combine BAS processes with outsourced accounting and bookkeeping functions.


A controlled model can follow this sequence:

Preparation → Checking → Exception escalation → Internal professional review → Lodgement


The external team can support tasks such as:

  • Reconciliations: Compare BAS figures with ledger and supporting records.
  • Exception identification: Flag unusual GST treatment, missing documents and unexplained differences.
  • Adjustment checks: Identify potential BAS adjustments for internal assessment.
  • Payroll reconciliation: Compare payroll, STP and PAYG withholding information.
  • Prior-period review: Highlight recurring unresolved items.
  • Workpaper preparation: Organise supporting schedules and review notes for the firm’s team.

The handoff should give the firm a clear set of exceptions, reconciliations and supporting schedules to assess during professional review.

What Firms Should Check Before Outsourcing BAS Review & Finalisation

Outsourcing BAS review & finalisation requires more than checking whether a provider can process BAS files. Firms should assess the operating model itself.

Professional Responsibility and Supervision

The practice should establish:

  • Defined responsibilities: Document which tasks the provider performs and which decisions remain with the practice.
  • Escalation rules: Identify matters that require registered practitioner involvement.
  • Review controls: Set expectations for sampling, exception handling and feedback.
  • Auditability: Maintain a clear record of preparation, review comments and changes.

The practice should define where BAS preparation and review support ends and where its own professional review and decision-making begin. Before engaging a provider, the firm should also confirm whether the provider’s activities constitute a BAS service that requires TPB registration or fall within an applicable exemption. The TPB’s guidance on supervision, competency and quality management provides expectations for supervision arrangements, workflow oversight, review processes, file management, escalation pathways and quality controls. The TPB’s guidance on outsourcing and offshoring focuses on the additional considerations that arise when engaging external providers, including competency, supervision, client disclosure obligations and compliance with the Code of Professional Conduct.


Data Security and Offshore Processing

If the arrangement involves offshore processing, firms should assess:

  • Access controls: Limit system and file access according to role.
  • Data transfer: Establish secure methods for sharing client information.
  • Contractual controls: Set enforceable requirements for information handling, subcontracting and breach notification.
  • Audit trails: Maintain visibility over file access and changes.
  • Incident procedures: Confirm how the provider handles security incidents.

The OAIC’s APP 8 guidance on cross-border disclosure requires APP entities to take reasonable steps before disclosing personal information to overseas recipients and can hold the Australian entity accountable for certain overseas handling.

Client Disclosure and Engagement Terms

The firm should also confirm:
  • Client information: Confirm whether the arrangement requires client permission to disclose information to an external provider and whether any privacy or cross-border disclosure obligations apply.
  • Engagement terms: Address third-party and offshore processing where relevant.
  • Client communication: Define who requests outstanding information and manages client communication.
  • Professional decisions: Keep technical judgement and engagement decisions within the firm’s defined responsibility structure.
 

Commercial Fit

The commercial model should support the firm’s existing workflow without creating another layer of review or administration. Firms should assess:

  • Defined scope: Confirm exactly which preparation, reconciliation and checking activities the provider performs and where the firm’s review begins.
  • Workflow integration: Check whether the provider can work within the firm’s existing systems, documentation standards and handoff process.
  • Review burden: Assess whether external checking produces clear exceptions and review-ready files rather than creating additional reconstruction work.
  • Service structure: Confirm how the arrangement handles recurring work, peak-period requirements, escalation and changes in workload.
  • Commercial terms: Examine pricing, minimum commitments and scope boundaries against the firm’s intended use of the service.

When Outsourcing Does Not Solve the Problem

BAS preparation and review support can strengthen a defined workflow, but the practice should address underlying control gaps before adding external support. Review the process first when:
  • Client records: Address recurring gaps where incomplete records delay preparation and exception review.
  • GST coding: Standardise coding rules where bookkeeping and BAS services rely on workflows that repeatedly apply inconsistent GST treatment.
  • Exception ownership: Assign responsibility for unresolved items so issues do not remain open across BAS cycles.
  • Escalation criteria: Define the points that require senior or registered practitioner review.
  • Professional review: Establish the firm’s review responsibilities before assigning preparation or checking activities externally.

When Outsourced BAS Review Makes Operational Sense

The model may fit when the practice has a recurring, clearly defined group of preparation or checking activities that compete with higher-value review work.


Typical indicators include:

  • Seasonal workload spikes: BAS volumes increase faster than available review capacity.
  • Senior bottlenecks: Experienced accountants spend review time on routine reconciliations.
  • Recurring exceptions: Teams repeatedly investigate the same preparation issues.
  • Backlog risk: Completed BAS files wait for review close to lodgement deadlines.

The practical test is whether the firm can isolate repeatable activities without weakening its internal review controls.

Looking to strengthen reconciliation, exception identification, and year-end BAS review processes? Talk to our team about a tailored support model.

Return to the Year-End BAS Review Question

A year-end BAS review should answer more than whether the activity statement balances. It should confirm correct GST treatment, trace significant figures to supporting records, resolve unexplained differences and align payroll and PAYG information.


When earlier exceptions remain unresolved, the issue may sit within the workflow rather than a single BAS. The core question is straightforward: can the practice identify and escalate exceptions before professional review and lodgement? Where the answer remains unclear, strengthen the process before the next BAS cycle.

How Unison Globus Australia Supports BAS Review and Reconciliation

Unison Globus Australia provides BAS Review & Lodgement Support for Australian Businesses, covering defined preparation, reconciliation, exception identification and review support activities, with the firm’s professional team applying the relevant judgement and approval controls.

  • BAS preparation: Prepare activity statement figures and supporting workpapers.
  • GST reconciliation: Compare reported figures with accounting records.
  • Exception identification: Flag unusual treatment, missing evidence and unexplained differences.
  • Review support: Organise schedules and review points for the firm’s professional team.
  • PAYG and prior-period checks: Reconcile payroll information and recurring exceptions.

The firm defines the provider’s role and applies the appropriate professional judgement, review, supervision and engagement controls for the arrangement. While Australian firms focus on BAS, GST and ATO compliance obligations, accounting firms globally face similar review-capacity challenges during peak workloads and reporting periods. 

Compliance Review Challenges Extend Beyond Australia

While BAS compliance reviews are unique to Australia’s GST and ATO reporting framework, the underlying challenge is often the same across accounting firms globally: maintaining review quality during periods of increasing workload. Whether firms are managing BAS reviews, year-end accounts, tax compliance, or reconciliation processes, capacity constraints can place additional pressure on senior review teams.


For example, many firms in the United States use outsourced bookkeeping and accounting support for CPA firms to improve workflow efficiency, strengthen reconciliations, and manage peak workload periods without increasing permanent headcount.


Similarly, accounting practices in the United Kingdom often rely on year-end accounts and bookkeeping support for UK accounting firms to maintain reporting accuracy and meet compliance deadlines during busy reporting cycles.


Canadian accounting firms face comparable challenges around reconciliations, financial reporting, and resource planning, leading many practices to adopt accounting support for Canadian firms as part of their broader operational strategy.


Regardless of jurisdiction, the common objective remains the same: ensuring routine preparation and reconciliation activities are completed efficiently so senior professionals can focus on review, advisory, and compliance oversight.
Frequently Asked Questions

Focus on GST classification, unsupported claims, adjustments, timing differences, ledger reconciliation, PAYG discrepancies, fuel tax credits where relevant and unresolved prior-period errors.
A year-end review can expose recurring exceptions, weak reconciliation points and unresolved prior-period issues before they enter another BAS cycle.
Outsourced BAS services can support preparation, reconciliation, exception identification, workpaper preparation and defined checking activities before the firm’s professional review.
Yes, where the arrangement meets applicable professional, confidentiality, supervision and control requirements. Firms should also confirm whether the provider must hold TPB registration or qualifies for an applicable exemption.
Review the provider’s Australian tax capability, TPB registration or applicable exemption, supervision model, data-security controls, access arrangements, escalation process, audit trails and client disclosure requirements.
It can make sense when recurring BAS volumes create a gap between preparation capacity and senior review capacity, particularly during concentrated workload periods.
A BAS Compliance Review typically involves verifying GST classifications, reviewing PAYG withholding and instalment amounts, reconciling BAS figures to the general ledger, checking supporting documentation, reviewing adjustments, and identifying unresolved exceptions before lodgement. For Australian accounting firms, the objective is to improve accuracy, strengthen compliance controls, and ensure BAS figures align with underlying business records and ATO requirements.
The frequency depends on client size, transaction volume, and reporting obligations. However, many Australian accounting firms perform a BAS Compliance Review before each BAS lodgement cycle, with additional year-end reviews for higher-risk or complex clients. Regular reviews can help identify recurring GST, PAYG, reconciliation, and documentation issues before they accumulate across multiple reporting periods.
Yes. Outsourced BAS support can help accounting firms manage preparation, reconciliations, workpaper preparation, exception identification, and documentation checks during peak workload periods. By reducing time spent on routine review activities, firms can allocate more senior resources to technical review, client advisory, compliance oversight, and lodgement approvals while maintaining professional control over the engagement.
Categories
Accounting Home Aus

Why Australian Accounting Firms Should Outsource Tax Preparation After EOFY?

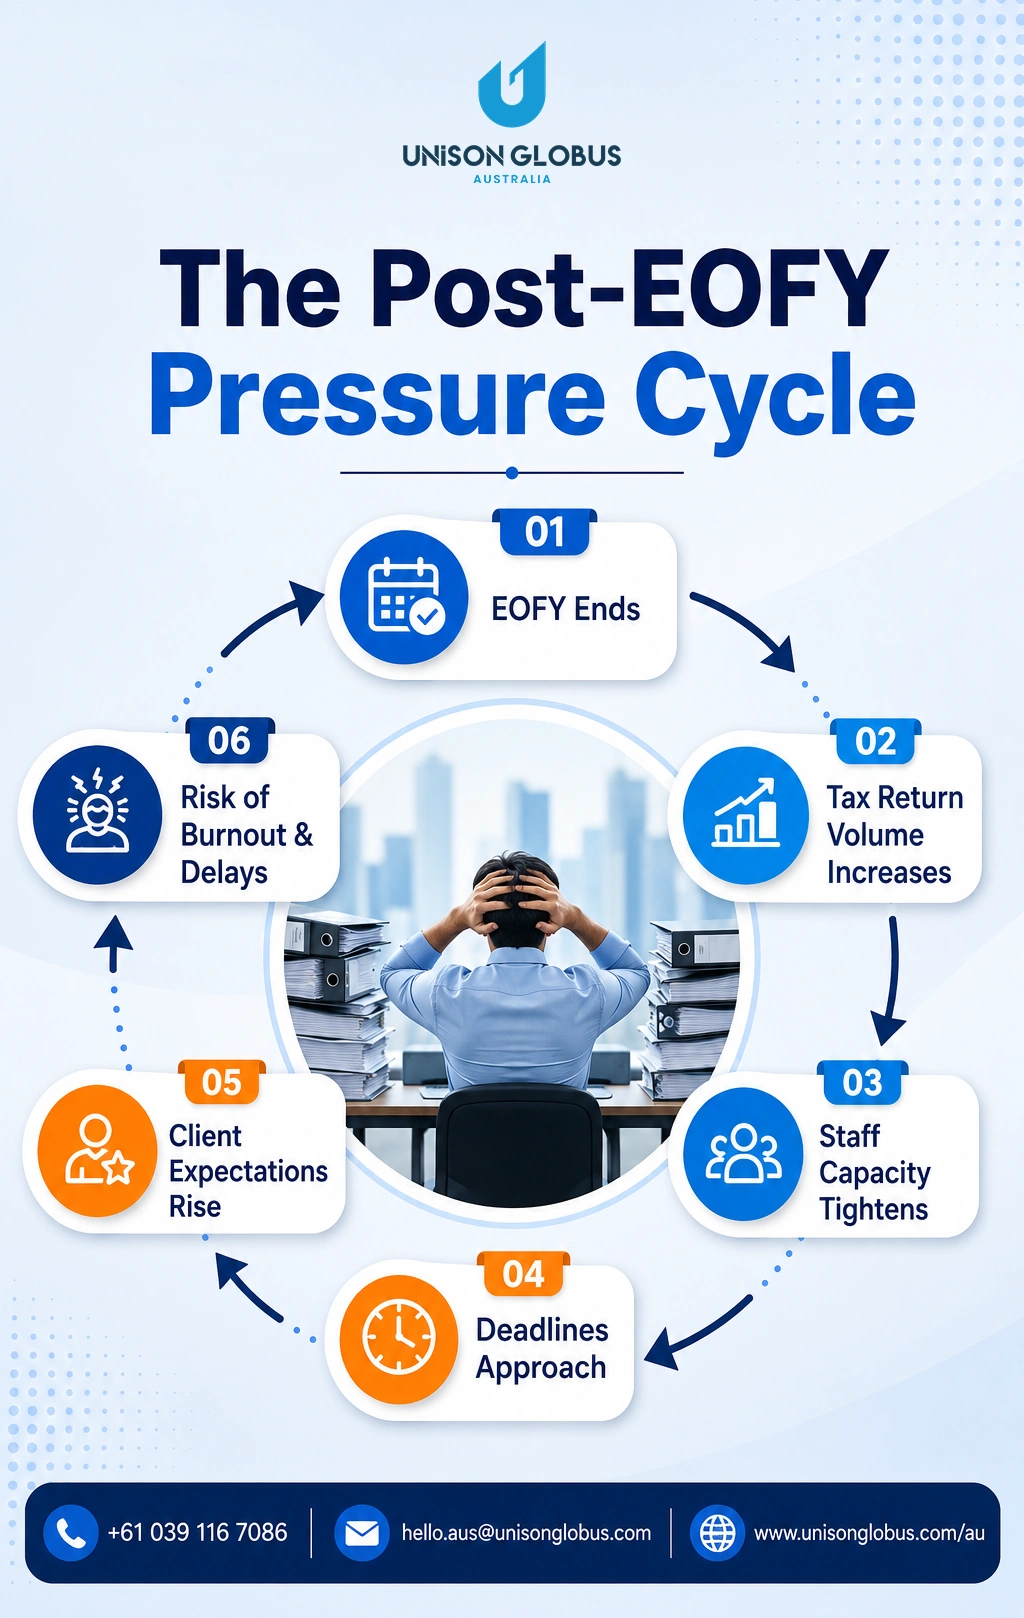
For many Australian accounting firms 30 June doesn’t bring a sense of relief, it simply marks the start of a new wave of work. The end of financial year deadline may be over, but tax returns still need to be prepared, clients have questions, compliance checks continue, and lodgement deadlines are just around the corner. Before long, the workload starts piling up again, leaving teams trying to keep up without compromising on quality.

This is one of the biggest reasons firms are looking into why outsource tax preparation after EOFY in Australia. What was once seen as a temporary fix for busy periods has evolved into a smarter way of working. By outsourcing tax preparation, firms can handle growing workloads more confidently, reduce pressure on internal staff, maintain consistent service levels, and give their accountants more time to focus on valuable client conversations and business growth.

The Reality of Post-EOFY Workloads

The period following EOFY is often one of the busiest times for accounting practices.

Teams are simultaneously managing:

  • Individual and business tax returns
  • Financial statement preparation
  • BAS and compliance obligations
  • Client queries and document collection
  • Advisory engagements and business planning discussions

For many firms, the challenge isn’t expertise it’s capacity.


When workloads surge, even high-performing teams can experience delays, overtime, and mounting pressure. This is where effective post EOFY tax workload management becomes critical.

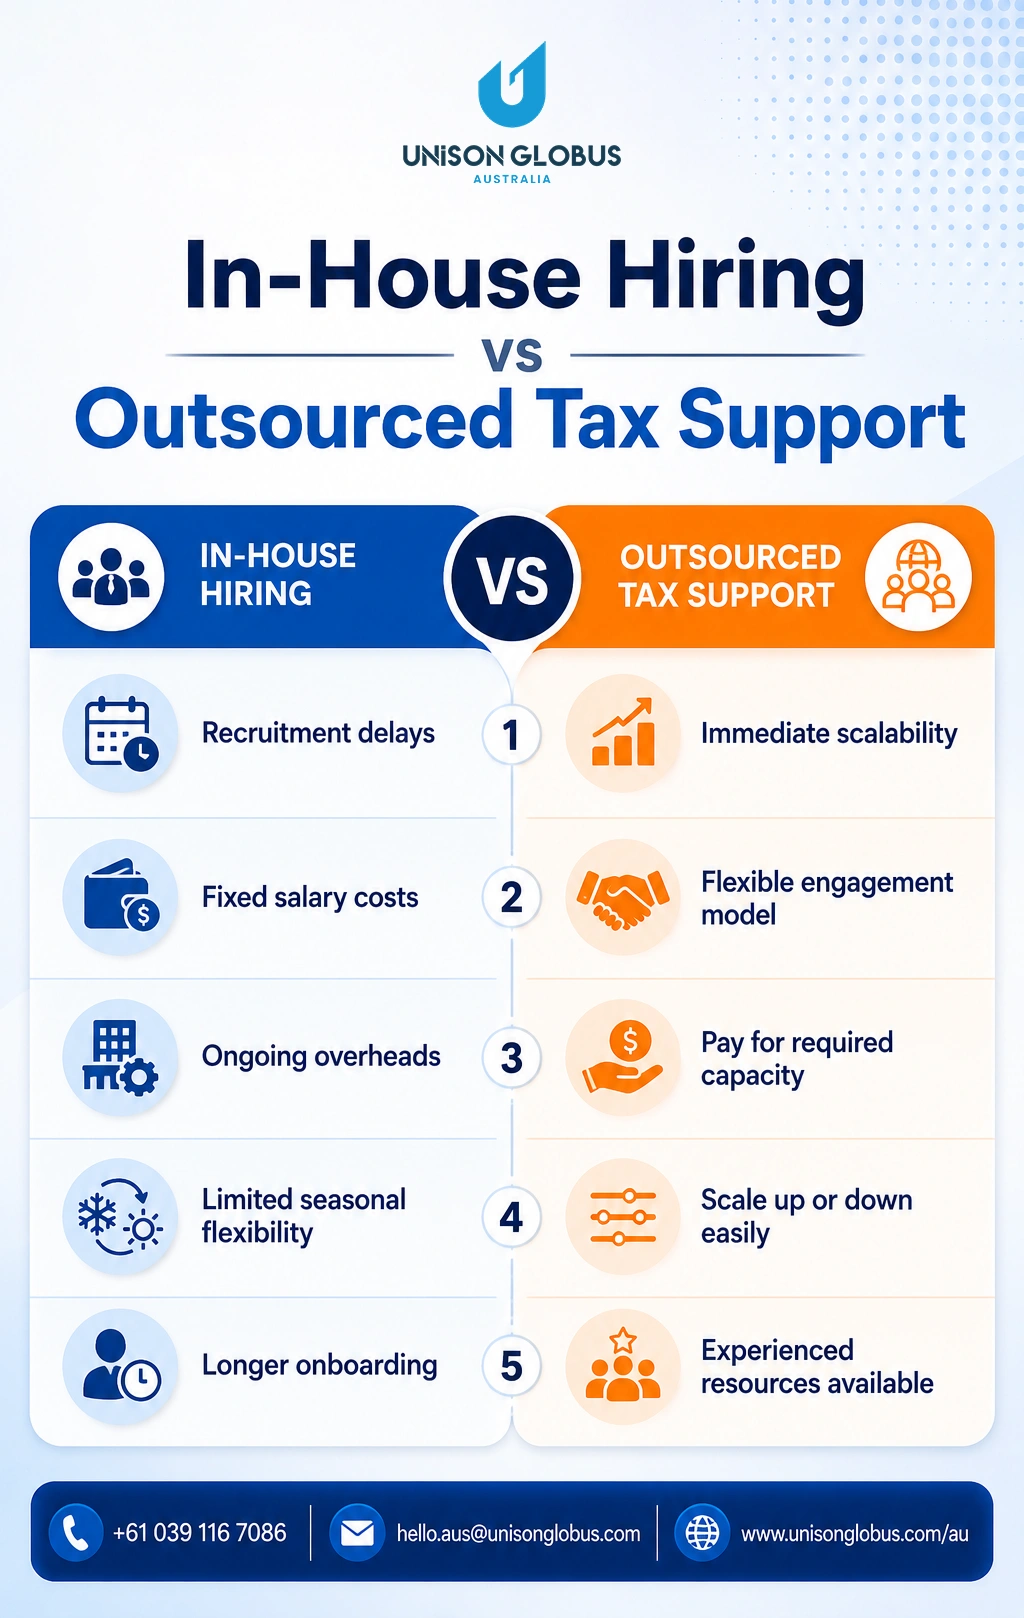
When workloads increase, the first instinct is often to hire.

Why Hiring More Staff Isn't Always the Best Solution?

However, recruiting experienced tax professionals in Australia has become increasingly difficult. Between rising salaries, lengthy hiring processes, onboarding costs, and ongoing overheads, expanding an internal team isn’t always practical for seasonal demand.


The challenge is simple, tax season spikes are temporary, but employment costs are permanent.


As a result, many firms are turning to accounting outsourcing for CPA firms Australia as a more flexible alternative.


Instead of adding fixed costs, firms can access skilled tax professionals only when additional support is required.

What Tax Preparation Outsourcing Actually Includes?

Many firm owners still assume outsourcing means handing over complete control. In reality, outsourcing functions as an extension of your existing team.

Common outsourced tax support includes:

  • Individual & Business tax return preparation
  • Workpaper preparation
  • Financial statement support
  • Reconciliations and data processing
  • Review-ready tax files
  • Compliance documentation support
The accounting firm retains full client ownership, oversight, and final review authority. This approach allows firms to scale efficiently without sacrificing quality or control.

Is your team still working through the post-EOFY backlog?

Unison Globus helps Australian accounting firms handle the tax season surge without the overhead of permanent hires.

7 Reasons Australian Accounting Firms Are Outsourcing Tax Preparation After EOFY

1. Instantly Increase Capacity During Peak Tax Season

One of the biggest advantages of CA firms outsourcing tax preparation is immediate access to additional resources.


Rather than overloading internal teams, firms can distribute work more effectively and handle larger return volumes with confidence.

2. Meet Deadlines More Consistently

Tax deadlines don’t move, regardless of staff availability. By leveraging offshore tax preparation services Australia, firms can reduce delays and maintain smoother workflows during high-demand periods.

3. Improve Profitability Without Increasing Fixed Costs

Permanent hiring comes with recruitment fees, salaries, benefits, and training expenses. Outsourcing provides a scalable model where support can be increased or reduced based on workload demands.


This is one of the key benefits of outsourcing tax preparation for CPA firms looking to protect margins.

4. Free Senior Staff for Higher-Value Work

When experienced accountants spend excessive time preparing returns, advisory opportunities often take a back seat.


Outsourcing routine tax preparation enables senior team members to focus on:

  • Strategic client conversations
  • Tax planning
  • Business advisory services
  • Practice growth initiatives

5. Reduce Staff Burnout

Extended overtime and seasonal pressure can impact morale and retention.


Firms that successfully reduce tax season workload outsourcing accounting tasks often create healthier, more sustainable working environments.

6. Maintain Consistent Service Quality

Quality can suffer when teams are stretched. Structured outsourcing processes help firms maintain consistency, accuracy, and review readiness even during peak periods.

7. Create a More Scalable Growth Model

Growth shouldn’t be limited by headcount.


Many firms using accounting firms outsourcing services Australia are able to onboard more clients without immediately expanding internal teams. The result is a more agile and scalable operating model.

Common Concerns About Outsourcing and the Reality

For many firms, the hesitation around outsourcing isn’t about capability, it’s about trust. Here are some of the most common concerns and what they look like in practice.

1. What About Data Security?

Handing over sensitive financial information can feel like a big step. That’s why established outsourcing partners rely on secure systems, confidentiality agreements, and controlled access protocols to safeguard client data and maintain privacy throughout the engagement.

2. Will Quality Be Maintained?

Quality doesn’t disappear when work is outsourced, it depends on the process behind it. Your firm continues to review and approve the final output, while the outsourced team follows your workflows and standards to deliver consistent, accurate work.

3. Will We Lose Control of Client Relationships?

Not at all. Outsourcing is designed to support your team, not replace it. Your clients still communicate with your firm, while the outsourced professionals handle the preparation work behind the scenes. The result is often better responsiveness, faster output timelines, and more time for meaningful client conversations.

4. Can Outsourcing Support Compliance?

Yes. In fact, compliance is one of the main reasons many firms turn to Australian tax compliance outsourcing. During busy periods, when deadlines are tight and workloads keep growing, it’s easy for small mistakes to slip through. Working with an experienced outsourcing partner gives your team extra support to handle the volume while following Australian tax requirements and maintaining the accuracy and consistency your clients expect.

Signs Your Firm May Need Outsourced Tax Support

Ask yourself:

✓  Is your team regularly working overtime after EOFY?

✓  Are tax return backlogs becoming difficult to manage?

✓  Are advisory projects being delayed because compliance work is taking priority?

✓  Do staff capacity issues arise every tax season?

✓  Are growth plans being constrained by resource limitations?

If you answered “yes” to several of these questions, outsourcing may provide the flexibility your firm needs.

This is increasingly becoming part of how accounting firms manage post EOFY workload without compromising client service.

Choosing the Right Outsourcing Partner

Not all providers offer the same level of expertise.

When evaluating a partner, look for:

  • Experience supporting Australian accounting firms
  • Strong understanding of Australian taxation processes
  • Scalable resource availability
  • Robust data security practices
  • Clear communication channels
  • Proven quality assurance procedures

The most successful outsourcing relationships feel less like vendor arrangements and more like an extension of the firm’s internal team.


Whether you’re considering offshore tax preparation services for Australian firms or broader accounting support, selecting the right partner is essential.

Conclusion

The post-EOFY period places significant pressure on accounting firms, but capacity challenges don’t have to limit growth. As tax return volumes increase and deadlines tighten, firms need solutions that provide flexibility without increasing permanent overheads. That’s why more firms are choosing to outsource tax preparation in Australia and leverage strategic support models that improve efficiency, protect staff wellbeing, and maintain service quality.


The firms that thrive after EOFY aren’t necessarily the ones with the largest teams they’re the ones with the smartest capacity strategies. And for most, that thinking doesn’t stop at tax. Once seasonal demand is managed effectively, many firm owners begin evaluating where else operational efficiency can be gained.

Tax preparation is often the starting point, but bookkeeping tends to follow. It is one of the more time-intensive back-office functions and, when handled internally, can limit the bandwidth available for higher-value client work. Addressing that through structured outsourcing allows firms to operate more consistently, improve turnaround times, and position their teams for advisory-focused growth. The same logic applies beyond Australia, UK firms navigating similar capacity pressures are increasingly turning to digital bookkeeping solutions to achieve the same outcome. For the firms that have made that shift, outsourcing is no longer a contingency measure it is simply how a well-structured practice is run. 


EOFY demands more than longer hours, it demands the right support.
Unison Globus Australia helps accounting firms scale tax preparation without compromising quality or deadlines.

Looking for Reliable Support This EOFY?

Discover how Unison Globus Australia can simplify your EOFY tax preparation Australia workflow with expert support that keeps your team ahead.

FAQ’s

Many firms choose to outsource tax preparation Australia after EOFY because tax return volumes increase significantly during this period. Outsourcing helps firms manage workload peaks, meet lodgement deadlines, reduce staff pressure, and maintain service quality without hiring additional full-time employees.

Yes. Reputable providers offering Australian tax compliance outsourcing implement strict data security measures, confidentiality agreements, controlled access protocols, and secure technology environments. Firms also retain oversight and final review authority over all tax work.

Some of the key benefits of outsourcing tax preparation for CPA firms include increased capacity during peak seasons, reduced operational costs, faster delivery timelines, improved staff productivity, lower burnout risk, and the ability to focus on higher-value advisory services.

Categories
Home Aus Payroll

ATO BAS Compliance Checklist for June 2026: Q4 Lodgement Guide for Australian Accounting Firms

The June quarter has a way of revealing everything that has been quietly building throughout the financial year.

A GST (Goods and Services Tax) coding error that slipped through in October, payroll figures that no longer reconcile cleanly with STP record, missing supplier invoices, unreviewed transactions sitting in suspense accounts.

For Australian accounting firms, the June BAS is rarely just another quarterly lodgement.

It marks the final BAS reporting period of the financial year and serves as a critical checkpoint before EOFY reporting, tax return preparation, and compliance reviews begin in earnest.

That is precisely why a structured ATO BAS compliance checklist 2026 is essential. Many firms rely on BAS Preparation & Lodgement Services to streamline compliance and reduce manual effort during peak BAS cycles.

The June 2026 BAS presents an opportunity not only to meet compliance obligations but also to identify risks early, improve reporting accuracy, and set clients up for a smoother EOFY process.

Whether you’re reviewing a handful of clients or managing a large portfolio, this BAS checklist for June quarter 2026 Australia can help streamline your review process and reduce year-end surprises.

Why the June BAS Matters More Than Any Other Quarter?

Every BAS matters, but the June quarter carries additional significance because it closes out the financial year.


The figures reported in Q4 form an important foundation for year-end financial statements and tax return preparation. If errors remain unaddressed at this stage, they can create a chain reaction that affects multiple compliance processes.


A seemingly minor issue can quickly snowball into:


  • GST reporting discrepancies
  • Payroll reconciliation challenges
  • Incorrect year-end balances
  • Delayed tax return preparation

For accounting firms managing multiple client engagements, a rushed review process can quickly become costly.


That’s why every firm should approach June with a structured BAS lodgement checklist June quarter rather than treating it as a routine compliance task. Similar compliance challenges exist globally. For example, firms managing VAT return compliance in the UK and sales tax filings in the US also rely on structured checklists and reconciliation processes to reduce reporting errors and ensure accuracy.

ATO BAS Compliance Checklist 2026 for a Smooth Q4 BAS Lodgement Season

1. Reconcile Every Account Before BAS Review

Before reviewing GST or PAYG amounts, ensure the underlying data is accurate.


Review and reconcile:


✓ Bank accounts

✓ Credit card accounts

✓ Loan accounts

✓ Clearing accounts

✓ Merchant facility transactions

✓ Unallocated transactions


One of the most common causes of BAS errors is incomplete reconciliations. If transactions haven’t been properly matched and reviewed, BAS figures may not accurately reflect the client’s financial position.

2. GST Coding Errors Are Easier to Fix Now Than During EOFY

GST coding issues remain a common source of BAS review adjustments for many businesses.


Pay close attention to:


  • GST-free supplies
  • Input-taxed transactions
  • Export income
  • Capital asset purchases
  • Motor vehicle expenses
  • Entertainment costs
  • Mixed-use expenses

The June quarter is an ideal time to identify and correct coding issues before they carry over into EOFY reporting.

3. Incomplete Revenue Reporting Can Create Significant BAS Risks

Revenue recognition has become increasingly complex as businesses adopt multiple payment channels and digital sales platforms.


When reviewing BAS figures, ensure all revenue sources have been captured.


This step is particularly important for meeting BAS lodgement requirements ATO expects businesses to satisfy.


Review:


  • Outstanding invoices
  • Cash sales
  • Online payments
  • Subscription income
  • Marketplace sales
  • Credit notes and refunds

A comprehensive review helps ensure BAS figures accurately reflect business activity throughout the quarter.

4. Don’t Leave GST Credits on the Table Before Lodgement

GST credits can only be claimed correctly when supporting documentation and transaction records are in order.

Before lodging:


✓ Confirm supplier invoices have been entered

✓ Verify GST credits are supported by documentation

✓ Remove duplicate transactions

✓ Review large purchases

✓ Follow up on missing invoices

The ATO requires businesses to maintain adequate records supporting BAS figures, including tax invoices, payroll records, and transaction documentation. Missing or incomplete records can create compliance risks even when reported amounts are otherwise correct.

5. Payroll and STP Must Match Before You Lodge

Payroll discrepancies often remain hidden until EOFY reviews begin.


To avoid complications, compare:


  • Payroll reports
  • BAS wage figures
  • STP data
  • Employee reimbursement records
  • Director remuneration entries

This forms a critical part of any BAS review checklist GST PAYG reconciliation process.

6. PAYG Errors Often Surface at the Worst Possible Time

PAYG withholding is another area where small inaccuracies can create larger compliance concerns.


Review:


✓ Employee withholding amounts

✓ Contractor withholding requirements

✓ Tax file declaration updates

✓ Payroll software calculations

✓ Reported withholding balances

7. Review PAYG Instalments Before They Impact Client Cash Flow

The June quarter provides an excellent opportunity to evaluate whether PAYG instalments still reflect the client’s financial position.


Consider:


  • Current business performance
  • Profitability trends
  • Cash flow pressures
  • Potential variation opportunities

Proactively reviewing instalments can help align tax payments more closely with current business performance.

June BAS Pressure Building Up? Scale Support Before EOFY Hits.

From BAS preparation and review to finalisation and lodgement, the right support can ease pressure without compromising quality. Unison Globus Australia helps accounting firms manage compliance workloads efficiently during peak BAS and EOFY periods.

8. EOFY Adjustments That Deserve a Second Look

The June BAS often includes transactions that require additional scrutiny because they directly affect year-end reporting.


Pay particular attention to:


  • Asset acquisitions
  • Asset disposals
  • Inventory adjustments
  • Bad debt write-offs
  • Director loan accounts
  • Business-use percentage adjustments

9. Correct BAS Errors Before They Become Year-End Problems

The final quarter of the year is an ideal time to identify and address GST adjustments.


Review whether any of the following apply:


✓ Private-use adjustments

✓ Change-in-use adjustments

✓ Fuel tax credit adjustments

✓ Prior BAS corrections

✓ Adjustment events affecting GST calculations

10. One Final Review Can Prevent Weeks of Rework

Before submitting the BAS, conduct one final quality review.


This is where Outsourced BAS Review & Finalisation Services help firms improve accuracy, reduce EOFY rework, and streamline compliance workflows.


Consider:


✓ Comparing figures against previous quarters

✓ Investigating unusual fluctuations

✓ Reviewing GST refund positions

✓ Obtaining client approval

✓ Retaining supporting documentation

✓ Documenting significant assumptions or adjustments


A thorough review remains one of the most effective ways to identify errors before lodgement and reduce EOFY rework.

Even globally, accounting firms face similar risks across GST, VAT, and sales tax compliance, where missing transactions, incorrect tax treatments, and reconciliation gaps can impact reporting accuracy and deadlines.

Five BAS Compliance Risks Hidden Inside the June Quarter

While every client is different, several recurring issues continue to surface across industries.

  • Missing Digital Revenue Streams

With more businesses operating online, income can originate from multiple sources beyond traditional invoicing systems. Similar reporting gaps are also observed in GST/HST filing requirements in Canada, where businesses dealing with multiple digital income streams often face reconciliation challenges.


Platforms such as payment gateways, subscription services, and online marketplaces can create reporting gaps if not reviewed carefully.


  • Payroll and STP Mismatches

Differences between payroll systems, STP submissions, and BAS figures remain a common EOFY issue.


  • Incorrect GST Treatment of Software Subscriptions

International software purchases often create GST treatment complexities, particularly where overseas software providers and digital services are involved.


  • Unsupported GST Claims

GST credits claimed without valid documentation continue to present compliance risks.


  • Historical Errors That Were Never Corrected

The June BAS offers an opportunity to identify and resolve historical issues before they affect year-end reporting.

What a Good BAS Review Can Reveal?

The most successful firms recognise that BAS preparation is about far more than compliance.


Every BAS review contains valuable insights into a client’s operations.


A structured Q4 BAS checklist Australia process can help firms:


  • Improve bookkeeping processes
  • Identify cash flow concerns
  • Strengthen payroll controls
  • Enhance reporting accuracy
  • Support business planning
  • Prepare clients for tax season

This is also where Outsourced BAS Review & Finalisation Services can help firms maintain consistency and capacity during peak periods.

Final Thoughts:

By the time the June BAS deadline arrives, most accounting firms are already preparing for EOFY. That’s why this lodgement deserves careful attention. 


A well-structured BAS checklist Australia process provides clarity during one of the busiest times of the year. Rather than spending valuable time correcting avoidable errors, your team can focus on accurate lodgements, efficient workflows, and delivering better client outcomes. Many firms also align BAS processes with Accounting & Bookkeeping Services to maintain accurate financial records and simplify compliance reporting throughout the year.


Preparing for the June BAS Rush?

When deadlines tighten and workloads increase, additional support can make all the difference. With dedicated Accounting & Bookkeeping professionals, Unison Globus Australia supports firms with BAS Preparation & Lodgement Services, review, finalisation, and EOFY compliance assistance.

BAS Errors Impacting Compliance? Fix It with the Right Support.

Accurate BAS reporting and GST reconciliation are critical to avoiding ATO penalties. Unison Globus Australia ensures your processes are streamlined, error-free, and managed by experienced professionals.

FAQ

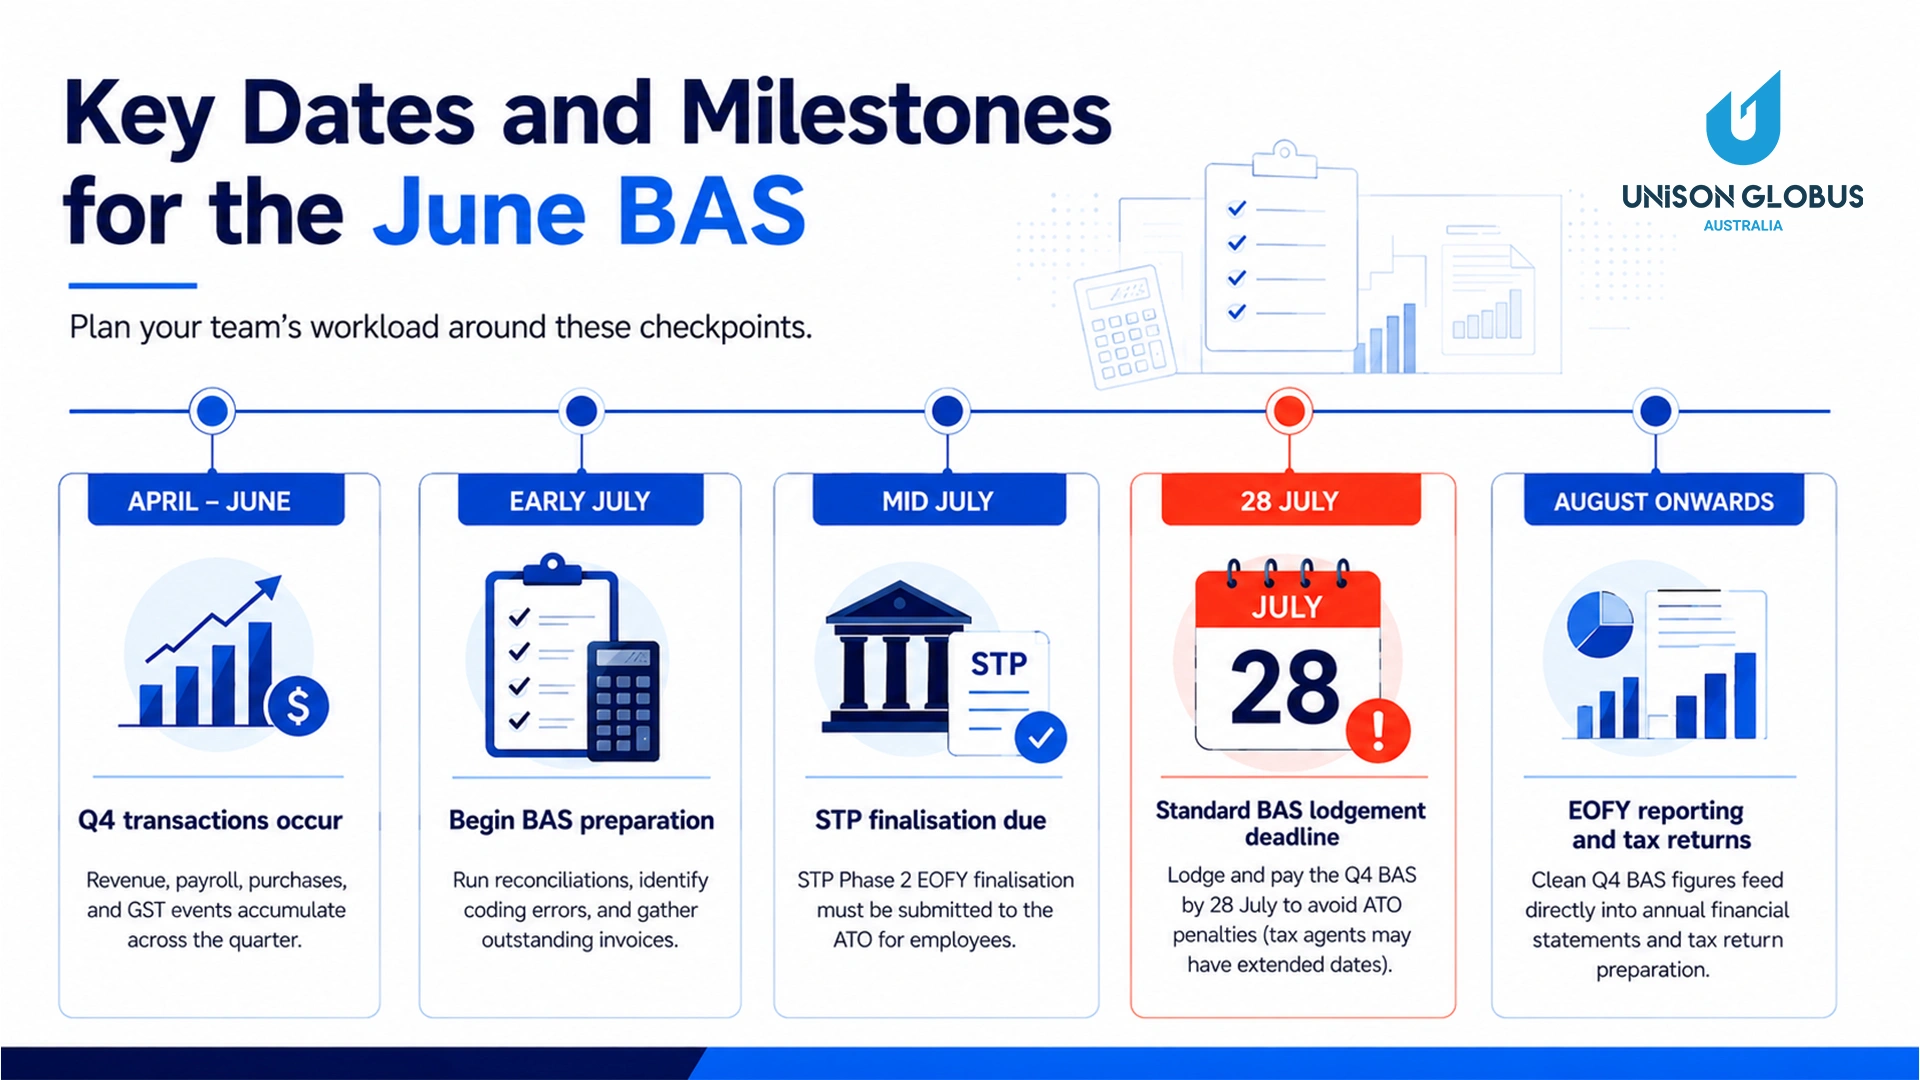
Yes. STP submissions must be finalised by mid-July. Payroll figures in the BAS must match STP data resolve any discrepancies before lodging.

Yes, if the net GST error is $10,000 or less. Larger errors or fraud-related corrections require a separate amendment request to the ATO.

Late lodgement attracts an FTL (Failure to Lodge) penalty ($313 per 28-day period, up to five units). Underpayments incur interest charges. Voluntary disclosure before an audit generally reduces penalties.