Categories
Bookkeeping

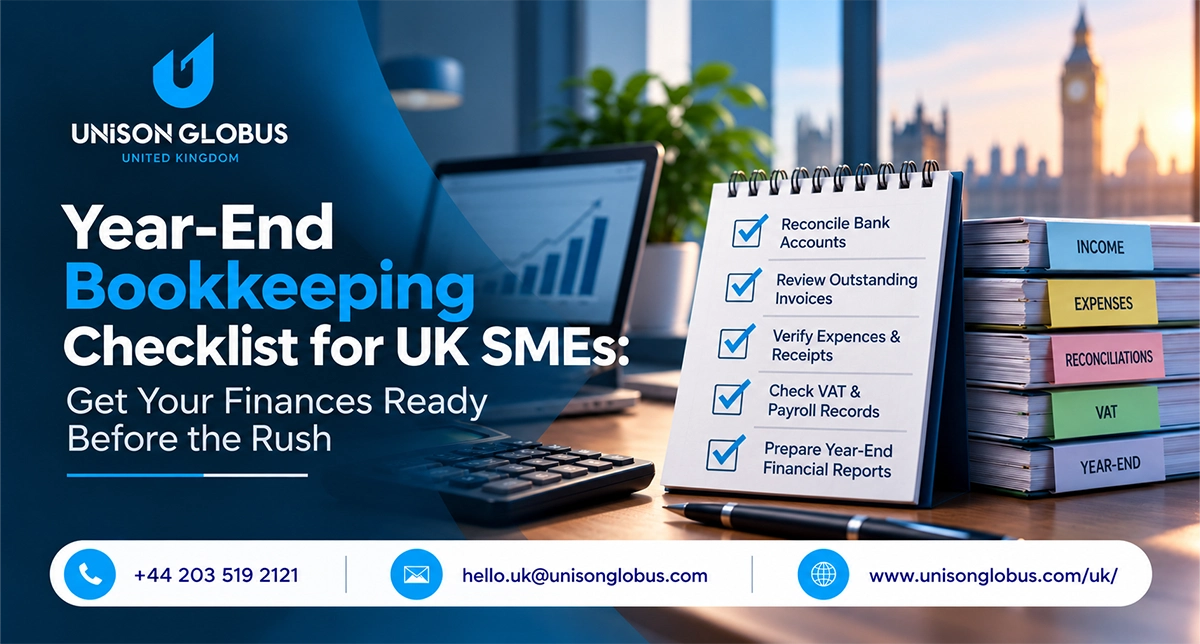
Year-End Bookkeeping Checklist for UK SMEs: Get Your Finances Ready Before the Rush

A business can have well-maintained books, up-to-date reconciliations and reliable accounting software, yet still need to resolve important questions at year-end. A supplier invoice may arrive after the reporting date, a customer balance may need reviewing, or a payment made during the year may cover costs relating to the next accounting period.

These are not necessarily signs of poor financial management. They reflect the work involved in establishing an accurate year-end position, where transactions, supporting documents and accounting adjustments must be reviewed together before the accounts are finalised.

For UK SMEs, a structured year-end bookkeeping checklist helps bring these checks into one process. It is also a useful framework for accountants and providers of outsourced bookkeeping services UK firms rely on to support year-end compliance and reporting requirements.

Key Takeaways
  • Reconcile bank accounts, payment platforms and outstanding balances before year-end.
  • Review VAT, payroll, fixed assets, loans and stock where applicable.
  • Identify potential accruals, prepayments and other adjustments for review by the accountant.
  • Organise supporting documents and list missing information or unresolved queries.
  • Maintain records throughout the year to make year-end preparation more manageable.
  • Check applicable record-retention requirements and statutory filing deadlines.

Year-End Bookkeeping Checklist for UK SMEs

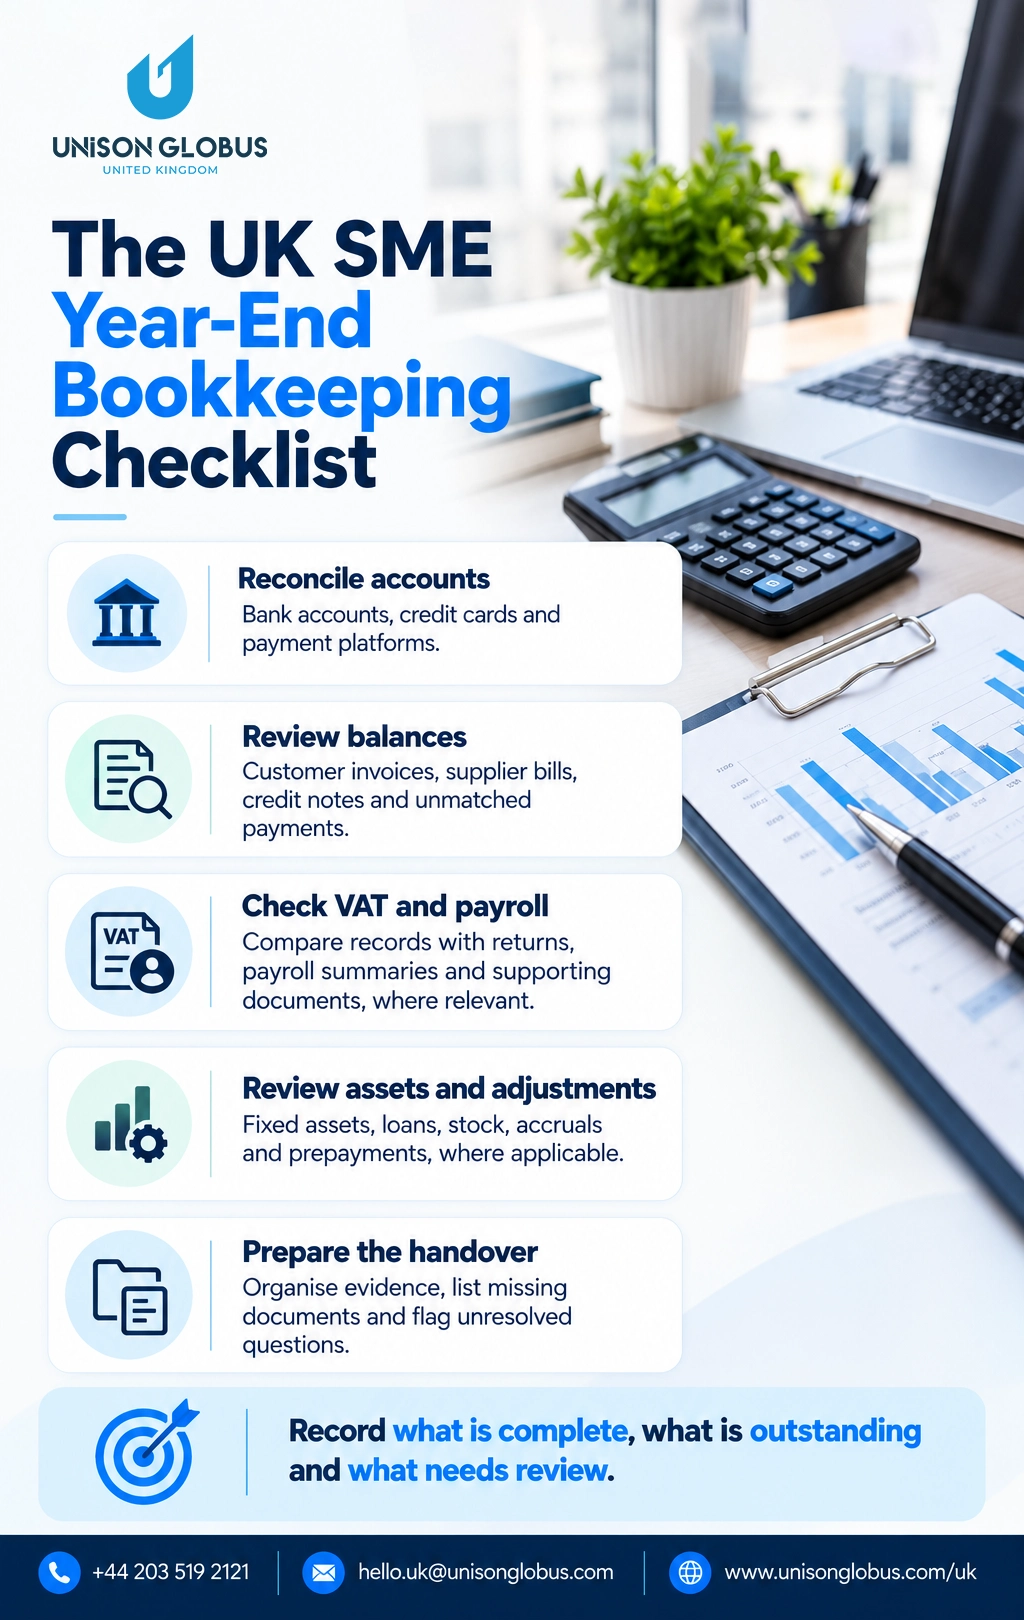
This year-end accounting checklist helps UK SMEs review their records systematically, identify missing evidence and flag balances that may need further investigation before the accounts are finalised.

1. Reconcile Bank Accounts, Credit Cards and Payment Platforms

Start by checking that the balances in your accounting software agree with the relevant statements at the year-end date. This includes business bank accounts, credit cards, loan accounts where applicable, and payment platforms used to collect customer payments.


Accounting software and bank feeds can save time, but they do not guarantee that every transaction has been recorded correctly. Duplicate entries, missing bank charges, transfers posted as income, unmatched payments and transactions assigned to the wrong account can all affect the figures.


Investigate differences rather than adjusting a balance simply to make the numbers agree. Check whether each difference is a genuine timing issue, an entry error or an unidentified transaction. Record the explanation and supporting evidence for resolved items, and list any outstanding differences, the checks already completed and the information still needed. Refer unexplained balances or accounting questions to your accountant.

2. Review Sales, Customer Balances and Supplier Records

Once the main accounts have been reconciled, review what customers owe the business and what the business owes its suppliers. An aged debtors report helps identify overdue invoices, unallocated payments and balances requiring follow-up. Check disputed invoices and consider whether any outstanding amounts require further assessment rather than assuming that every unpaid invoice will be collected.


On the supplier side, confirm that bills received during the year have been recorded and that outstanding liabilities are included. Compare supplier statements with the balances in your accounting system where available. Investigate discrepancies, check that relevant credit notes have been recorded, and identify costs relating to the period that may not yet have been invoiced. Keep a note of any items requiring further information or review.


These checks help produce a more reliable picture of income, expenses and outstanding balances. They also support year-end accounts preparation by giving the accountant clearer records and a list of items that still require attention.

3. Review VAT and Payroll Records

If the business is VAT-registered, compare the bookkeeping records with the VAT returns submitted and review the VAT control-account balance. Check relevant sales and purchase transactions, investigate unusual balances or VAT codes and confirm that supporting invoices and credit notes are available. Record any differences that need further investigation rather than assuming that a completed VAT return or software reconciliation confirms the figures are correct. Under Making Tax Digital for VAT, businesses generally need to maintain specified VAT records digitally and use compatible software to submit returns, unless an exemption applies. Consistent VAT compliance and bookkeeping help businesses maintain supporting records and identify discrepancies before their figures are finalised. 


For example, a supplier credit note may have been received but not recorded in the bookkeeping system. Check that it has been entered correctly and that the related VAT treatment is supported by the documents and applicable rules.


Payroll records also need to be complete where the business employs staff or pays directors through payroll. Compare payroll summaries with the amounts recorded in the accounts and check that wages, employer National Insurance, pension contributions and other relevant payroll costs have been accounted for correctly. Investigate differences between payroll reports, payments made and the bookkeeping entries rather than assuming that the software has captured every item.


The objective is to identify inconsistencies before the year-end figures are finalised. Specific payroll reporting obligations and deadlines depend on the business’s arrangements and the relevant tax year.

4. Check Fixed Assets, Loans and Other Significant Balances

Review the fixed asset register against purchases and disposals during the year. Check that equipment, vehicles, computers and other business assets have been recorded appropriately, and make sure that disposals or assets no longer held are not left incorrectly on the register. Keep the relevant purchase invoices and disposal records available for review. Depreciation is an accounting adjustment and should be considered in line with the applicable accounting policy.


Loan balances also deserve attention. Compare outstanding amounts with lender statements and separate capital repayments from interest where the accounting treatment requires it. For limited companies, director loan account balances may need particular attention because they can affect the accounts and may have tax implications.


If the business holds inventory, carry out an appropriate stock count at or near the year-end date and compare the results with the accounting records. Investigate differences and identify damaged, obsolete or unsaleable items for review. Stock values can affect reported profit, so adjustments should be supported by evidence and handled in accordance with the applicable accounting requirements.


Not every SME needs a stocktake or a complex asset review. Focus on the balances and transactions relevant to the business, and raise unusual items with the accountant before making adjustments that are not supported by the records.

5. Identify Accruals, Prepayments and Other Year-End Adjustments

Bookkeeping records do not always show the full financial position simply because every bank transaction has been entered. Some income and expenses relate to a different accounting period from the date cash was received or paid. This is why the year-end review should identify potential accruals, prepayments and other adjustments for the accountant to assess.


For example, a utility cost relating to March may be invoiced in April. An annual insurance premium paid during the year may cover months in the following accounting period. A customer may also pay in advance for work that has not yet been completed. These items may require adjustments so that income, expenses, assets and liabilities are presented in the appropriate period.


Prepare the available invoices, contracts, payment details and explanations for these items. The accountant can then determine the appropriate treatment under the applicable accounting framework. Avoid posting unsupported journals simply to reach an expected profit figure. A year-end bookkeeping checklist also helps identify which items are ready for review and which still need supporting evidence.  


Many UK accounting firms use outsourced bookkeeping support to manage year-end workloads efficiently while maintaining established review and compliance procedures.
Need support keeping your books
accurate and organised before year-end?

Our UK bookkeeping specialists help businesses maintain
compliant financial records and prepare accounts-ready bookkeeping.

What Should You Prepare Before Handing Records to Your Accountant?

A good handover gives the accountant the records needed to complete the work, along with enough context to understand anything unusual. Sending a large collection of files without explaining missing documents or unresolved balances can create additional questions and delay the process.


Before handing over the records, organise the following where relevant to your business:

  • Bank and credit card records: Statements and completed reconciliation reports.
  • Sales and supplier records: Sales invoices, supplier bills and details of outstanding customer and supplier balances.
  • VAT information: VAT returns and supporting records, if the business is VAT-registered.
  • Payroll information: Payroll summaries and relevant pension or employment cost information.
  • Assets and loans: Fixed-asset details, purchase and disposal records, and loan statements.
  • Stock records: Stock count results, where the business holds inventory.
  • Unusual transactions: Details of director loan balances and potential year-end adjustments that need review.
  • Missing information: A list of missing documents, disputed balances and questions that remain unresolved.

Alongside the documents, prepare a short exceptions list showing which items remain unresolved, what checks have already been completed and what information is still required. Use your year-end bookkeeping checklist to ensure that outstanding queries are clearly documented and ready for the accountant to review.


The most useful handover is not necessarily the one with the most files. It is the one that makes the status of the records clear. Tell your accountant what is complete, what remains uncertain and where supporting evidence can be found. This helps prioritise outstanding work and distinguish unresolved queries from confirmed accounting adjustments.

How Can You Make the Next Year-End Easier?

Year-end preparation is generally more manageable when bookkeeping is maintained throughout the year rather than left until the reporting deadline approaches. Regular reconciliations, timely invoice processing and periodic reviews of outstanding balances help identify issues while the relevant information is still easy to obtain. Good financial record keeping in the UK involves maintaining accurate records, retaining supporting evidence and making information available when it is needed. 


A simple monthly routine can include reconciling bank and payment accounts, reviewing customer and supplier balances, checking VAT records where applicable, and monitoring other significant balances. Businesses with payroll, stock or more complex transactions may also benefit from scheduled reviews of those areas. Revisiting the year-end bookkeeping checklist throughout the year helps track completed checks and address outstanding items before the reporting deadline.

Record retention requirements depend on the type of record and the business’s circumstances. VAT records generally need to be retained for at least six years, although different requirements may apply to other business and tax records. Check the relevant GOV.UK guidance on VAT records, company accounting records and self-employed records to confirm the applicable requirements.


Keeping documents organised by accounting period, retaining supporting evidence and documenting adjustments also makes it easier to answer questions after the year-end work has been completed.

When Should an SME Consider Additional Bookkeeping Support?

Some businesses can maintain their bookkeeping internally but need help resolving accumulated discrepancies before year-end. Others need more regular support because transaction volumes have grown, the internal team has limited capacity or the business has several reporting requirements to manage. Bookkeeping for small businesses in the UK may be managed internally, supported externally or divided between an internal team and a specialist provider, depending on transaction volumes and available resources.


The appropriate level of support depends on the condition of the existing records, the complexity of the transactions and the work the business expects to retain internally. For businesses reviewing their bookkeeping arrangements, the key consideration is whether the proposed service covers the tasks they need and fits their existing accounting process. Businesses considering outsourced bookkeeping in the UK should establish which tasks are included, who will resolve missing information, how queries will be handled and who is responsible for reviewing and approving the completed work.


Additional bookkeeping support is most useful when responsibilities and handover arrangements are clear. It should help maintain reliable records and a consistent workflow, while the business owner and appointed accountant retain the responsibilities that belong to them.

Why Accounting Firms Benefit from Additional Bookkeeping Capacity at Year-End

As client demands increase during year-end, accounting firms often need additional support to maintain turnaround times and manage routine bookkeeping workloads. Tasks such as bank reconciliations, accounts payable and receivable reviews, VAT record checks and transaction processing can consume substantial internal resources.


Additional bookkeeping capacity can help firms keep client records organised, identify issues earlier and prepare information for year-end accounts preparation. When aligned with existing workflows and review procedures, this support.


The right support model should align with the firm’s existing workflows, quality-control procedures and reporting standards. When responsibilities are clearly defined, additional bookkeeping capacity can help firms maintain service levels, improve efficiency and manage seasonal demand more effectively.

Cross-Country Perspective: Bookkeeping Across the UK, USA and Australia

The core bookkeeping practices are similar across markets: reconcile transactions, retain supporting evidence, review outstanding balances and investigate unusual items before finalising figures. However, statutory and tax requirements vary by jurisdiction.


For example, US businesses may need to maintain records for federal and state tax reporting, while Australian businesses may need records for Business Activity Statements (BAS) and other Australian Taxation Office obligations. These requirements differ from UK VAT, Companies House and HMRC processes. Businesses operating across countries should maintain consistent internal processes while applying the rules relevant to each entity and jurisdiction.

Strengthen your year-end delivery process with bookkeeping capacity that integrates with your practice workflows, reporting standards and review procedures.

Preparing for Year-End: Next Steps

A structured year-end bookkeeping process helps UK SMEs identify discrepancies, organise supporting records and prepare outstanding questions before the accounts are finalised. Regular reconciliations and a clear handover can also reduce avoidable delays.


At Unison Globus UK, our accounting and bookkeeping services in the UK support UK accountancy practices with accounting and bookkeeping workflows that fit their existing processes. Our AI-ready professionals can work within clients’ existing technology environments, including AI-enabled platforms where appropriate, combining accounting expertise with platform fluency to prepare work for review.


For limited companies, remember that annual accounts filing, Corporation Tax payment and Company Tax Return deadlines are separate. Late filing can result in penalties. Check the relevant GOV.UK guidance on company accounts and tax returns and Companies House late-filing penalties for the applicable requirements.

Frequently Asked Questions

Reconcile bank accounts, review customer and supplier balances, check VAT and payroll records, verify relevant assets and liabilities, and identify potential year-end adjustments.

Maintain reconciliations and process invoices throughout the year. Begin a focused year-end review before the reporting date where possible, allowing time to resolve discrepancies and obtain missing documents.

Yes. Accounting software helps organise transactions, but year-end checks are still needed to identify missing records, incorrect entries, unexplained balances and adjustments requiring review.

Provide relevant bank statements, reconciliation reports, sales invoices, supplier bills, VAT and payroll records, loan statements, asset details and stock records. Include a list of missing documents and unresolved queries where applicable.

Retention periods depend on the type of record and the business structure. VAT records generally need to be kept for at least six years, while different requirements apply to company and self-employed records.

Many bookkeeping checks are similar, but reporting obligations differ. Limited companies must meet statutory accounts and Corporation Tax requirements, while sole traders generally use their business records to prepare Self Assessment.

Yes. Depending on the agreed scope, they may help reconcile transactions, investigate discrepancies and organise records for review. Confirm responsibilities, exclusions and how outstanding queries will be handled before work begins.
Categories
Bookkeeping home uk VAT Services

Reducing VAT Errors Through Real-Time Bookkeeping: A Strategic Guide for UK Accounting Firms

It usually starts with one bank transaction. The transaction can be processed, but the supporting evidence has not arrived, so it gets left “for later”.

Then another transaction requires client confirmation before its VAT treatment can be finalised, while a bookkeeping correction is deferred rather than resolved. Across bookkeeping and VAT services in the UK, these unresolved items can remain open simply because they are not considered urgent enough to interrupt the current workflow. 

The issue for UK accounting practices is therefore not simply technical competence. It is how consistently exceptions are identified, assigned, resolved, and cleared before they reach VAT review.

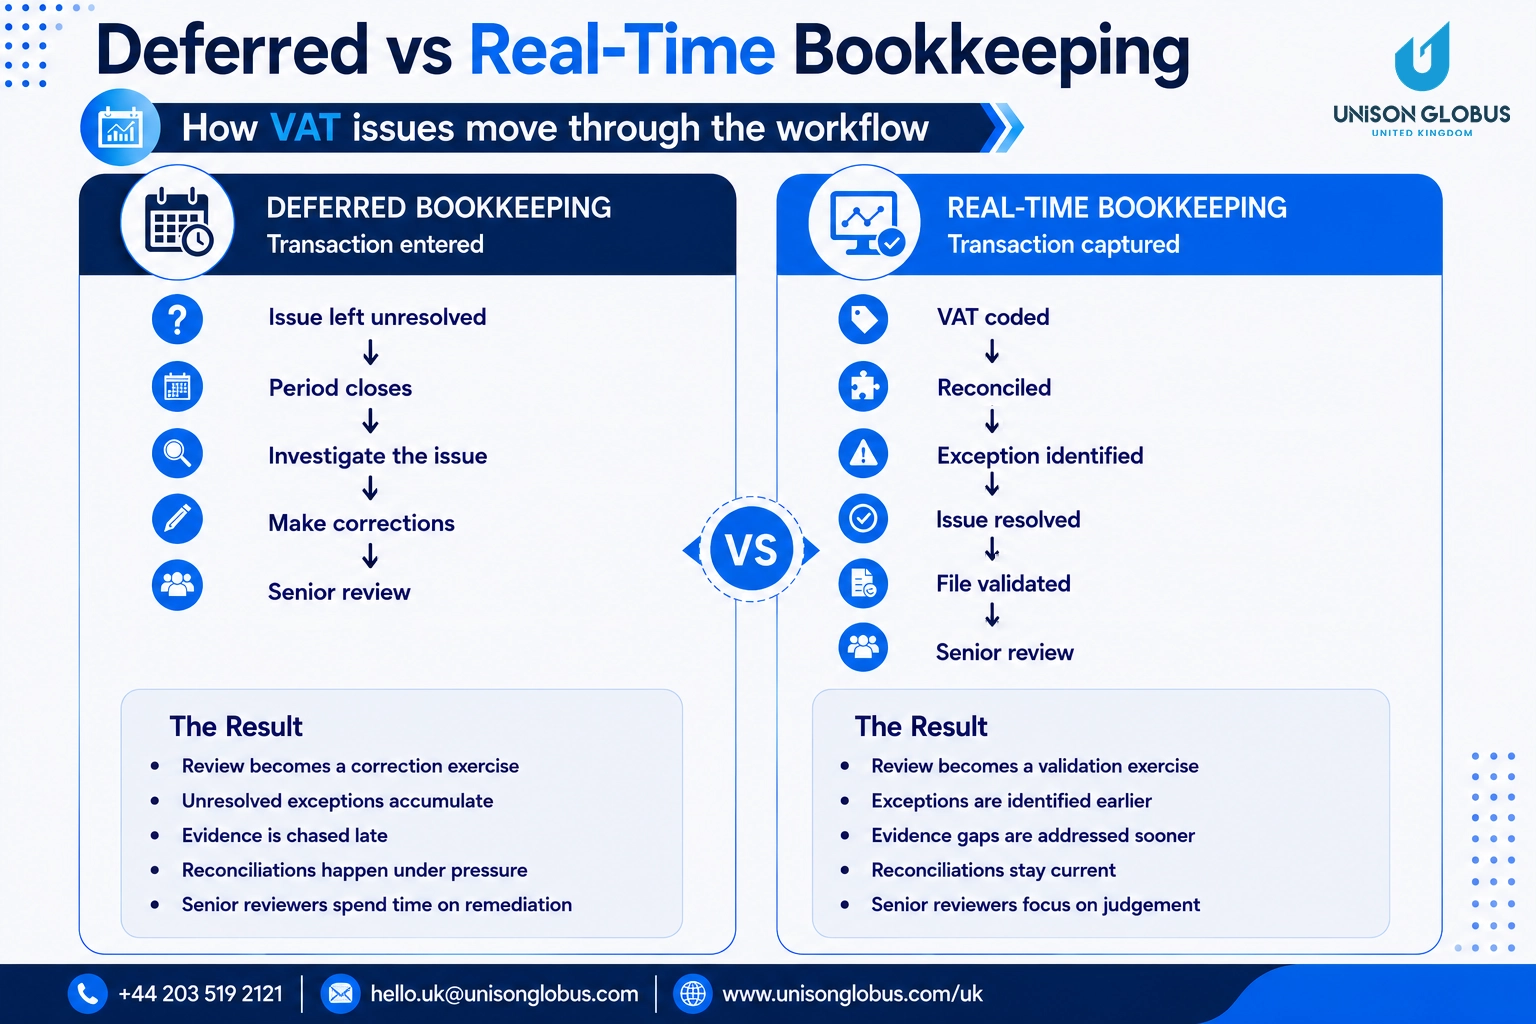
The workflow difference is straightforward:

  • Deferred: Transaction → unresolved → period closes → investigate → correct → review
  • Real-time: Transaction → identify exception → resolve → reconcile → validate → review

When these controls operate throughout the bookkeeping cycle, VAT preparation can begin with a substantially complete file rather than a queue of unresolved issues. The result is a shift in review from finding and fixing routine problems to validating the VAT position.

TL;DR

  • Deferred bookkeeping, including missing evidence, unresolved queries, and delayed corrections, can turn VAT review into a correction exercise rather than a validation step.
  • Real-time bookkeeping is a control framework that moves reconciliation, VAT coding, evidence capture, and exception resolution closer to transaction entry.
  • HMRC’s 2025 MTD evaluation found that 48% of businesses kept VAT records continuously up to date, compared with 38% before MTD. It also found that 67% identified at least one-way MTD had reduced potential mistakes.
  • MTD requires digital records, compatible software, and relevant digital links, but real-time bookkeeping itself is a firm-level workflow choice.
  • A practical VAT error-prevention framework covers six stages, from client onboarding and routine bookkeeping through MTD checks, senior VAT review, and pre-submission controls.
  • The objective is to resolve routine bookkeeping issues earlier so senior reviewers can focus on technical judgement, while defined external support can assist with execution where appropriate.

What Deferred Bookkeeping Actually Costs a UK Accounting Practice

For an accounting practice, the cost of deferred bookkeeping becomes most visible when routine remediation starts consuming review time and disrupting planned workflow. Incomplete records can delay VAT preparation because the file is not sufficiently complete to proceed. The issue is not the preparer’s technical capability, but whether the underlying bookkeeping has been sufficiently completed and controlled before the file reaches VAT preparation.


When basic bookkeeping issues remain unresolved, they can carry into later stages of the workflow. Senior reviewers may then spend time resolving bookkeeping matters rather than validating technical positions. At the same time, unanswered client queries can delay progress further, particularly when supporting evidence has not been requested early enough.


As these issues recur, workflow and resource planning become less predictable. Review effort starts to depend on how much remediation a file requires rather than on the technical assessment planned for that stage.


The effect can also extend to the client relationship. When evidence requests and bookkeeping queries arrive late or are repeated, clients may experience the process as reactive rather than controlled.


The operational impact becomes clearer when each deferred bookkeeping issue is traced to the work it creates downstream:

Deferred Issue Downstream Impact
Unreconciled transaction Reconciliation rework
Missing VAT evidence Client query
Incorrect VAT code Return correction
Unresolved exception Senior review time
Repeated bookkeeping error Recurring compliance risk

This is why VAT compliance UK bookkeeping should be considered an upstream control issue rather than something addressed only during VAT return preparation.

Stop VAT backlogs before review. Let Unison Globus UK keep your client files reconciled and exception-free.

What the UK Data Says About Digital Accounting and Client Expectations

HMRC’s 2025 final evaluation of Making Tax Digital for VAT supports the case for earlier issue detection.


HMRC’s 2025 evaluation, drawing on IFF Research involving 2,005 businesses mandated in 2019, found that 48% kept VAT records continuously up to date, compared with 38% before MTD. It also found that 67% identified at least one-way MTD had reduced potential mistakes.


The finding matters because more frequent digital record updates change when errors can be identified. This is particularly relevant when considering how VAT errors UK businesses encounter can arise from incomplete records, inconsistent coding, or unresolved transaction exceptions.


HMRC’s evaluation also found that 53% of businesses mandated in 2019 felt more confident about getting their VAT right after adopting MTD. Among businesses using fully functional software, that figure rose to 59%.


For a practice leader, the implication is practical. Digital record keeping is not simply a compliance requirement. It can create more frequent opportunities to identify discrepancies before they become period-end problems.


The question is whether the accounting firm’s own workflow uses those opportunities or still relies on quarterly catch-up.

Real-Time Bookkeeping Is a Control Framework, Not Just a Faster Bookkeeping Process

Real-time bookkeeping is best understood as a control framework. It moves reconciliation, evidence capture, coding checks, and exception handling closer to transaction entry.


The objective is not to process transactions simply because technology makes faster processing possible. The objective is to prevent unresolved issues from accumulating. For UK accounting firms, this connects bookkeeping controls with VAT reporting discipline, while MTD requirements govern the relevant digital records and data flows.


A controlled workflow follows:

Capture → Code → Reconcile → Exception → Resolve → Validate → Review


Each stage has a specific purpose.

  • Capture: Bring transactions and supporting evidence into the accounting environment.
  • Code: Apply the appropriate accounting and VAT treatment.
  • Reconcile: Confirm transactions agree with underlying records.
  • Exception: Identify items requiring further investigation or judgement.
  • Resolve: Assign and clear the exception before it moves downstream.
  • Validate: Confirm the file is complete and internally consistent.
  • Review: Apply professional judgement to material, unusual, or technically complex matters.

This approach supports accurate VAT reporting while also improving the quality of current-period financial information.


A reconciled file can support broader client conversations more effectively than a file that still requires basic bookkeeping reconstruction.

The Real-Time VAT Error Prevention Checklist for UK Accounting Firms

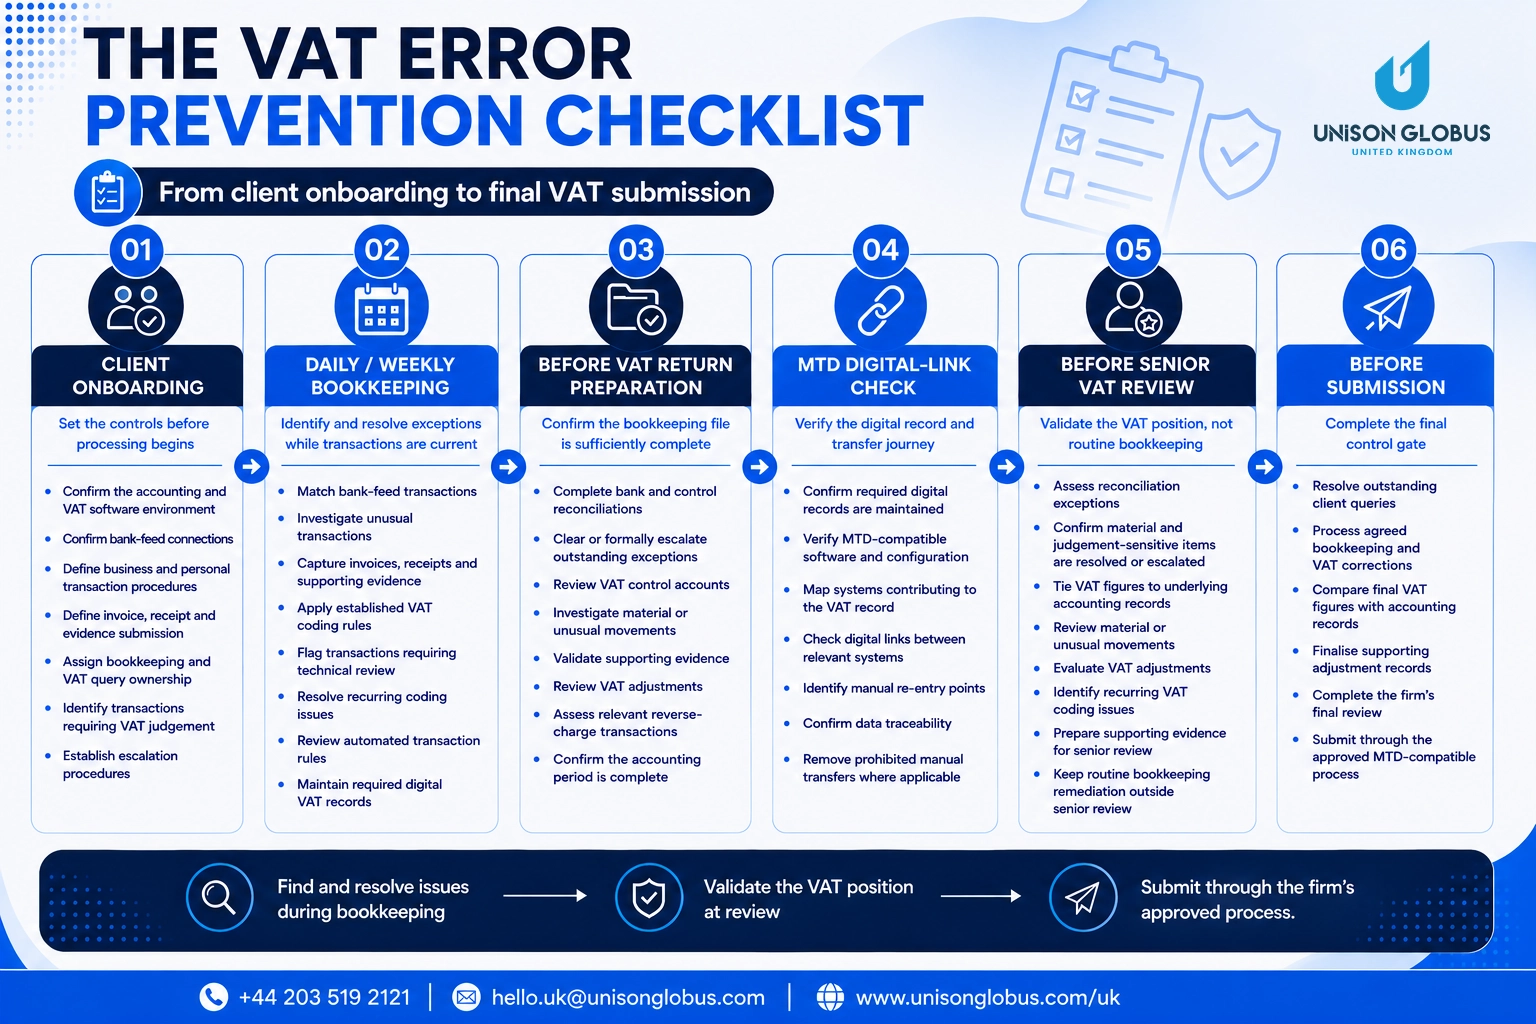
The most effective control framework follows the client file chronologically, strengthening bookkeeping first, controlling VAT error risks throughout, and verifying relevant MTD requirements before submission. For firms delivering bookkeeping services for VAT compliance, this means embedding VAT checks into routine bookkeeping rather than treating them as a separate period-end activity. 


At Client Onboarding

VAT error prevention begins before routine transaction processing. Establish the operating model and escalation routes at the start:

  • Confirm the software environment: Record the accounting and VAT platforms used by the client and practice.
  • Confirm bank-feed connections: Establish which relevant accounts are connected and how transaction data enters the ledger.
  • Define transaction boundaries: Establish procedures for identifying business and personal transactions.
  • Assign query ownership: Establish who answers bookkeeping and VAT queries and how unresolved items are escalated.
  • Identify judgement areas: Flag transaction types likely to require technical VAT consideration.
  • Set escalation procedures: Establish a clear route for uncertain VAT treatment rather than allowing items to remain unresolved.

The objective is to establish controls for VAT compliance in UK bookkeeping before transaction volume creates an exception backlog. 

During Daily or Weekly Bookkeeping

Routine processing is where many preventable exceptions should be identified. The workflow should make unresolved items visible:

  • Match bank-feed transactions: Reconcile transactions at an appropriate frequency based on transaction volume and risk.
  • Investigate unusual transactions: Flag items that do not fit established client patterns or coding rules.
  • Capture supporting evidence: Attach available invoices, receipts, and other relevant documents to transactions during processing, and raise missing items as exceptions.
  • Apply VAT codes: Apply established coding rules during processing rather than correcting large batches before review.
  • Identify technical exceptions: Route genuinely uncertain VAT treatments to the appropriate reviewer.
  • Resolve recurring issues: Correct the underlying cause when the same coding problem repeatedly appears.
  • Review recurring rules: Check automated transaction rules periodically for continued suitability.
  • Maintain digital records: Record the VAT information required in functional compatible software, while retaining invoices, receipts, and other supporting records in the form required by VAT rules.

This is where digital bookkeeping becomes a control mechanism rather than simply a method of recording transactions.


It also supports digital VAT record keeping UK practices by keeping required VAT information and supporting documentation organised within the firm’s broader bookkeeping workflow.

Before VAT Return Preparation

Before VAT return preparation for UK businesses begins, the bookkeeping file should pass a defined completion gate:

  • Complete reconciliations: Confirm relevant bank and control reconciliations are complete, with routine discrepancies resolved.
  • Clear exceptions: Resolve or formally escalate outstanding bookkeeping items that could affect VAT preparation.
  • Review VAT control accounts: Investigate balances that do not reconcile with underlying activity.
  • Investigate movements: Review material or unusual period-on-period changes before the file moves into VAT preparation.
  • Validate evidence: Confirm that supporting documentation is sufficient for material, unusual, or VAT-sensitive transactions.
  • Review adjustments: Check that relevant VAT adjustments have appropriate explanations and supporting records.
  • Review reverse charges: Where applicable, identify and assess relevant reverse-charge transactions before VAT preparation.
  • Confirm period completion: Establish that the accounting period is sufficiently complete for VAT preparation to begin.

HMRC’s VAT record-keeping guidance sets out the records VAT-registered businesses must keep and states that business records generally need to be retained for at least six years.


The result should be a VAT-ready bookkeeping file, with routine exceptions addressed, required evidence available, and the underlying records sufficiently controlled to support VAT preparation and the relevant MTD process.

MTD Digital-Link Check

MTD creates specific requirements around digital records, compatible software, and digital links. These requirements form part of the wider HMRC VAT compliance requirements for MTD reporting, while real-time bookkeeping remains a firm-level control choice.


Use this control point to assess:

  • Confirm digital records: Verify that the VAT information required for the electronic account is maintained digitally in functional, compatible software.
  • Confirm compatible software: Check the specific software and configuration being used.
  • Map software connections: Identify every system contributing to the VAT record.
  • Check digital links: Confirm that transfers within the functional, compatible software journey meet HMRC’s digital-link requirements.
  • Identify manual re-entry: Locate points where figures are manually retyped between systems.
  • Confirm traceability: Ensure figures can be followed through the relevant digital record journey.
  • Review transfer procedures: Eliminate manual transfers where HMRC requires a digital link, while documenting permitted manual inputs within the digital-record workflow.

HMRC states that digital links can include API transfers, XML, CSV imports and exports, and automated transfers. Copy-and-paste is not considered a digital link.


HMRC Guidance: Digital links and acceptable transfer methods under MTD for VAT. View HMRC VAT Notice 700/22

This makes Making Tax Digital VAT bookkeeping a practical control within the wider VAT error-prevention workflow.


The same principle applies to MTD compliance bookkeeping for UK firms operating across multiple software environments. The key issue is whether required digital records and their relevant transfers remain compliant, traceable, and connected to accurate underlying bookkeeping and VAT reporting.

Before Senior VAT Review

Senior review should validate the VAT position rather than repair basic bookkeeping. The focus should shift from file completeness to professional assessment:

  • Assess reconciliation exceptions: Focus on unusual reconciling items, unexplained balances, or exceptions requiring professional assessment rather than repeating routine reconciliation work.
  • Assess material exceptions: Confirm that material or judgement-sensitive items have a documented resolution, escalation rationale, and supporting evidence.
  • Validate VAT figures: Tie VAT figures back to the underlying accounting records and investigate material variances.
  • Assess unusual movements: Review significant or unusual changes where the explanation may affect the VAT position or require professional judgement.
  • Evaluate adjustments: Assess whether VAT adjustments are appropriate, supported, and consistent with the underlying transaction and applicable treatment.
  • Identify recurring coding issues: Determine whether recurring VAT coding patterns indicate a broader workflow, training, or client-process issue.
  • Prepare review evidence: Ensure material VAT judgements, adjustments, and technical matters are supported by the documentation or explanations required for senior review.
  • Protect reviewer time: Keep routine bookkeeping remediation outside the senior review wherever appropriate.

This is where VAT compliance support accounting firms can use defined external execution to keep routine bookkeeping work ahead of senior review. The aim is to move routine bookkeeping execution and correction earlier so senior professionals can focus on technical assessment, judgement, and review.

Before Submission

The final stage should operate as a control gate:

  • Resolve client queries: Confirm outstanding questions affecting the return have been answered.
  • Process corrections: Ensure agreed bookkeeping and VAT corrections are reflected in the file.
  • Review the return: Compare final VAT figures with the accounting records.
  • Finalise adjustment records: Confirm approved VAT adjustments are reflected in the return and supported by the required explanations and documentation.
  • Complete final review: Follow the firm’s established approval procedure.
  • Submit appropriately: Following the firm’s final approval, use its approved MTD-compatible submission process.

The strongest workflow makes submission the final validation point, not the first opportunity to discover incomplete records.

Use HMRC Error-Correction Rules as a Control Reference, Not an Error Tolerance

HMRC provides specific routes for correcting VAT errors already discovered. Those routes should never be treated as an acceptable level of bookkeeping inaccuracy.


Under Method 1, the net value of previous-return errors can generally be adjusted on the current VAT Return where the amount does not exceed £10,000. Errors between £10,000 and £50,000 can also use Method 1 where they do not exceed 1% of Box 6 for the return period in which the errors are discovered. Net errors greater than £50,000, or errors between £10,000 and £50,000 that exceed the applicable 1% Box 6 test, require Method 2 notification. The applicable correction methods and limits are set out in HMRC’s VAT error-correction rules.


HMRC also states that deliberate errors must use Method 2. Where a Method 1 correction resulted from careless conduct, separate disclosure may be required to obtain the maximum penalty reduction.


The operational distinction is important:

Regulatory Framework Operational Objective
Understand correction thresholds Detect errors early
Follow HMRC correction routes Resolve underlying bookkeeping issues
Assess material errors correctly Prevent recurring errors
Document appropriate corrections Strengthen review controls

Therefore, MTD VAT errors solutions should focus on earlier detection and root-cause correction rather than treating regulatory thresholds as acceptable error levels.

Warning:

The £10,000 figure is a regulatory correction limit. It is not an acceptable-error allowance or a bookkeeping target.

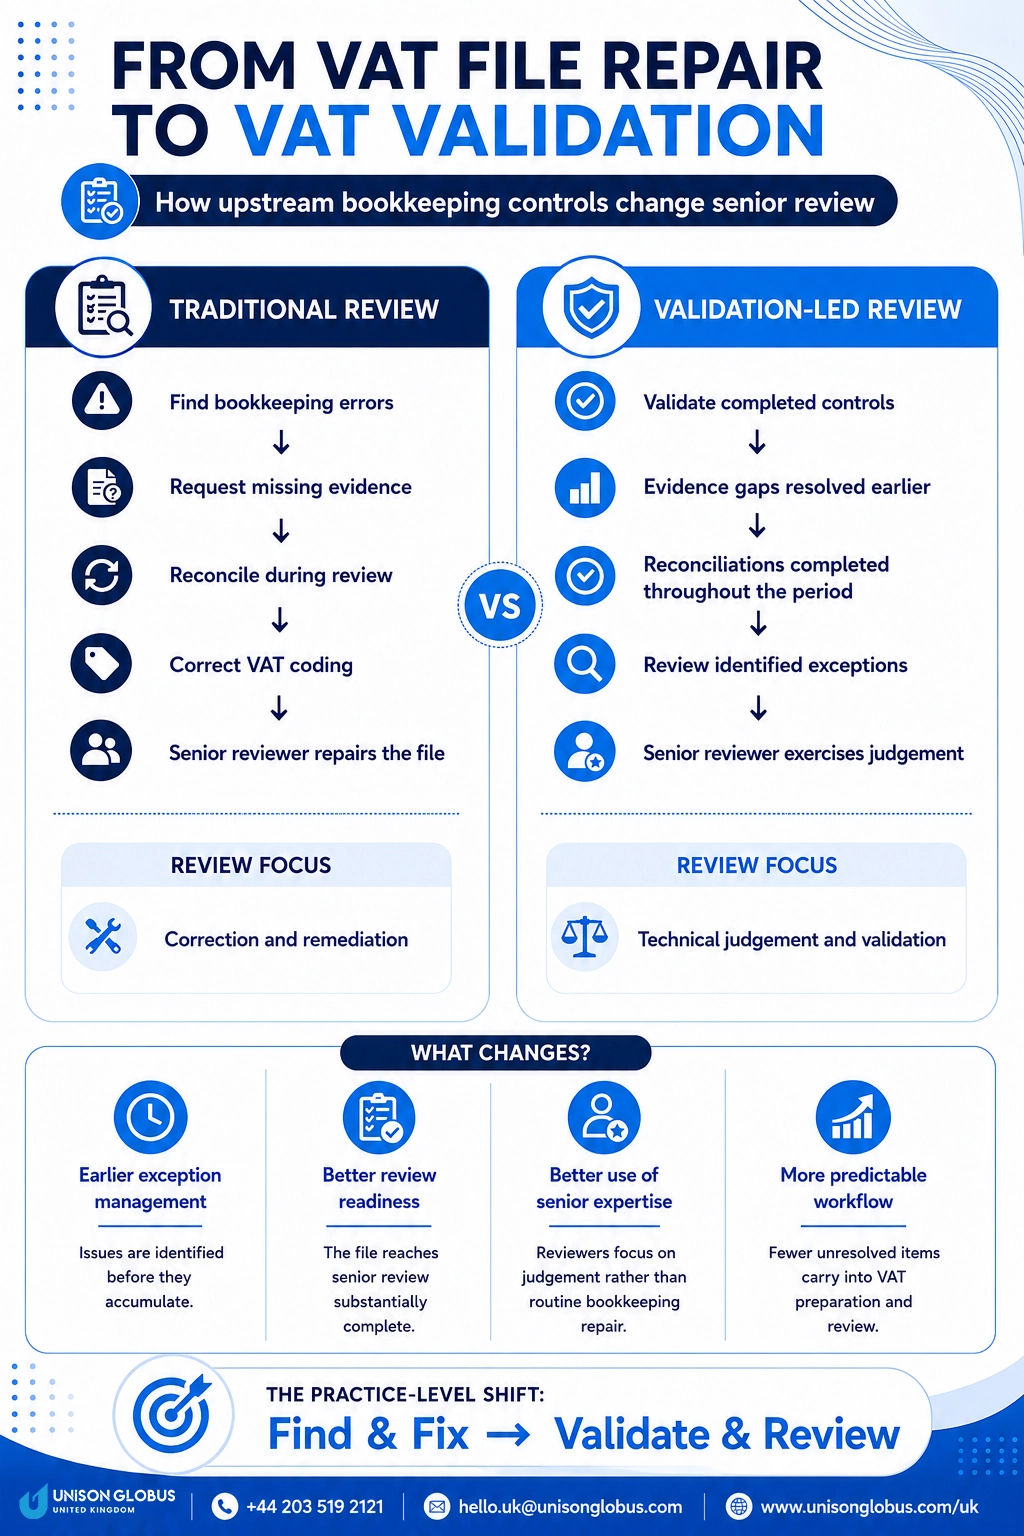
Turn the Final VAT Review into a Validation Exercise

A well-controlled bookkeeping workflow changes the purpose of senior review.


The file arrives substantially complete. Reconciliations have been performed. Exceptions have owners. Supporting evidence has been collected. The reviewer can focus on technical judgement and unusual transactions.


The distinction is straightforward:

Traditional Review Real-Time Workflow
Find bookkeeping errors Validate completed controls
Request missing evidence Resolve evidence gaps earlier
Reconcile during review Reconcile throughout the period
Correct VAT coding Review identified exceptions
Senior reviewer repairs file Senior reviewer exercises judgement

This also makes review findings more useful.


A recurring VAT coding issue should not simply be corrected and forgotten. It should feed back into the bookkeeping rule, client instruction, training point, or escalation procedure that caused the problem.


That creates a practical improvement cycle:


Exception identified → Cause assessed → Process improved → Recurrence monitored


The outcome is stronger Value Added Tax solutions because VAT control becomes part of the broader bookkeeping operating model.

The Technology Behind a Real-Time Bookkeeping Workflow

A real-time bookkeeping workflow does not depend on adopting a new technology stack. The priority is using existing systems to support earlier visibility, exception management, reconciliation, and evidence capture.


Common capabilities include:

  • Bank feeds: Bring transaction activity into the accounting system regularly, allowing unmatched or unusual items to be identified earlier.
  • Receipt and invoice capture: Connect supporting evidence to transactions while the underlying activity is still current.
  • Automated matching: Reduce routine unmatched transactions while leaving exceptions for appropriate review.
  • Cloud accounting platforms: Maintain connected accounting records and support access across the practice’s workflow.
  • Practice workflow tools: Assign bookkeeping tasks, track outstanding queries, and make unresolved exceptions visible.

Accounting platforms such as Xero, QuickBooks, and Sage can support elements of a real-time bookkeeping workflow, depending on the product, configuration, and client environment.


The important distinction is that technology enables the control framework; it does not create the control framework by itself.


For example, an automated bank feed may improve transaction visibility, but someone still needs to investigate an unusual transaction. Receipt capture may make evidence available sooner, but the supporting document still needs to be assessed. Automated matching can reduce routine work, but exceptions still require appropriate review.


The control model therefore remains:


Technology → visibility → exception identification → human assessment → resolution → review


This also explains why software capability should not be treated as equivalent to MTD compliance. Firms still need to verify their specific software configuration, digital records, digital links, and submission processes against the applicable HMRC requirements.


For practice leaders, the more useful question is: Does the current technology help the team identify, assign, resolve, and document bookkeeping exceptions before they reach senior VAT review?


If the answer is no, the underlying issue may be workflow execution rather than technology selection.

The Checklist Is Straightforward. Consistent Execution Is the Challenge.

The controls themselves are familiar. The operational challenge is maintaining them consistently across every client file. Without clear ownership, reconciliation queues, evidence requests, and unresolved exceptions can accumulate, drawing senior staff into routine remediation. The issue is therefore not whether the firm has defined bookkeeping controls, but whether those controls are executed consistently across the client portfolio.


This is where outsourced bookkeeping can have a defined operational role.


The question is not whether every bookkeeping activity should be outsourced. It is whether specific, repeatable activities can be supported externally while the accounting firm retains technical judgement and professional oversight.


For practices evaluating Outsourced Bookkeeping Services for UK Accountants, the starting point should therefore be the workflow, not the provider.

Where Outsourced Bookkeeping Can Support the Workflow

External support can help execute defined bookkeeping activities consistently within the firm’s existing systems and review framework.


Potential activities include:

  • Transaction processing: Process routine transactions according to agreed client-specific procedures.
  • Reconciliation support: Complete defined bank and account reconciliations before internal review.
  • Document follow-up: Track missing invoices, receipts, and supporting evidence.
  • Exception preparation: Identify and organise items requiring client or technical review.
  • Workflow continuity: Maintain recurring bookkeeping activities across the client portfolio.
  • Review readiness: Deliver files according to the firm’s established completion standards.

The accounting firm should retain client ownership, technical VAT judgement, client advice, approval, and submission responsibility.


For firms considering whether to outsource bookkeeping and VAT UK workflows, the same principle applies. External support should fit the firm’s control framework rather than create a separate process.


A practical evaluation should cover:

  • UK accounting expertise: Confirm the provider understands UK bookkeeping, VAT, and practice workflows.
  • Software compatibility: Ensure work can be completed within the firm’s established systems.
  • Data security: Assess controls around confidential client information.
  • Defined responsibilities: Document exactly which activities sit with each team.
  • Exception management: Establish how uncertain transactions are escalated.
  • Review controls: Define how completed bookkeeping is handed into the firm’s existing review, approval, and escalation process. 
  • Communication: Agree query routes, ownership, and escalation procedures.
  • Scalability: Confirm the model can operate consistently across the client portfolio.

For firms assessing offshore bookkeeping UK firms, these controls are more important than simply comparing delivery models.


The relevant question is whether the external team can execute defined work consistently while remaining integrated into the firm’s workflow.


Unison Globus UK provides bookkeeping support including transaction recording, reconciliations, VAT and tax preparation assistance, and integration with accounting platforms such as QuickBooks, Xero, and Sage.

Build the Control Before the Review, Not During It

The strongest VAT error controls are established before the VAT return reaches senior review.


An unresolved transaction identified during routine bookkeeping is easier to investigate than one discovered after the period closes. Missing evidence requested early is easier to obtain than evidence chased during final review.


The strategic shift is therefore:


Find and fix → Validate and review


For firms delivering Bookkeeping and VAT services in the UK, the objective is not simply to process transactions more frequently. It is to establish a repeatable control environment where reconciliation, evidence collection, VAT coding, exception management, and review readiness happen at the right point in the workflow.


That can support more reliable VAT reporting, stronger compliance controls, fewer unresolved bookkeeping issues, more predictable reviews, and better use of senior accounting expertise.


Unison Globus UK supports accounting firms with outsourced bookkeeping and accounting services, including transaction processing, bank and account reconciliations, VAT preparation support, financial reporting, and year-end accounts preparation. Our teams work within defined client procedures and existing accounting platforms, supporting consistent execution while the firm retains professional oversight, technical VAT judgement, client relationships, approval, and submission responsibility.


Contact Unison Globus UK to discuss how defined bookkeeping and VAT support can strengthen your firm’s workflow and review readiness.

Move from "find and fix" to "validate and review" with Unison Globus.

Frequently Asked Questions

No. Real-time bookkeeping is optional. MTD requires digital records, compatible software, and relevant digital links, but not continuous transaction processing.

It moves reconciliation, evidence capture, VAT coding, and exception resolution closer to transaction entry, reducing unresolved issues before VAT preparation.

Firms should verify reconciliations, VAT control accounts, supporting evidence, adjustments, unusual movements, and relevant transaction records before the return moves into preparation.

Confirm that transfers within the functional, compatible software journey use permitted digital links and that prohibited manual transfers are not used where links are required.

Method 1 generally covers errors up to £10,000, or larger errors meeting HMRC’s 1% Box 6 test, subject to the £50,000 limit.

Consider it when recurring bookkeeping creates backlogs or unresolved exceptions. Bookkeeping and VAT services UK can support defined execution while the firm retains professional oversight.